
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
SPX Technologies (SPXC) Draws Fresh Earnings Optimism, Is It A Bargain?
Analyst commentary around SPX Technologies (SPXC) has turned into the main story, with a positive Earnings ESP and recent estimate beats drawing attention even as some firms trim fair value assumptions due to HVAC and data center risk.
SPX Technologies shares have retreated from recent highs, with a 30-day share price return down 13.11% and a year-to-date share price return down 16.06%. However, the 3-year total shareholder return is up 106.91% and the 5-year total shareholder return is up 193.72%. This suggests long term holders have still seen strong compounding while recent sentiment has cooled as investors reassess HVAC and data center risks against the upbeat earnings commentary.
Scan how SPX Technologies stacks up against peers exposed to HVAC, power and AI infrastructure by reviewing the hand picked 43 power grid technology and infrastructure stocks in the same space.The share price reset and the wide gap between SPX Technologies at about US$171 and analyst fair value estimates up near US$257 put the real question on the table: Where does fair value actually sit in that spread?
Most Popular Narrative: 16% Undervalued
On the numbers, the most followed valuation narrative for SPX Technologies lines up a fair value of $203 against the last close near $171, which puts the current pullback in a different light for anyone focused on long term cash flows instead of short term sentiment.
The liquid cooling shift underneath this stock is one of the more genuinely interesting structural stories in industrials right now, and SPX Technologies is a legitimate, well-built way to eventually own it. I'd just rather fall in love with it at a price that doesn't need me to be right about everything.
See why 36 investors see SPX Technologies as 16% undervalued.
According to John_Eric, that narrative fair value is built off a discounted cash flow framework that weighs SPX Technologies on its ability to keep turning current earnings quality and backlog into future cash generation, rather than on headline multiples or short term share price moves. The discount rate used in that work is 8.52%, which is relatively grounded for an industrial group with US$2.5b in annual revenue, an 11.5% net margin, and a meaningful presence in HVAC and detection equipment across the US, Canada, the UK, China and other markets.
There is tension between that narrative and the current signals from Simply Wall St's SWS DCF model, which points to a future cash flow value of $240.55 per share compared with the $170.62 last close. That is a very wide gap for a business already producing $285.0m in net income and growing both revenue and earnings at double digit rates year on year.
Analyst targets add another reference point. The average price target of $257.36 is 50.8% above the latest trading level and the analyst group is described as being in a statistically confident range of agreement. For readers, that means three different valuation lenses, the narrative DCF at $203, the SWS cash flow estimate at about $241, and the analyst target cluster around $257, are all sitting comfortably above where the stock currently changes hands.
Each approach has trade offs. The narrative built by John_Eric leans more heavily on a specific set of growth paths and margin assumptions for SPX Technologies, including the rapidly expanding HVAC backlog and the buildout costs that have compressed segment margins. The SWS DCF model standardises assumptions across the wider market, which can help avoid overfitting a single story but may not fully capture data center specific tailwinds and risks. Analyst targets, while forward looking, rely on brokerage level inputs that can shift rapidly around quarterly earnings and sector sentiment.
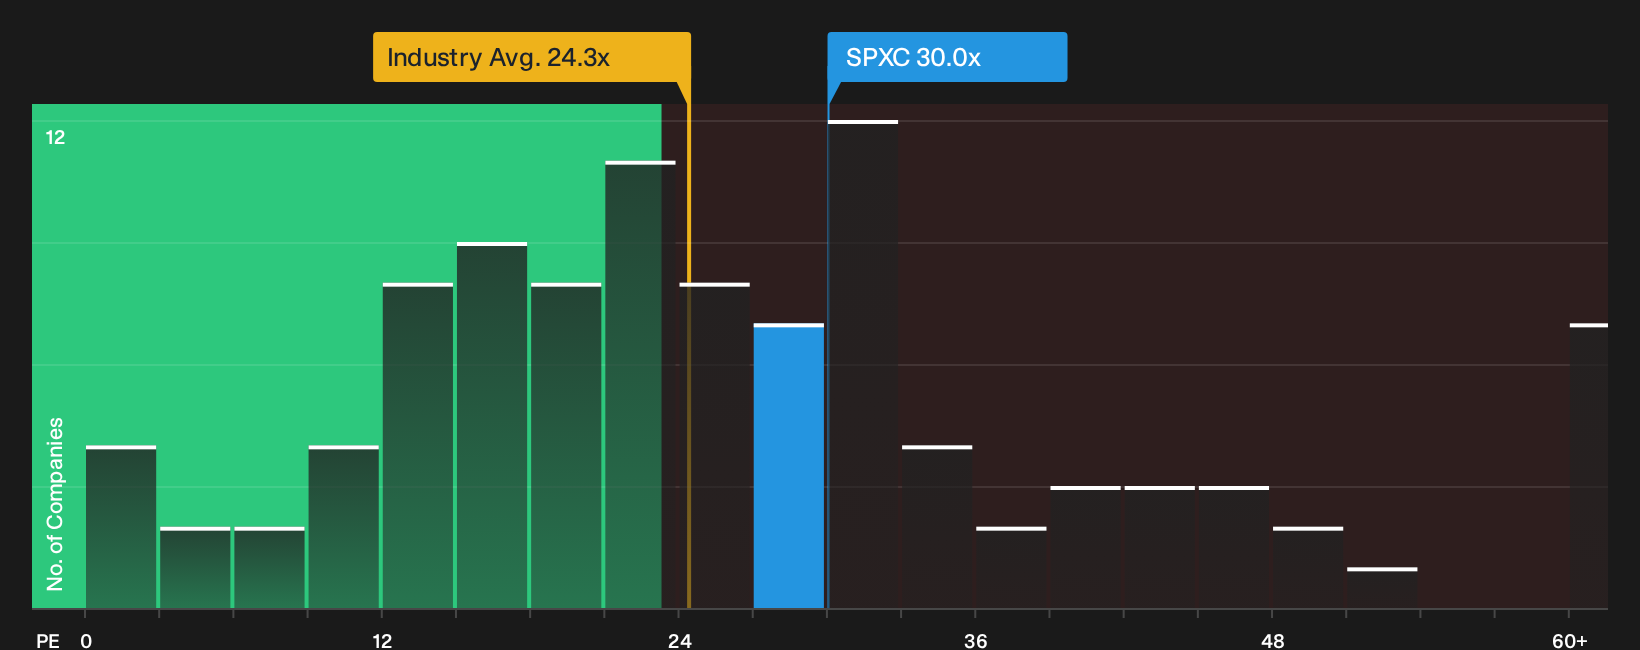
For long term investors, the useful takeaway is not that one number is "right", but that three separate valuation frameworks currently cluster well above the live price while still flagging real trade offs. Those trade offs include a P/E ratio of 30x that screens as expensive versus both the Machinery industry average of 24.3x and an estimated fair P/E of 28.1x, plus a forecast return on equity of 16% that is described as low and revenue growth expectations that trail the broader US market. On the other side of the ledger sit 5 year earnings growth of 35.5% per year, high quality profits, and a 3 year total shareholder return above 100% even after the recent pullback.
Result: Fair Value of $203 (UNDERVALUED)
Still, the SPX Technologies story can break if data center orders cool faster than expected or if HVAC margin pressure lingers longer than current enthusiasts hope.
Find out about the key risks to this SPX Technologies narrative.
Another View On SPX Technologies: What The P/E Is Telling You
That $203 fair value from the user DCF reads as supportive, yet the live P/E of 30x presents a more demanding picture. SPX Technologies trades richer than the Machinery industry at 24.3x and also above a fair ratio of 28.1x, which leaves less room for disappointment if growth or margins slow.
If the market eventually moves back toward that fair ratio, current holders are relying on earnings to keep doing the heavy lifting. The question for anyone looking at SPX Technologies is simple: Are you comfortable paying a premium valuation while HVAC and data center risks are still in play, or would you rather wait for that gap to narrow before acting?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Feeling conflicted about the mix of premium valuation and data center risk around SPX Technologies right now is completely reasonable, especially after such a strong multi year track record. Act quickly on that uncertainty by reviewing the full breakdown of potential upsides through the 4 key rewards.
Looking for more SPX Technologies style investment ideas?
Do not let your research stop with SPX Technologies. Broaden your watchlist with fresh ideas that line up with the kind of quality and risk profile you actually want.
- Target durable cash flows by reviewing the 8 dividend fortresses that focus on higher yields with underlying business strength.
- Hunt for mispriced opportunities by scanning the 20 high quality undiscovered gems that rarely show up on mainstream radars.
- Prioritise capital protection by reviewing the 31 resilient stocks with low risk scores that emphasise resilience over drama.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com