
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
National Health Investors (NHI) Stock Dropped, What Is Behind The Latest Attention?
National Health Investors (NHI) recently committed US$107.7 million to acquire six senior housing properties with 443 units across Kentucky, Michigan and Tennessee. These properties will be incorporated into its Senior Housing Operating Portfolio, which is managed by Allegro Living Management.
Recent trading shows that momentum in National Health Investors has cooled, with the share price down 9.8% over the past month and 16.8% year to date. This comes even though the 3 year and 5 year total shareholder returns of 46.7% and 54.1% point to a much stronger longer run record.
Spot opportunities around National Health Investors by scanning a curated list of solid balance sheet and fundamentals (25 results) that may benefit from similar sector themes and real estate income profiles.The share price slide now sits beside fresh investment in new properties. For National Health Investors, is this mainly about changing views on the business, or a reset in sentiment that shapes what you are paying today?
Most Popular Narrative: 21.9% Undervalued
On the latest numbers, the most followed narrative puts National Health Investors’ fair value at $81.88, compared with a last close of $63.96, which frames the recent share price pullback against a higher long term value estimate built on its senior housing strategy.
Capital recycling from the completed US$560 million sale of the NHC portfolio, coupled with the use of 1031 exchanges and roughly US$792–960 million of available liquidity, provides capacity for new senior housing investments that can influence future rental revenue and FFO once fully deployed.
See why 18 investors see National Health Investors as 22% undervalued.
Result: Fair Value of $81.88 (UNDERVALUED)
Still, the bullish narrative around National Health Investors could be challenged if weaker SHOP performance at legacy Holiday properties persists, or if higher G&A costs linger without clear operating payoffs.
Find out about the key risks to this National Health Investors narrative.
Another View: What Multiples Say About National Health Investors
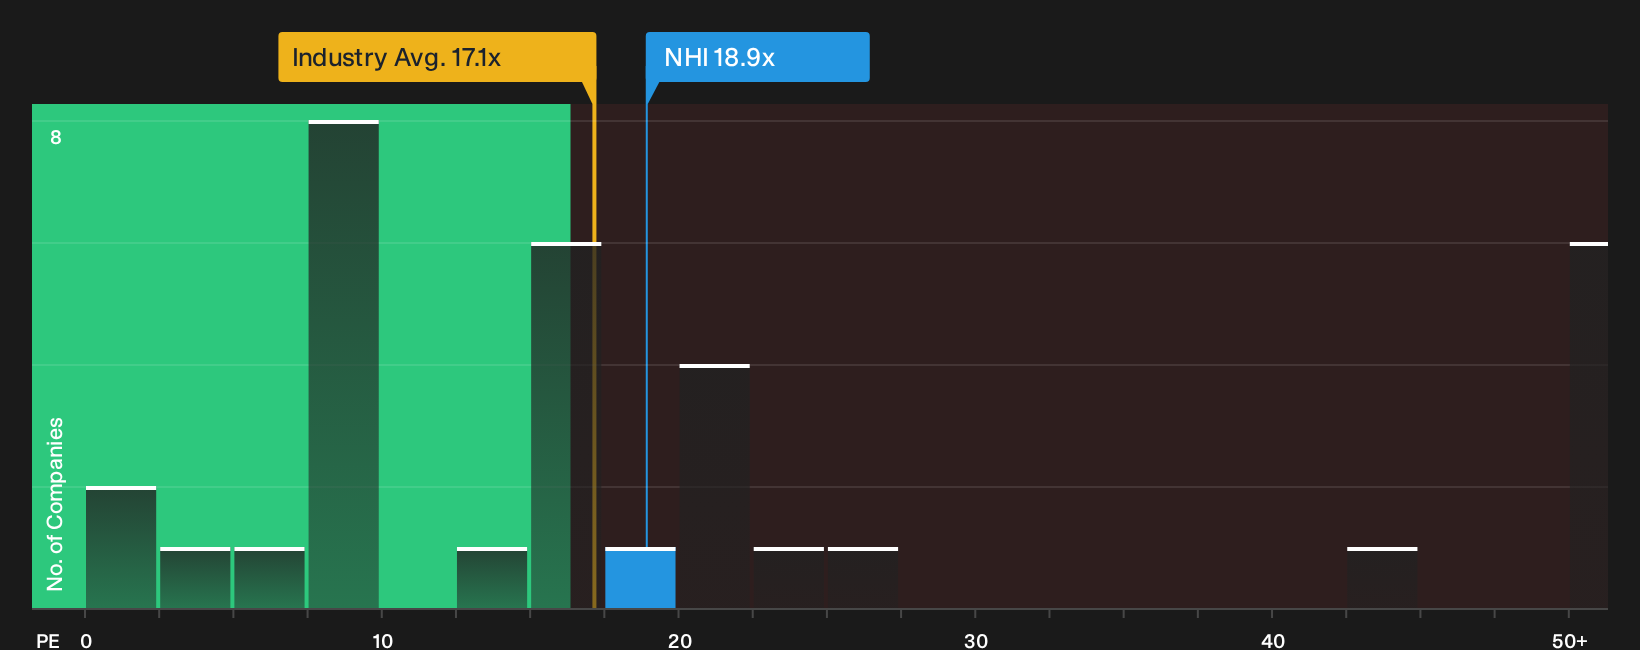
There is a sharp contrast between the fair value narrative on National Health Investors and what its current P/E suggests. The stock trades at 18.9x earnings, above the Global Health Care REITs industry on 17.1x, yet below a fair ratio of 29.3x that the market could move toward if sentiment shifts.
That combination points to a share price that screens more expensive than the sector average, but cheaper than what its own earnings profile might justify. This raises a simple question: Is this a margin of safety, or a signal that expectations on National Health Investors still need to cool?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment around National Health Investors is mixed, which is exactly why you should move quickly, look through the data yourself and decide how the balance of risks and rewards stacks up. To weigh both sides in one place, start with the 3 key rewards and 4 important warning signs.
Looking for more investment ideas beyond National Health Investors?
Do not stop your research with National Health Investors. The right watchlist often starts with a few strong ideas, then widens into fresh opportunities.
- Target potential mispricings by scanning a curated set of companies that screen as quality yet undervalued through the 29 high quality undervalued stocks.
- Strengthen your income focus by reviewing higher yielding candidates built to support sizeable payouts using the 8 dividend fortresses.
- Dial down portfolio risk by shortlisting sturdier balance sheets and steadier fundamentals with the 31 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com