
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Why Did iRhythm Holdings (IRTC) Shares Drop?
iRhythm Holdings (IRTC) has come under pressure recently, with the share price down about 15% over the past month and roughly 11% over the past 3 months. This has prompted investors to reassess expectations.
Zooming out, iRhythm Holdings has had a tough stretch recently, with the 7 day share price return down 7.63% and the year to date share price return down 40.08%. However, the 3 year total shareholder return of 25.17% and 5 year total shareholder return of 46.21% still show that investors who stayed in over longer periods have seen positive results overall.
Scan how iRhythm Holdings compares with other beaten down healthcare names by reviewing our hand picked 35 healthcare AI stocks that are also under pressure.
For iRhythm Holdings, a 40% year to date slide can either signal cracks in the business or just a sharp swing in sentiment. Which scenario do the current valuation markers point toward next?
Most Popular Narrative: 41% Undervalued
iRhythm Holdings last closed at $104.99, while the most followed narrative pegs fair value at about $178.93. This creates a wide gap that investors are trying to explain through growth, risk and discount rate assumptions rather than short term price swings.
The growing push towards population health management, preventative care, and value-based reimbursement is aligning directly with Zio's evidence-supported, scalable monitoring platform, supporting both recurring usage and improved payer coverage, which should drive higher revenues and improved net margins over time.
See why 4 investors see iRhythm Holdings as 41% undervalued.
Result: Fair Value of $178.93 (UNDERVALUED)
Still, the iRhythm Holdings narrative can be knocked off course if regulatory remediation drags on or if rising competition forces heavier spending and results in weaker margins.
Find out about the key risks to this iRhythm Holdings narrative.
Another View On iRhythm Holdings Valuation
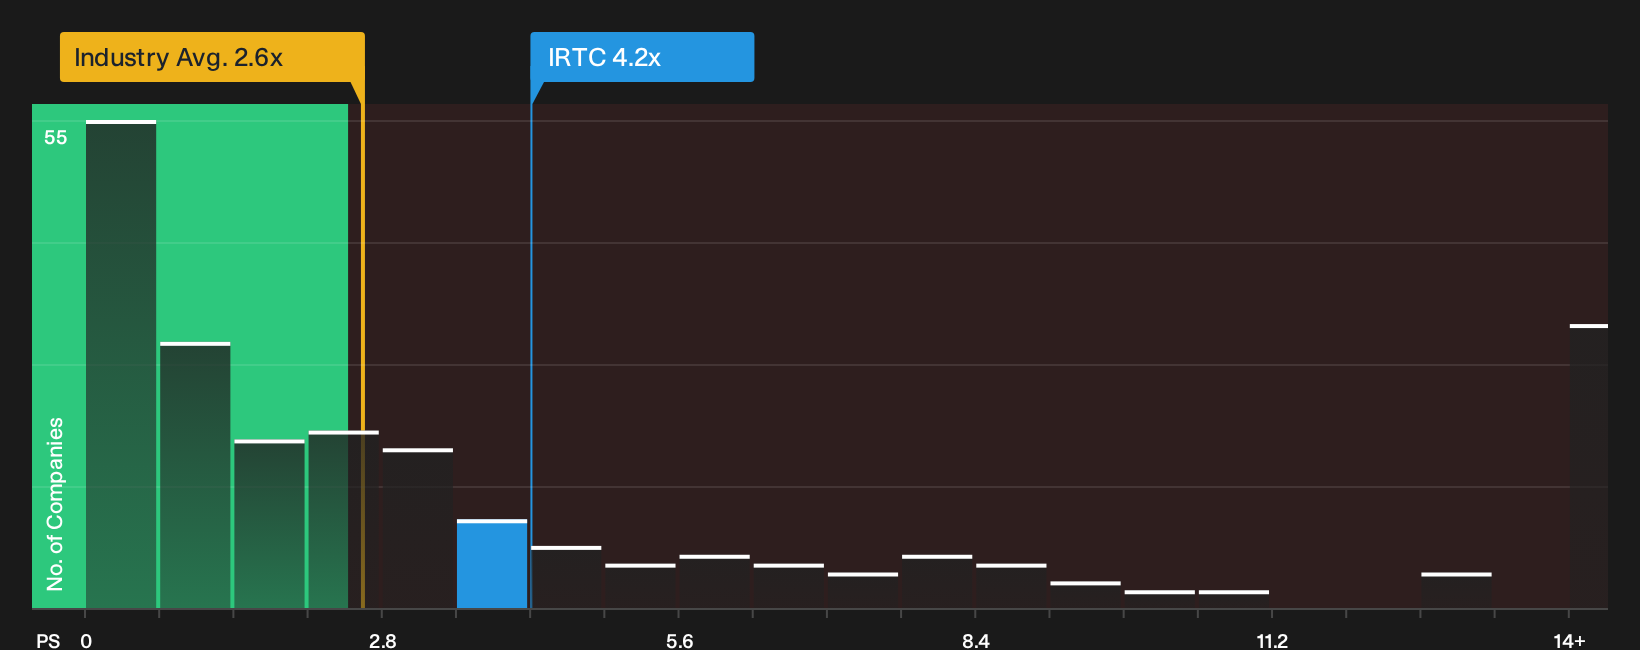
Analyst narratives and the SWS fair value model both point to iRhythm Holdings looking undervalued, yet the market is still charging a premium P/S ratio of 4.2x versus 2.6x for the wider US Medical Equipment group and 2.8x for peers. The fair ratio sits closer at 4.6x, which narrows the gap but still leaves you weighing whether this premium reflects quality or adds extra valuation risk.
To see how these revenue multiples stack up in more detail, including how they might compress or stretch if sentiment shifts, take a closer look at our valuation breakdown via See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Mixed messages on iRhythm Holdings so far, right? If you want to move quickly and form your own judgment, start with the full breakdown of 4 key rewards and 1 important warning sign
Looking for more iRhythm Holdings style investment ideas?
Staying focused on iRhythm Holdings is useful, but the real edge often comes from lining up a few strong alternatives using a disciplined screener.
- Target dependable potential with a focus on quality businesses by scanning our 29 high quality undervalued stocks that combine appealing pricing with stronger fundamentals.
- Prioritise resilience by reviewing a list of solid balance sheet and fundamentals (25 results) that can help you sidestep fragile stories and concentrate on sturdier opportunities.
- Hunt for fresher prospects with a 20 high quality undiscovered gems that many investors may not be watching yet but still meet clear financial filters.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com