
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Did Earnings Beat Just Shift UFP Technologies' (UFPT) Investment Narrative?
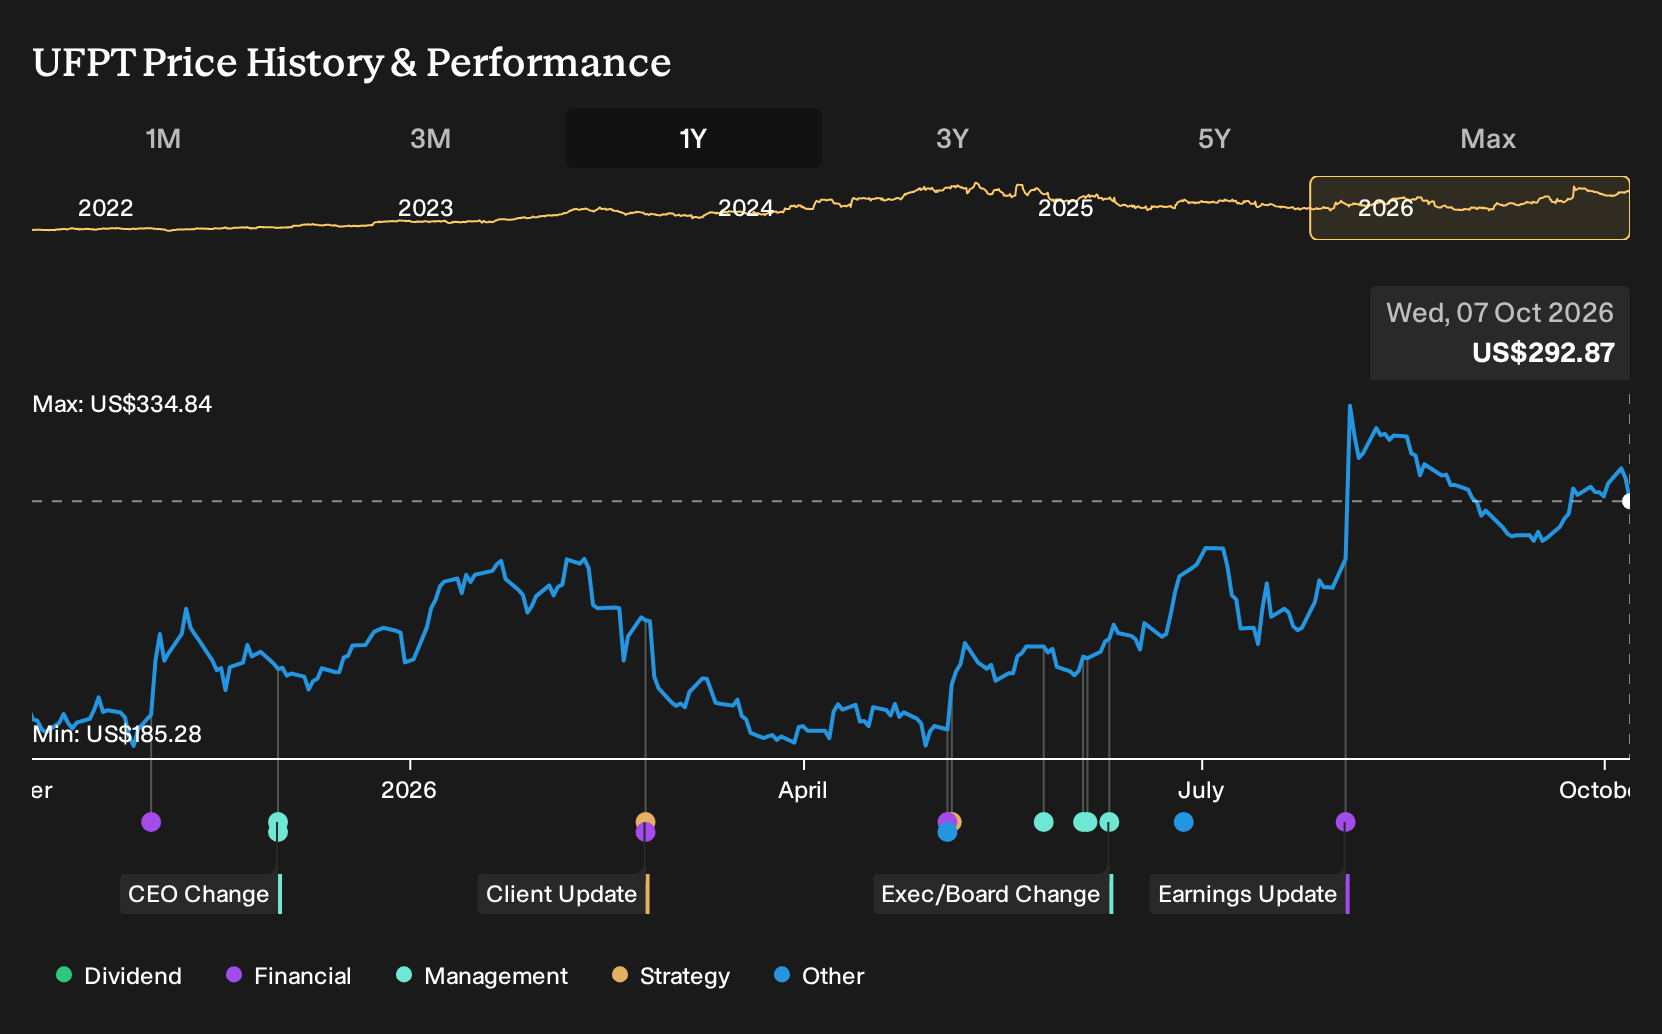
- UFP Technologies reported a strong Q2, with revenue of $174 million that was 15.1% higher year on year and 9.1% above analyst expectations, alongside an earnings beat that outpaced its peer group.
- The scale of the earnings surprise suggests UFP Technologies is executing well on demand for medical device components and packaging, at a time when outsourcing and biopharma investment are supporting activity across the drug development services sector.
- The focus now turns to how this sizeable Q2 earnings surprise from UFP Technologies could reshape the existing investment narrative.
Scan the drug development inputs space beyond UFP Technologies by checking which peers are also seeing strong demand trends in the 20 high quality undiscovered gems.
UFP Technologies Investment Narrative Recap
To own UFP Technologies, you need to be comfortable with a healthcare supplier that leans heavily on a few large device customers and is in the middle of meaningful operational shifts. The strong Q2 print reinforces that demand for its medical components and packaging is currently healthy, but it does not remove concentration risk or execution questions around facility transitions.
The key short term swing factor is how cleanly UFP Technologies can improve margins as labor issues at sites like AJR are worked through and new capacity, including offshore, ramps efficiently. The biggest near term risk remains operational disruption, whether from workforce turnover, retraining bottlenecks, or hiccups as production moves to lower cost regions.
The most relevant recent development for this Q2 beat is management’s ongoing push to expand manufacturing capacity and product development centers in the Dominican Republic alongside new programs for robotic assisted surgery customers. That effort helps explain why medical demand can translate into higher revenue, provided production quality and delivery times hold up.
For you as a shareholder, those moves create a clear execution test. Successful ramp up and stable output could support higher volume and better unit economics. Any material delays, quality issues, or cost overruns would go straight to margins and could strain relationships with major partners like Intuitive Surgical and Stryker, which already represent a concentrated customer base.
UFP Technologies’ current consensus narrative points to US$741.6 million of revenue and US$102.0 million of earnings by 2029. This outlook is built on analysts’ assumption of 5.5% yearly top line expansion and an earnings increase of about US$29.7 million from US$72.3 million today.
Uncover why UFP Technologies' fair value indicates a 21% potential upside to its current price, which could close faster than many investors expect.
Exploring Other Perspectives
One bullish twist on UFP Technologies focuses on acquisition firepower rather than margin repair. The most optimistic analysts were already assuming about US$785.0 million of revenue and US$111.2 million of earnings by 2029. That view is more upbeat than consensus and may shift again as you weigh this Q2 surprise against other scenarios.
Explore another UFP Technologies fair value estimate, including one that suggests as much as 21% upside from the current price.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your UFP Technologies research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for UFP Technologies. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate UFP Technologies' overall financial health at a glance.
Looking For More Ideas Beyond UFP Technologies?
If the Q2 story for UFP Technologies has sharpened your thinking, it can help to compare it against a wider field of potential opportunities using the Simply Wall St Screener.
- For investors focused on income resilience, review companies that screen as potential 8 dividend fortresses and see how their payouts line up with your risk tolerance.
- If capital preservation ranks high on your list, check out businesses identified as 31 resilient stocks with low risk scores and judge whether their profiles fit your preferred downside protection.
- When you want to broaden the watchlist with fresher ideas, scan the 20 high quality undiscovered gems and see which smaller players have fundamentals that meet your criteria.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com