
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Warner Music Group (WMG) Could Be 26% Undervalued Following Its International Expansion Push
Warner Music Group (WMG) is reshaping its international footprint after a series of leadership moves in the Middle East and North Africa and a fresh digital distribution deal in Europe. Both decisions give investors new context for the current share price.
Recent trading tells a mixed story. Warner Music Group’s share price is down 7.5% year to date and the 1-year total shareholder return has declined 11.5%, even though the stock has picked up slightly over the past week. This suggests investors are still weighing these international moves against longer term concerns about returns and risk.
Spot under-the-radar peers that are moving on similar international expansion stories by scanning our hand picked 20 high quality undiscovered gems in media and entertainment.Warner Music Group now trades well below both analyst targets and intrinsic value estimates. The real tension is whether the recent international push justifies a tighter gap or a deeper discount.
Most Popular Narrative: 26% Undervalued
Warner Music Group closed at $28.16, while the most followed narrative pegs fair value at $37.81. The gap centers on whether the business can translate its global reach and restructuring efforts into cash that matches those expectations.
Ongoing cost reduction initiatives such as the multi year restructuring and financial transformation programs are now backed by a 2025 plan that targets US$200 million of savings this year and US$300 million on an annualized basis by 2027. This supports the updated guidance for margin expansion at the high end of the 150 to 200 basis point fiscal 2026 target and is set to impact net margins and cash conversion.
See why 7 investors see Warner Music Group as 26% undervalued.
Result: Fair Value of $37.81 (UNDERVALUED)
Still, the Warner Music Group story could be knocked off course if legal disputes around AI licensing or questions over returns on past catalog and tech spending intensify.
Find out about the key risks to this Warner Music Group narrative.
Another View On Warner Music Group’s Valuation
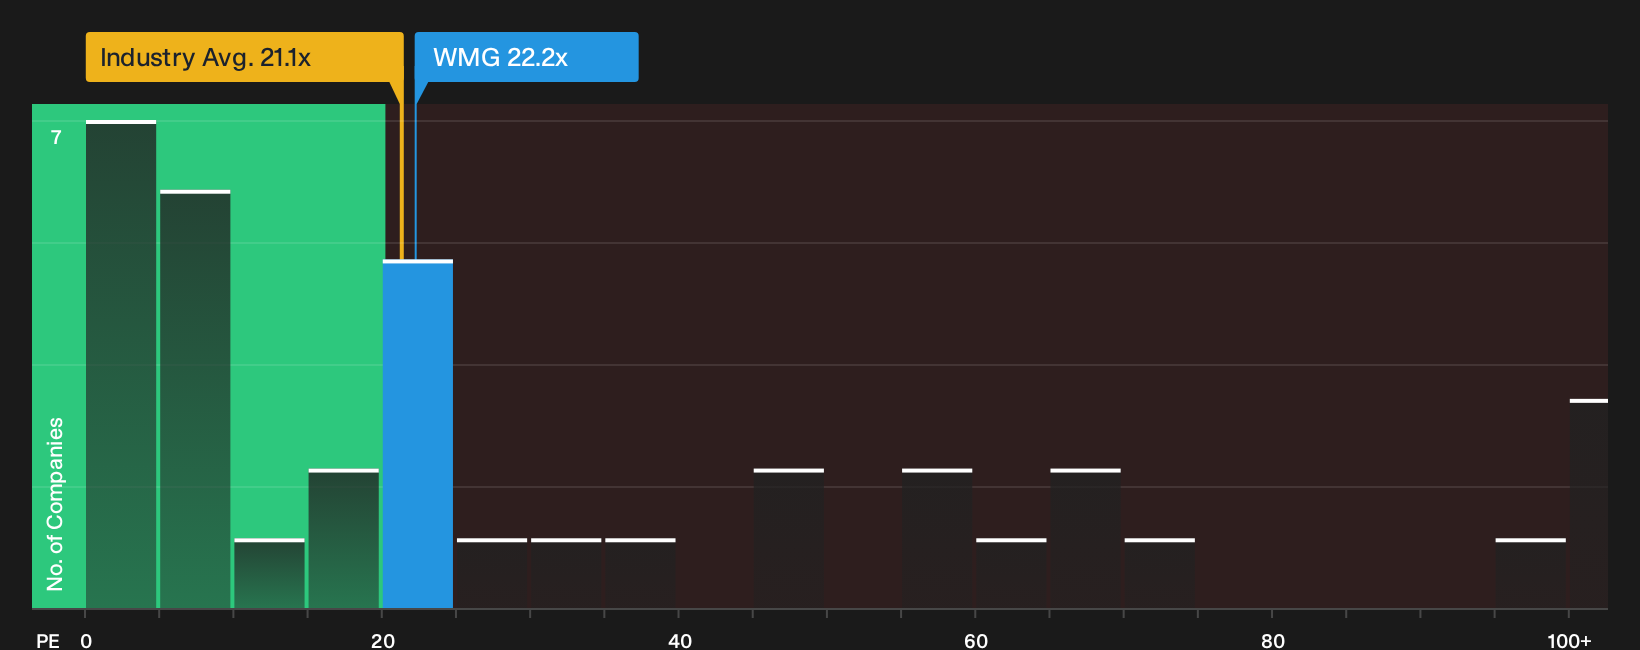
The earlier narrative leans on fair value estimates and analyst targets that frame Warner Music Group as 26% undervalued. A second lens tells a different story. On a simple P/E basis of 22.2x, the stock trades richer than the US Entertainment industry at 20.9x, but below a fair ratio of 24x and well under a 50.3x peer average. This points to some valuation risk if sector enthusiasm cools and some potential upside if sentiment moves closer to that fair ratio. Which reading do you think fits your own expectations for Warner Music Group over the next few years.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment on Warner Music Group is clearly split, so treat this as a prompt to move fast, review the facts yourself and decide where you stand on the stock’s risk and reward balance. To weigh both sides in one place, start with the 4 key rewards and 3 important warning signs.
Looking for more investment ideas beyond Warner Music Group?
Do not stop with Warner Music Group. Broaden your watchlist with a few targeted screens that highlight different ways to balance return potential and risk.
- Target potential mispricing by scanning a curated set of companies that appear attractively valued on quality and fundamentals using the 29 high quality undervalued stocks.
- Build a steadier income stream by focusing on payout strength and resilience through our hand picked 8 dividend fortresses.
- Dial down portfolio stress by reviewing a 31 resilient stocks with low risk scores that filters for resilience, financial strength and lower downside indicators.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com