
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Bank Of Communications (SEHK:3328) Could Be 47% Below Fair Value On Bond Redemption
Bank of Communications (SEHK:3328) has fully redeemed its RMB 30b 10-year Tier 2 capital bonds at par, exercising its issuer call option on the fifth interest reset date in the China interbank market.
At a share price of HK$8.205, Bank of Communications has given investors a 4.12% 1 month share price return and a 21.20% 3 month share price gain, while the 1 year total shareholder return of 35.30% and 5 year total shareholder return of 149.14% point to momentum that has been building over time as recent capital actions, such as the Tier 2 bond redemption, feed into how the market is reassessing both growth potential and perceived risk.
See how Bank of Communications compares with other lenders adjusting their funding mix by reviewing our hand picked 225 resilient stocks with low risk scores universe.
Bulls see Bank of Communications retiring pricey Tier 2 capital as a cleaner balance sheet and stronger earnings power. Bears argue the recent share price surge already reflects that. Which side do the current valuation markers support?
Price-to-Earnings of 6.8x: Is it justified?
On simple numbers, Bank of Communications trades on a P/E of 6.8x, which lines up with a share price of HK$8.205. The market is treating this as richer than many Hong Kong bank peers but still below some broader peer averages.
The P/E ratio compares what investors pay for each unit of current earnings. For Bank of Communications, a 6.8x multiple means the stock price is a little under seven times its annual profit per share. For large lenders this metric often becomes a shorthand for how investors view the reliability of earnings and the long term return on equity profile rather than a quick growth story.
Bank of Communications shows a 7.6% return on equity and high quality earnings, with profits forecast to grow 5.02% per year and revenue expected to expand 9.7% per year. Against that backdrop, a 6.8x P/E sits above the Hong Kong Banks industry average of 5.1x but below the peer group average of 8.2x. This points to the market assigning a premium to its earnings compared to local banks in general while still pricing the stock below a level the fair P/E of 7.1x suggests the valuation could move towards if current trends hold.
Explore the SWS fair ratio for Bank of Communications.
Result: Price-to-Earnings of 6.8x (ABOUT RIGHT)
Still, the recent rally in Bank of Communications could stall if earnings momentum softens or if funding costs shift in ways the market does not expect.
Find out about the key risks to this Bank of Communications narrative.
Another View on Bank of Communications Valuation
The P/E story leans toward fair. The SWS DCF model tells a different story. At around HK$8.21, Bank of Communications is trading roughly 47% below an estimated cash flow value of HK$15.44. That points to a large gap between earnings based pricing and long term cash expectations. Which signal do you trust more?
Look into how the SWS DCF model arrives at its fair value.
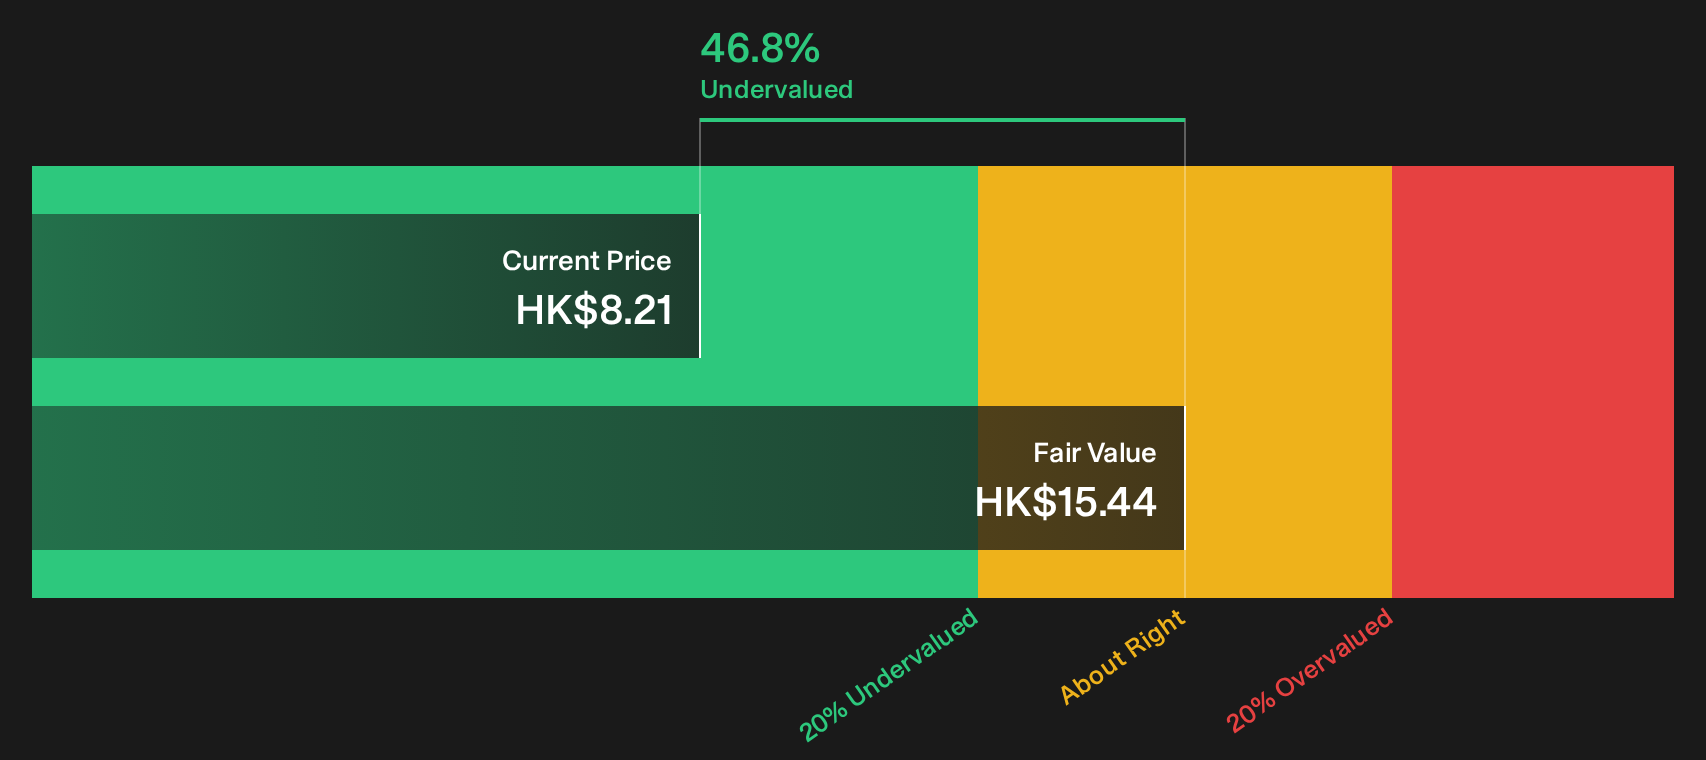
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Bank of Communications for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 184 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed messages on Bank of Communications valuation and risk reward can feel messy, so move quickly, dig into the full picture, and weigh the 3 key rewards and 1 important warning sign.
Looking for more ideas beyond Bank of Communications?
Do not stop with Bank of Communications. Put these valuation clues to work, broaden your watchlist, and give yourself more options before the next move hits.
- Target resilient balance sheets by scanning our list of solid balance sheet and fundamentals (207 results) that spotlight companies combining prudent leverage with dependable fundamentals.
- Spot potential value gaps early through the 184 high quality undervalued stocks and see which stocks trade at prices that look modest next to their fundamentals.
- Prioritise income strength by reviewing the 224 dividend fortresses and focus on businesses offering higher yields with an emphasis on durability.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com