
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Is uniQure (QURE) Undervalued On New Huntingtons Data And FDA Filing Clarity?
Why uniQure Stock Is Back in Focus
uniQure (NasdaqGS:QURE) is back on investors’ radar after fresh Phase I/II data on its Huntington’s disease gene therapy candidate showed continued slowing of disease progression at both 36 and 48 months.
At a share price of US$23.14, uniQure has seen the 30 day share price return fall 48% and the 1 year total shareholder return decline 61.41%, even though the 3 year total shareholder return is up more than 3x. This suggests recent momentum has faded despite longer term holders still being ahead overall.
Seize this pullback in uniQure as a chance to review other clinically active biotech contenders in our curated 20 high quality undiscovered gems that could be flying under most investors’ radar.uniQure’s sharp pullback after the Huntington’s data release has flipped the debate. Is most of the re‑rating already in the rear-view mirror? Or does the current valuation still leave meaningful upside on the table?
Most Popular Narrative: 63% Undervalued
On Simply Wall St’s most followed narrative, uniQure’s fair value sits at about $62.42 against a last close of $23.14. This places a lot of weight on what AMT-130 can deliver and how regulators respond.
The potential accelerated approval for AMT-130 in treating Huntington's disease could significantly boost future revenues as it would be one of the first disease-modifying treatments available for this condition.
Expansion of the clinical pipeline with new studies in refractory temporal lobe epilepsy, Fabry disease, and SOD1-ALS could lead to additional revenue streams if these treatments are successful and commercialized.
See why 11 investors see uniQure as 63% undervalued.
Result: Fair Value of $62.42 (UNDERVALUED)
Still, if AMT-130 stumbles in FDA review or if manufacturing outsourcing creates supply snags, the uniQure narrative could look very different, very quickly.
Find out about the key risks to this uniQure narrative.
Another View on uniQure’s Valuation
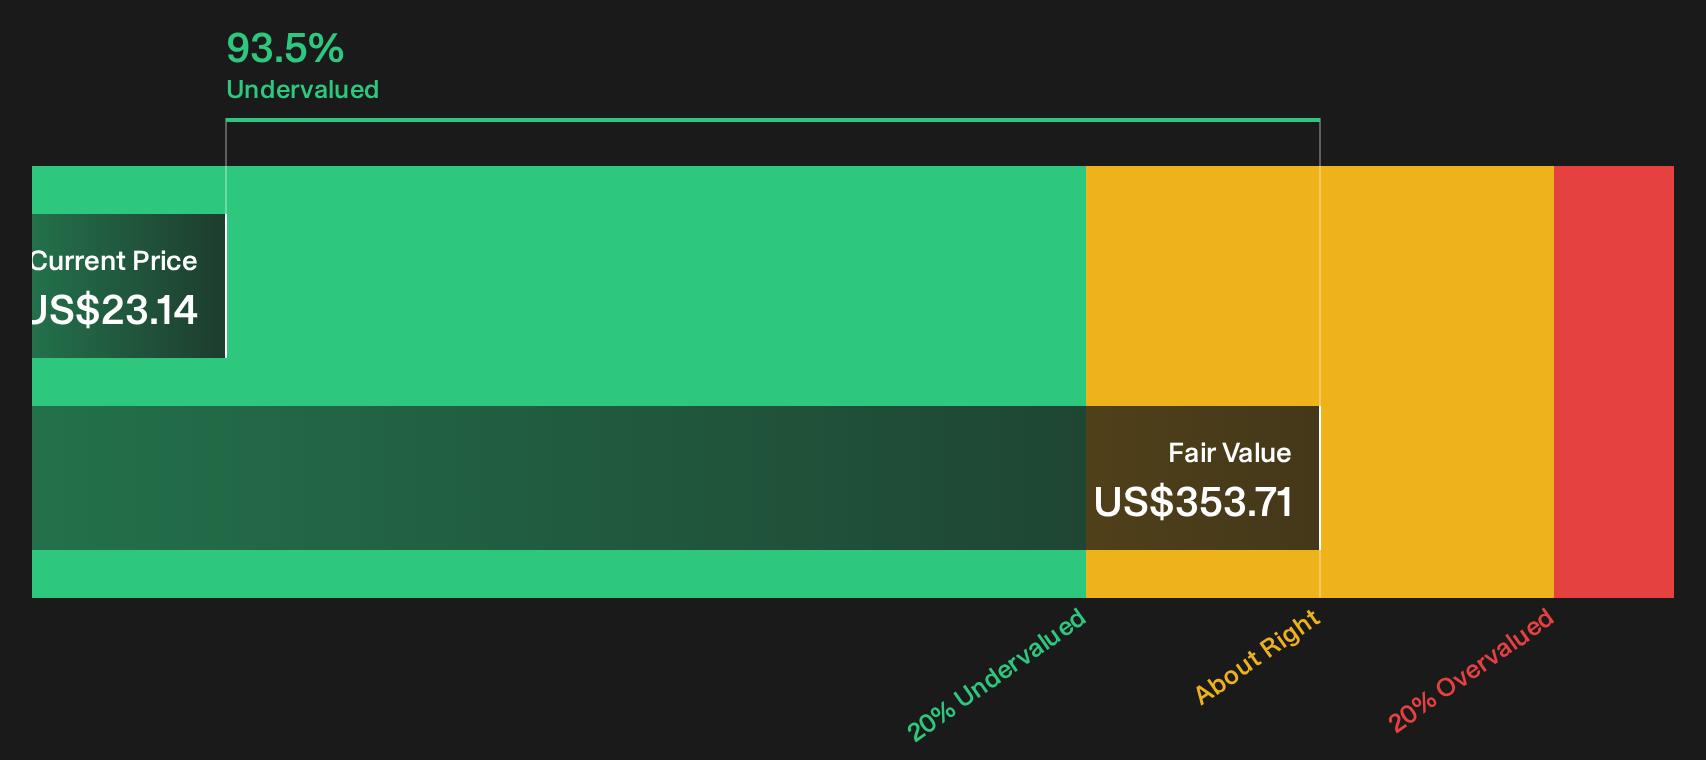
Analysts lean heavily on future earnings targets, yet Simply Wall St’s DCF model paints a very different picture. On that framework, uniQure at US$23.14 screens as deeply undervalued against an indicated future cash flow value of US$353.71. Which lens do you trust more when real cash generation is the focus?
Look into how the SWS DCF model arrives at its fair value.
Next Steps
Mixed signals around uniQure can create hesitation, so move quickly to review the underlying data, weigh the concerns alongside the potential, and focus on the 2 key rewards and 1 important warning sign.
Looking for more investment ideas beyond uniQure?
If uniQure has sharpened your focus, treat this moment as your prompt to scan wider, compare opportunities, and pressure test your next move before the crowd does.
- Target potential mispricings by lining up quality fundamentals against current valuations using our focused 29 high quality undervalued stocks.
- Build a steadier core for your portfolio by filtering companies with healthier finances through the list of solid balance sheet and fundamentals (25 results).
- Hunt for lesser known opportunities that still show strong underlying metrics with the curated 20 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com