
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Kyoritsu Maintenance (TSE:9616) Could Be Fully Valued On Stronger August Sales
Kyoritsu Maintenance (TSE:9616) released preliminary sales data for August 2026, reporting monthly sales of ¥25,557 million and year-to-date sales of ¥116,222 million, both above the figures for the prior year.
At a share price of ¥3,226, Kyoritsu Maintenance has logged a 9.77% 90 day share price return and a 12.13% year to date share price return. The 5 year total shareholder return of 61.71% points to momentum that has been building over a longer horizon, with the latest stronger preliminary sales likely reinforcing that trend in investors’ minds.
Scan Kyoritsu Maintenance alongside a hand picked 15 high quality undervalued stocks that also show rising sales momentum and recent share price strength.
The recent move in Kyoritsu Maintenance on the back of stronger preliminary sales leaves investors weighing one thing: Is most of the upside already priced in, or is there still meaningful value on the table?
Preferred P/E Multiple of 16.2x: Is It Justified?
Kyoritsu Maintenance is being valued on a P/E of 16.2x at the last close of ¥3,226. This points to a market assessment that is slightly conservative compared to both peers and an estimated fair level.
The P/E ratio measures how much investors are paying for each ¥1 of current earnings. For a group like Kyoritsu Maintenance that runs dormitories, hotels and related services, earnings power matters because cash flows are linked to occupancy, room rates and operating efficiency rather than one off asset sales.
Viewed against peers, this earnings multiple looks restrained. The stock trades below the JP Hospitality industry average P/E of 22x and also below the estimated fair P/E of 22.2x that our fair ratio framework suggests the market could gravitate toward if sentiment and fundamentals stay aligned.
Explore the SWS fair ratio for Kyoritsu Maintenance.
Result: Price-to-Earnings of 16.2x (UNDERVALUED).
Still, Kyoritsu Maintenance remains exposed to shifts in travel demand and any slowdown in student or corporate dormitory contracts that could reduce earnings expectations.
Find out about the key risks to this Kyoritsu Maintenance narrative.
Another View On Kyoritsu Maintenance’s Value
The P/E points to Kyoritsu Maintenance looking inexpensive, yet the SWS DCF model paints a very different picture. On that framework, the estimated future cash flow value sits at ¥728.65 per share, well below the current ¥3,226 level, which implies the stock screens as overvalued on this method. Which lens do you trust more for your own process?
Look into how the SWS DCF model arrives at its fair value.
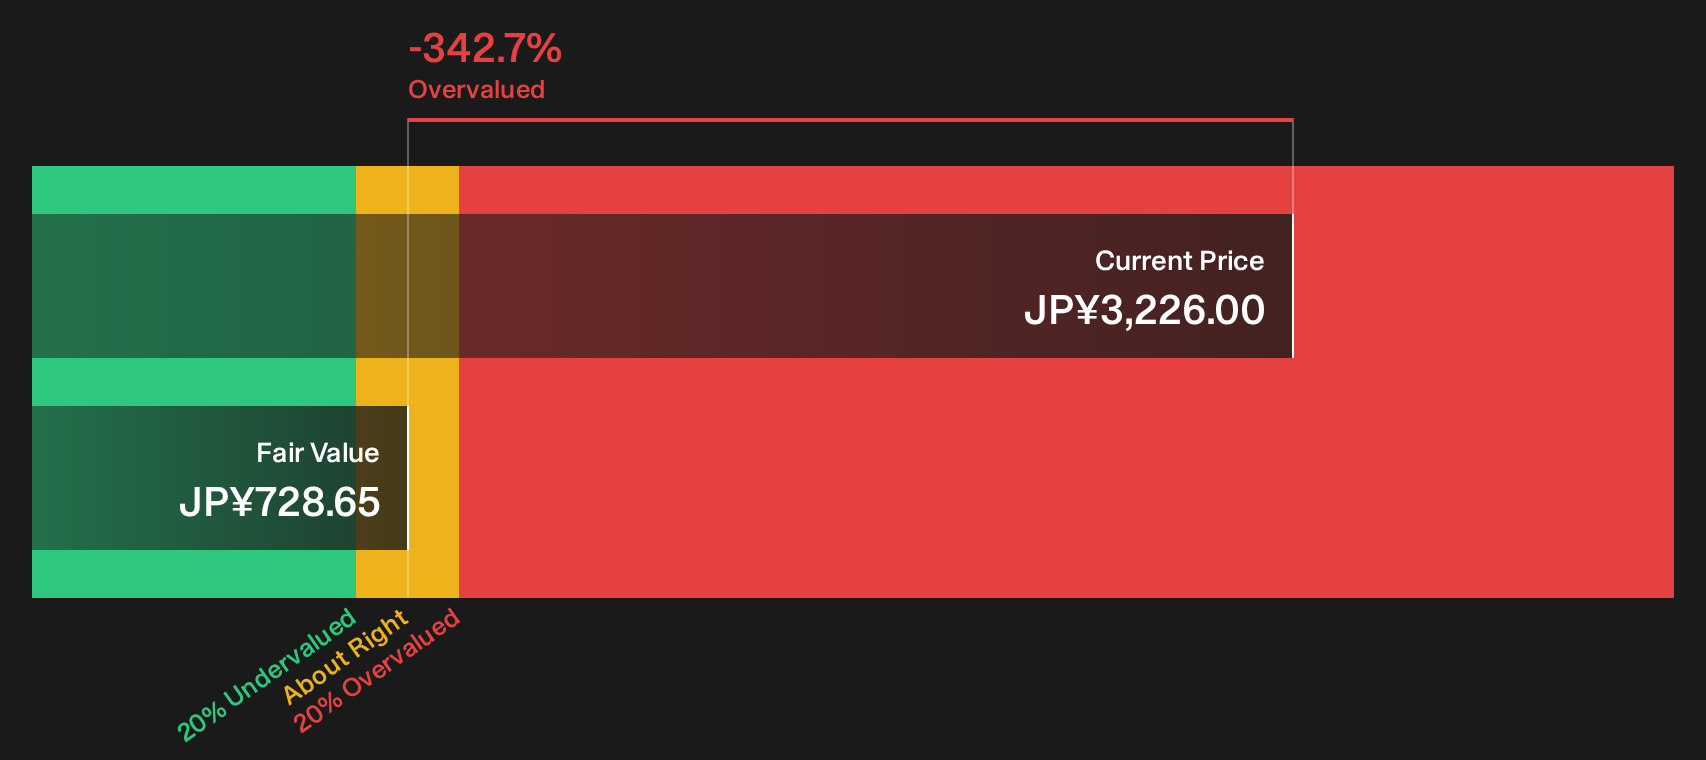
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Kyoritsu Maintenance for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 15 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Keen to test whether the mixed signals around Kyoritsu Maintenance truly add up for you personally? Move quickly, examine both the upside and the downside in detail, then ground your view in the 4 key rewards and 2 important warning signs
Looking for more ideas beyond Kyoritsu Maintenance?
If you want to turn this analysis into action, broaden your watchlist with a few focused stock ideas sourced directly from the Simply Wall St Screener.
- Target stability in choppy markets by reviewing a 22 resilient stocks with low risk scores that focuses on resilience and quality over short term hype.
- Hunt for potential mispricings by scanning a 75 high quality undiscovered gems that pairs strong fundamentals with relatively low market attention.
- Prioritise financial strength by working through a list of solid balance sheet and fundamentals (23 results) that highlights companies with sturdier capital structures and healthier fundamentals.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com