
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
International Petroleum (TSX:IPCO) Completed Its Buyback, Is It Still A Bargain?
International Petroleum (TSX:IPCO) has completed a share repurchase tranche, buying 1,197,483 shares for CA$39.65 million between July and early October, equal to 1.06% of its outstanding equity.
Recent trading has been firm, with International Petroleum’s share price up 13.55% over the past 90 days and recording a 37.01% year to date share price return. Total shareholder return has reached 44.45% over one year and 381.63% over five years, suggesting investors have been rewarding the buyback driven capital return story.
Scan other energy plays that use disciplined capital returns as a potential catalyst by reviewing the hand picked 7 high quality undervalued stocks alongside International Petroleum's latest buyback move.
International Petroleum has been retiring shares while the stock has been climbing, which raises a simple tension. Are investors paying up for sentiment, or for the cash flows that are shrinking the equity base?
Most Popular Narrative: 13% Undervalued
International Petroleum's most followed valuation storyline puts fair value at CA$40.11, above the recent CA$34.87 close, which keeps attention on how future projects and cash generation might support that gap.
The imminent completion and ramp-up of Blackrod Phase 1 is expected to significantly increase long-life, low-cost production, materially improving operating cash flow and free cash flow from late 2026 onwards. This is expected to support future revenue and earnings growth. Tightening differentials between WTI and WCS (supported by structural pipeline expansions like TMX) are expected to persist, bolstering realized prices for Canadian crude and increasing netback per barrel, directly benefiting net margins.
See why 9 investors see International Petroleum as 13% undervalued.
Result: Fair Value of CA$40.11 (UNDERVALUED)
Still, the International Petroleum story can be knocked off course if Blackrod Phase 1 underdelivers or if climate and regulatory pressures raise long term costs.
Find out about the key risks to this International Petroleum narrative.
Another View on International Petroleum's Valuation
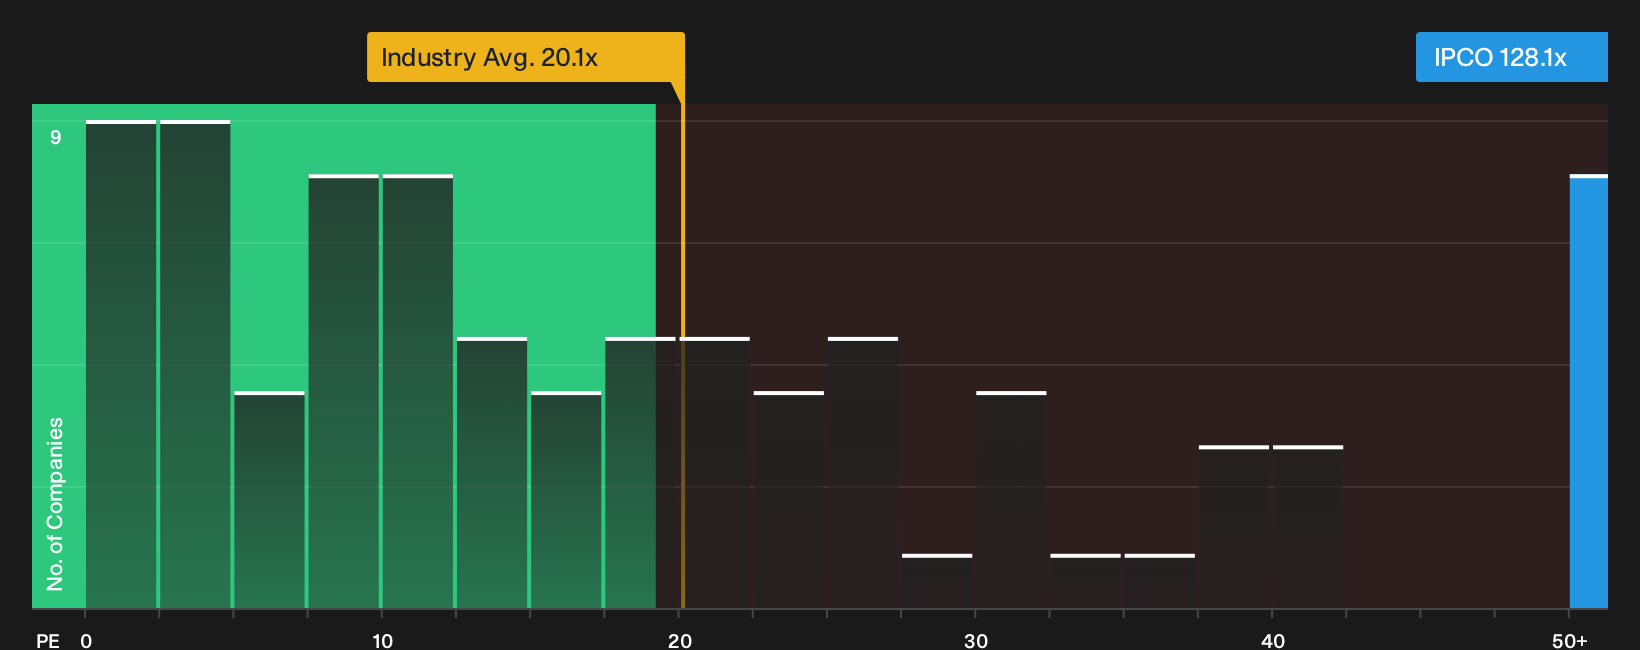
On simple earnings multiples, International Petroleum looks expensive. The stock trades on a P/E of 128.1x, compared with about 20.2x for the Canadian Oil and Gas sector, a peer average of 20.6x, and a fair ratio of 24x that the market could move towards over time.
If that gap closes toward either the industry or the fair ratio, the adjustment would fall on the share price rather than on reported earnings, which is the sort of valuation risk investors usually feel most directly.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on International Petroleum's valuation story. If you want to move fast and judge the risk and reward balance for yourself, start with the 2 key rewards and 2 important warning signs.
Looking for more International Petroleum style investment ideas?
If International Petroleum has sharpened your focus on valuation and capital returns, use the Simply Wall St screener to widen your opportunity set with data driven ideas.
- Target potential mispricings by lining up quality fundamentals against value indicators using the 7 high quality undervalued stocks.
- Lock in potential income ideas by scanning companies with robust payouts through the 2 dividend fortresses.
- Prioritise resilience by filtering for companies with stronger finances using the list of solid balance sheet and fundamentals (7 results).
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com