
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Learn Why The Bull Case For Avient Stock Could Change Following Dividend Increase
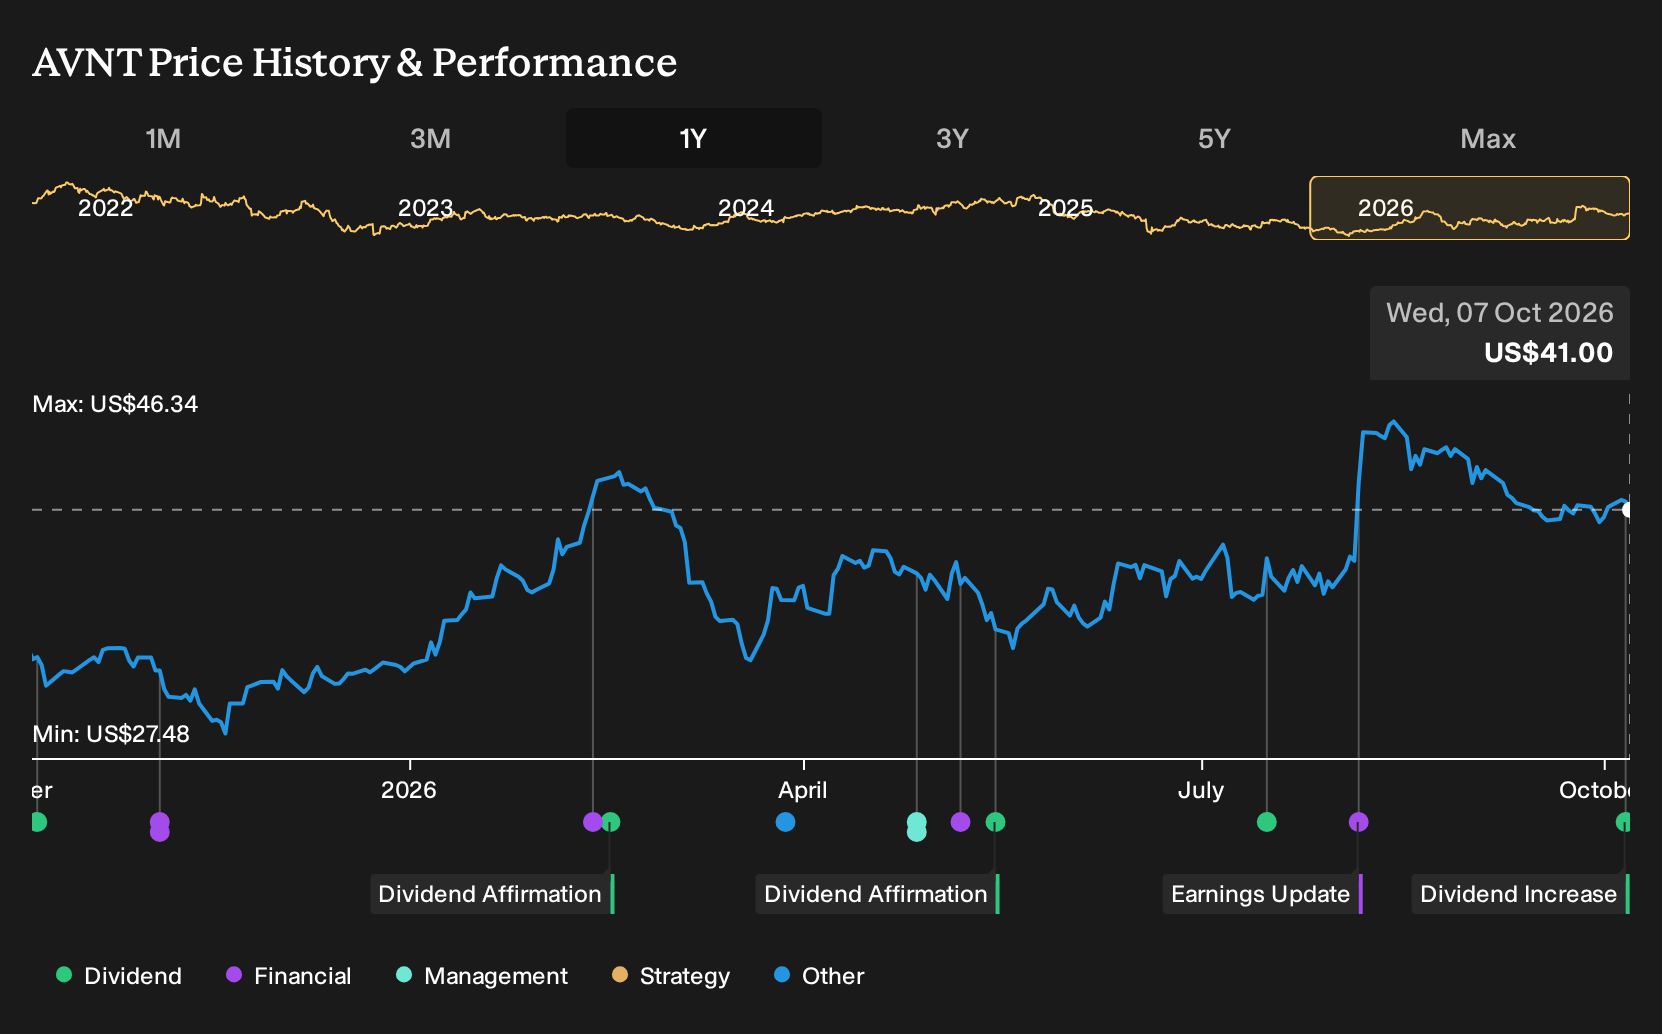
- Avient has declared a quarterly cash dividend of $0.2825 per share on common stock, to be paid on January 7, 2027. This lifts the annualized payout from $1.10 to $1.13 and extends its run of consecutive annual dividend increases to sixteen years.
- The sixteenth straight annual dividend raise indicates that Avient's board currently views the business as generating sufficient cash to support regular shareholder distributions, while also continuing its capital allocation program.
- In the following sections, we consider how Avient's investment narrative is influenced by this sixteenth consecutive annual dividend increase and what it may signal for shareholders.
Scan how Avient's sixteenth straight dividend increase compares with other income ideas by running through our hand picked 8 dividend fortresses before you decide where your next dollar goes.
Avient Investment Narrative Recap
To own Avient, you need to believe the shift toward higher value materials in electronics, healthcare and non PFAS packaging can keep lifting mix quality and profitability over time. The sixteenth straight dividend increase supports that narrative, although by itself it does not change the near term story. That story hinges on execution in these focus areas.
For now, the key short term catalyst is whether demand in electronics, data center infrastructure and non PFAS packaging continues to offset softer transportation and other industrial markets. The biggest risk remains that cyclical end markets stay weak, which would limit operating leverage and keep returns on equity and cash coverage of debt under pressure.
The latest quarterly dividend of US$0.2825 per share is the most relevant signal for this catalyst setup. Avient is committing more cash to payouts at a time when it is also targeting debt reduction, margin improvement in EMEA and growth in electronics and packaging. Income investors may read that as confidence in cash generation capacity.
That confidence sits alongside real execution tasks. Management still needs to grow earnings from US$170.0m, improve the currently low 7% return on equity and keep funding higher margin projects while servicing borrowings that are not yet well covered by operating cash flow. Dividend growth, in that context, increases the importance of consistent free cash flow delivery.
What Avient's Dividend Move Sits On Top Of
Avient's narrative projects US$3.7b revenue and US$338.5m earnings by 2029. That path assumes revenue grows by 3.9% a year and earnings roughly double from US$170.0m today, an increase of about US$168.5m.
Uncover how Avient's fair value indicates a 24% potential upside to its current price before the gap between price and value tightens.
Exploring Other Perspectives
You also have a very different story on the cautious end. The lowest analysts focus on how weakness in packaging and consumer demand could cap progress, even while Avient lifts its dividend again. They were pencilling in US$3.7b of revenue and about US$314.9m of earnings by 2029, and see that as a modest outcome. Those views were all formed before this dividend news, so use them as starting points and then consider how your own expectations might shift from here.
Reach Your Own Conclusion
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Avient research is our analysis highlighting 5 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Avient. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Avient's overall financial health at a glance.
Looking For More Ideas Beyond Avient?
If Avient has sharpened your focus on income, quality and risk, it can help to line it up against other opportunities using structured filters rather than hunches.
- For investors who want potential bargains with supporting fundamentals, check out a curated set of companies through the 29 high quality undervalued stocks to see which ones line up with your return and risk goals.
- If capital preservation matters just as much as upside, scan the 31 resilient stocks with low risk scores to focus on businesses that currently screen with more resilient profiles.
- When you are hunting for fresh ideas beyond the usual watchlists, let the 20 high quality undiscovered gems surface lesser known stocks that still carry strong underlying metrics.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com