
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Amazon (AMZN) Stock Still Looks Discounted On Cash Flow
Amazon.com has seen its stock power higher in recent years, and the question for investors now is whether the current share price is properly anchored to the cash the business can generate over time. With enthusiasm around artificial intelligence, logistics and cloud computing shaping expectations, the focus turns to what the underlying cash flows actually justify for Amazon.com today.
- Over the past 3 years, Amazon.com has delivered a 97.2% share price gain, which puts a lot of weight on whether its future cash generation can support that kind of market value.
- The recent multi year deal between Amazon Web Services and Synopsys to support custom chip design points to heavy, ongoing investment that can influence future cash flow timing, capital intensity and the value investors place on those streams.
- What if you looked at Amazon.com through its earnings instead? See what Amazon.com's 20.7x P/E says about the price.
The issue now is whether the cash flows implied by Amazon.com's current price of US$259.92 line up with what the Discounted Cash Flow (DCF) intrinsic value estimate suggests.
Investors weighing Amazon.com against the wider AI and cloud build out may find it useful to compare its cash flow story with other 92 AI infrastructure stocks.
Is Amazon.com a Bargain on Cash Flow?
The Discounted Cash Flow (DCF) model here looks at the cash Amazon.com can return to shareholders over time and then works back to what that is worth today. On this view, the latest twelve month Free Cash Flow sits at about $32.6b, and the projections use a growing cash generation profile rather than assuming a flat or shrinking business.
Those estimates factor in a dip to negative free cash flow in 2027 before a sharp recovery, with projected annual cash flows reaching into the hundreds of billions of $ by the early 2030s. That path reflects heavy spending needs, including cloud and AI infrastructure, but assumes the outlay eventually produces much larger cash surpluses. The Discounted Cash Flow (DCF) projections put Amazon.com's estimated intrinsic value substantially above the current share price of US$259.92. Because the recent AI borrowing surge across major tech groups raises questions about how much of that future cash will be absorbed by interest and data center spending, the model gap is worth treating as a scenario to test rather than a conclusion. Find out what Amazon.com could be worth using our Discounted Cash Flow (DCF) estimate.
The Amazon.com Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where Amazon.com's DCF puzzle leaves off by spelling out which paths for growth, profitability and earnings would need to play out for the stock to be worth meaningfully more or less than today's price. Each narrative ties a fair value estimate to a particular mix of potential catalysts and risks for Amazon.com, so you can track over time which version of the story the business appears to be moving toward on the Community page.
Community views on Amazon.com split between investors who see an AI driven margin reset playing out and others who think the current price already assumes too much.
Bull case: 42% undervalued
"Amazon is sacrificing short-term margins to secure long-duration dominance in AI infrastructure, advertising, and automated commerce..."
Discover why this Narrative puts Amazon.com at 42% undervalued.
Bear case: 55% overvalued
"From these simulations we can extrapolate that there''s more than 90% probability of Amazon being overvalued..."
Explore why this Narrative puts Amazon.com at 55% overvalued.
For Amazon.com, the share price is only one piece of the story
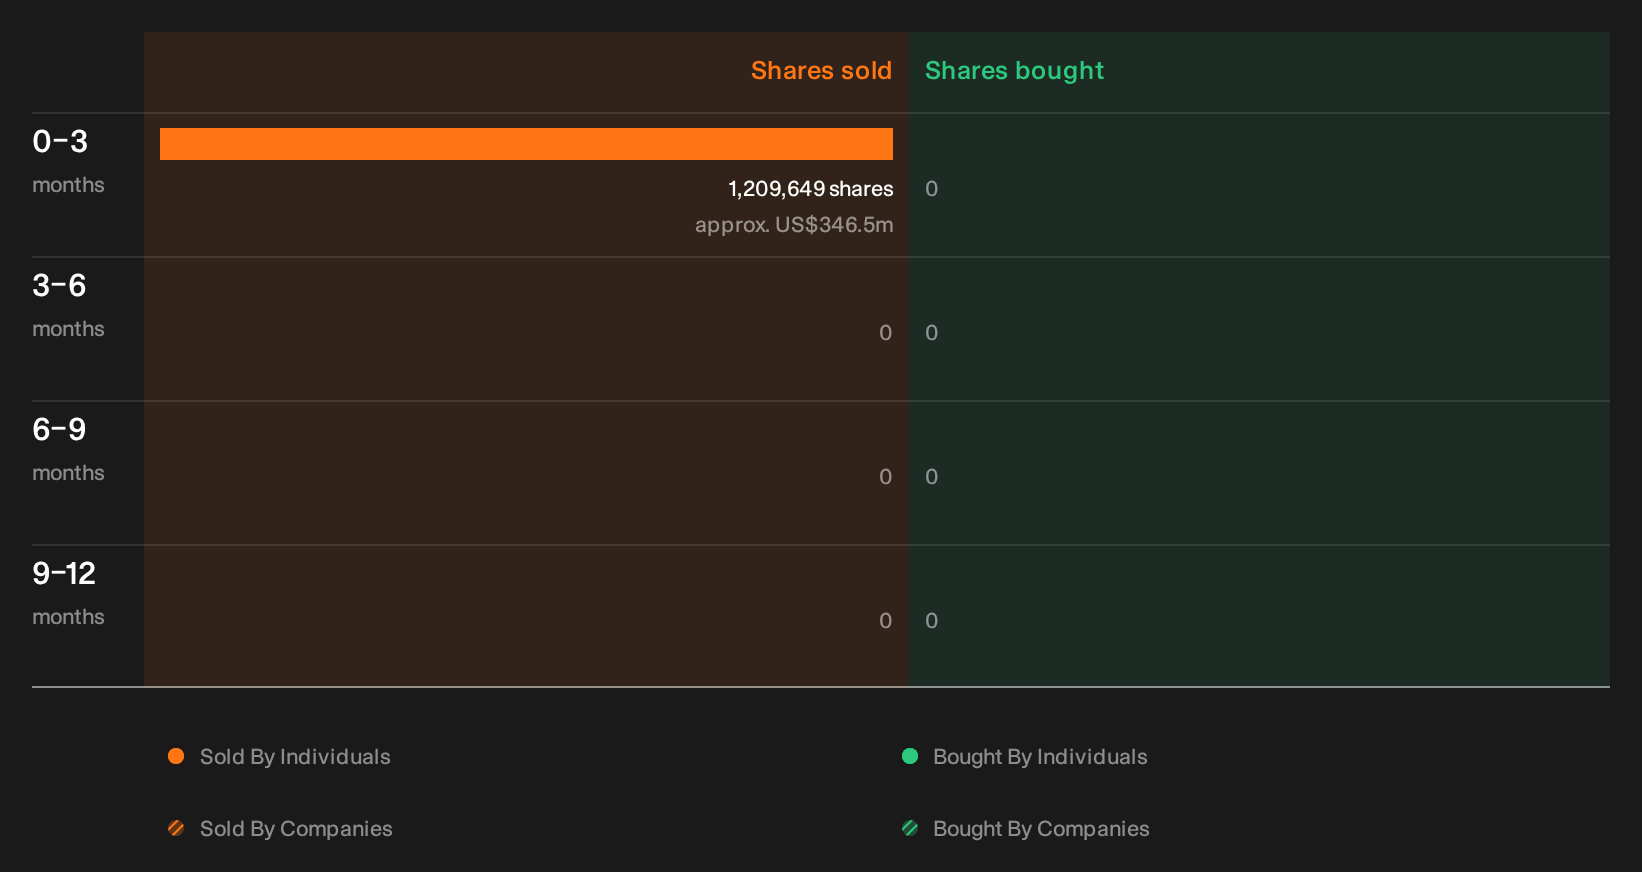
One factor that does not show up in a DCF output is what Amazon.com insiders are doing with their own holdings, and recent selling activity has been flagged for you to review in detail. See the recent insider selling flagged for Amazon.com.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com