
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Asian Growth Companies With High Insider Ownership In October 2026
As of October 2026, Asian markets are navigating a complex landscape marked by fluctuating global economic indicators and regional policy shifts. Amidst these dynamics, investors are increasingly focused on growth companies with high insider ownership, as such stocks often signal strong management confidence and alignment with shareholder interests.
Top 10 Growth Companies With High Insider Ownership In Asia
| Name | Insider Ownership | Earnings Growth |
| Suzhou Dongshan Precision Manufacturing (SZSE:002384) | 33.5% | 74.9% |
| Shanghai Skychem Technology (SHSE:688603) | 31.8% | 67.7% |
| Shanghai Biren Technology (SEHK:6082) | 10.4% | 119.7% |
| Seojin SystemLtd (KOSDAQ:A178320) | 18% | 106.6% |
| SEERS (KOSDAQ:A458870) | 33.8% | 37.8% |
| JHT DesignLtd (SHSE:603061) | 23.1% | 48.6% |
| Guangdong Shenling Environmental Systems (SZSE:301018) | 36.7% | 65.4% |
| Great Microwave Technology (SHSE:688270) | 21.1% | 95.2% |
| Gpixel Changchun Microelectronics (SEHK:3277) | 18.2% | 32% |
| Fulin Precision (SZSE:300432) | 10.8% | 66.5% |
Let's uncover some gems from our specialized screener.
IntelliEPI (Cayman) (TPEX:4971)
Simply Wall St Growth Rating: ★★★★★☆
Overview: IntelliEPI Inc. (Cayman) manufactures and sells epitaxy wafers of compound semiconductors for applications in wireless communications, data transmission, and national defense across various international markets, with a market cap of NT$28.50 billion.
Operations: The company generates revenue of NT$1.16 billion from its semiconductor segment, which involves the production and sale of epitaxy wafers for various applications.
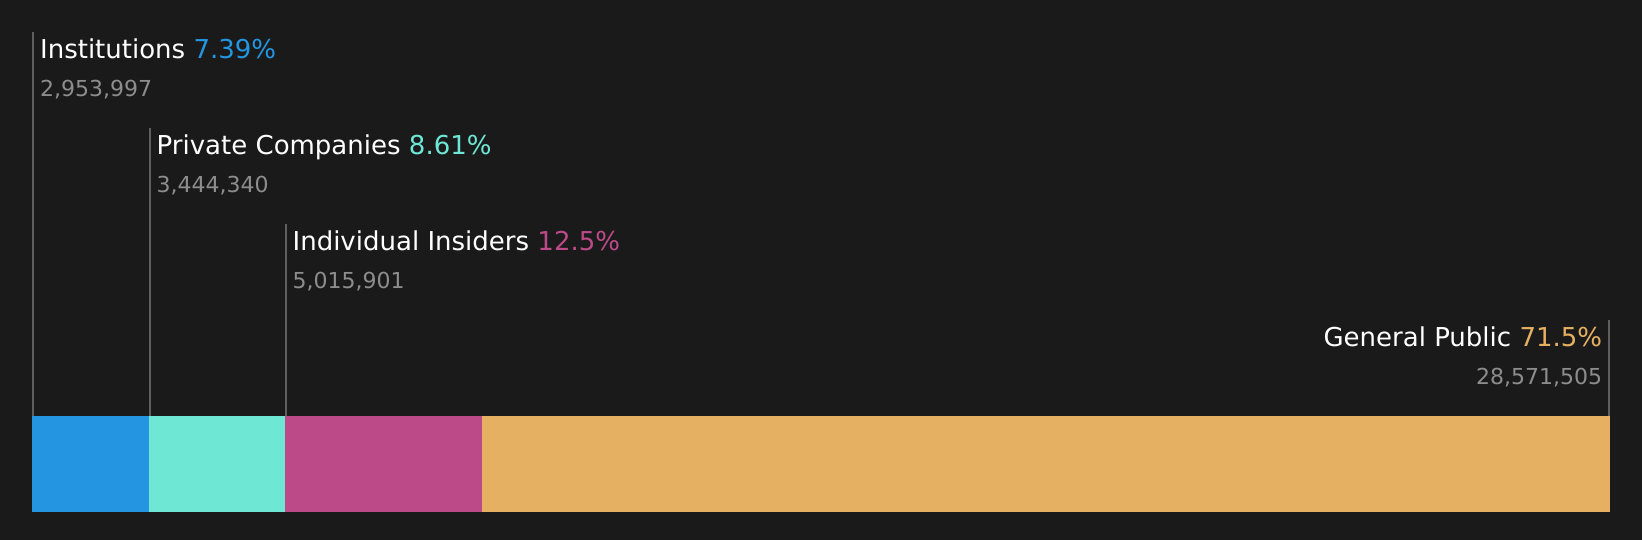
Insider Ownership: 10.6%
Earnings Growth Forecast: 62.7% p.a.
IntelliEPI (Cayman) showcases strong growth potential with forecasted earnings growth of 62.7% annually over the next three years, significantly outpacing the TW market. Despite recent share price volatility and past shareholder dilution, revenue is expected to grow at 31.8% per year, surpassing market averages. Recent earnings announcements revealed increased sales but a decline in quarterly net income compared to last year, though profitability improved over six months with TWD 97.59 million net income reported.
- Delve into the full analysis future growth report here for a deeper understanding of IntelliEPI (Cayman).
- The analysis detailed in our IntelliEPI (Cayman) valuation report hints at an inflated share price compared to its estimated value.
Sansan (TSE:4443)
Simply Wall St Growth Rating: ★★★★★☆
Overview: Sansan, Inc. is a Japanese company that plans, develops, and sells cloud-based solutions with a market cap of ¥267.67 billion.
Operations: The company's revenue segments include the Sansan/Bill One Business, which generated ¥46.85 billion, and the Eight Business, contributing ¥6.72 billion.
Insider Ownership: 39.4%
Earnings Growth Forecast: 23.6% p.a.
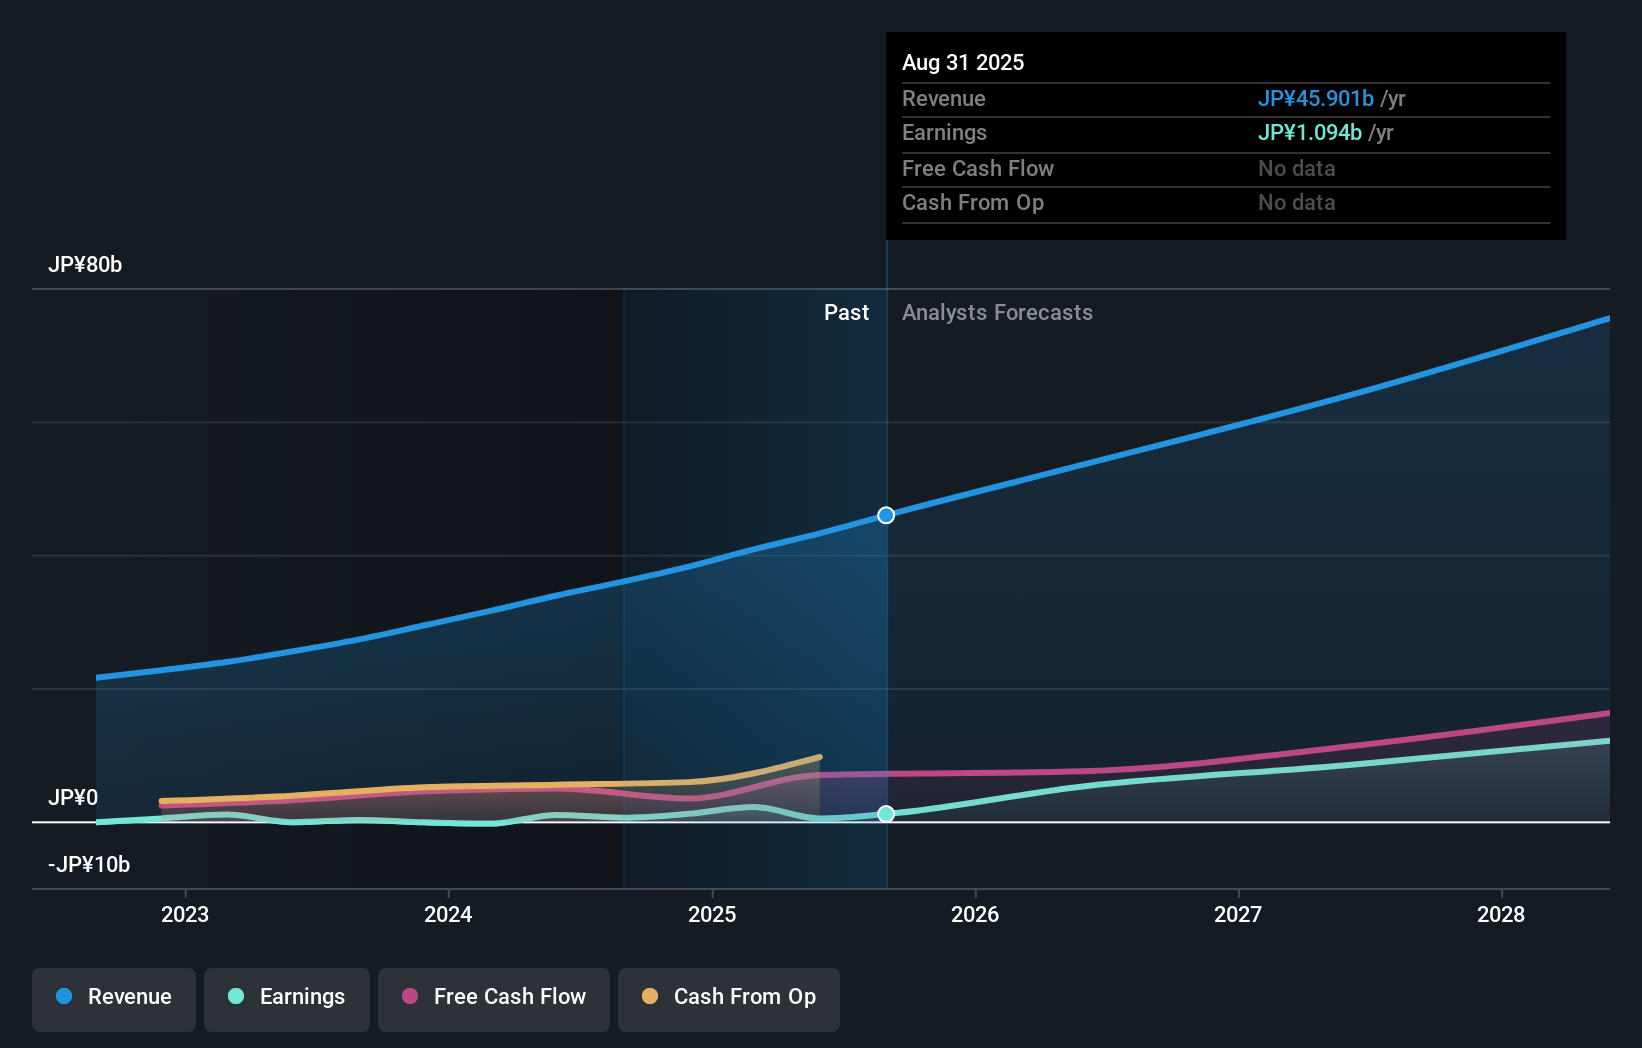
Sansan demonstrates robust growth potential with earnings surging by a very large percentage over the past year and forecasted to grow 23.65% annually, significantly outpacing the JP market. Despite high share price volatility, Sansan is trading at 54.7% below its estimated fair value. Recent financial results showed sales of ¥53.76 billion and net income of ¥6.78 billion for the year ended May 31, 2026, highlighting substantial revenue growth compared to last year.
- Navigate through the intricacies of Sansan with our comprehensive analyst estimates report here.
- Our valuation report unveils the possibility Sansan's shares may be trading at a discount.
Fortune Electric (TWSE:1519)
Simply Wall St Growth Rating: ★★★★★☆
Overview: Fortune Electric Co., Ltd. manufactures, processes, and trades transformers, distribution panels, low voltage switches, and substation equipment in Taiwan and internationally with a market cap of NT$243.92 billion.
Operations: The company's revenue segments include NT$1.16 billion from General Contracting and NT$22.98 billion from Mechanical and Electrical operations.
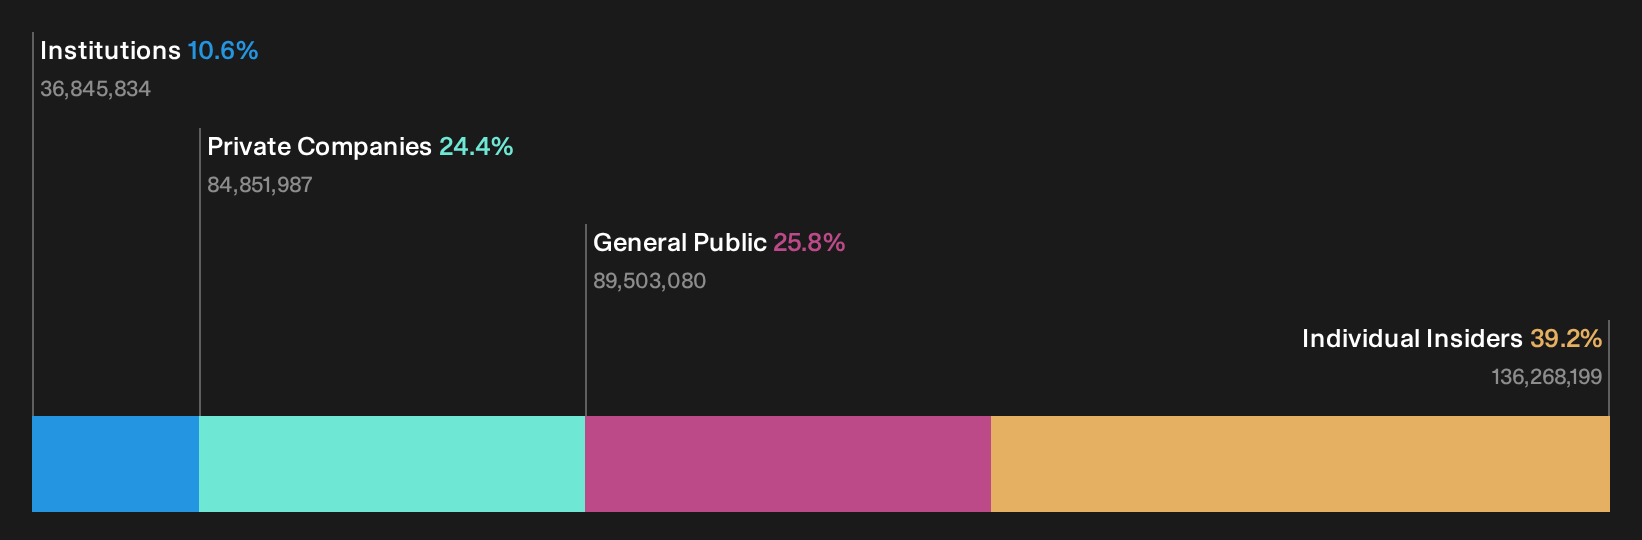
Insider Ownership: 39.2%
Earnings Growth Forecast: 30.1% p.a.
Fortune Electric showcases promising growth prospects with earnings forecasted to grow 30.1% annually, surpassing the Taiwan market's average. Despite a decrease in second-quarter sales to TWD 5.46 billion, net income rose significantly to TWD 1.02 billion, reflecting strong profitability and a substantial increase in earnings per share from continuing operations. Analysts anticipate a stock price rise of 26.1%, although insider trading activity remains limited over recent months, indicating stable insider confidence without significant buying or selling actions.
- Click to explore a detailed breakdown of our findings in Fortune Electric's earnings growth report.
- In light of our recent valuation report, it seems possible that Fortune Electric is trading beyond its estimated value.
Where To Now?
- Click here to access our complete index of 495 Fast Growing Asian Companies With High Insider Ownership.
- Interested In Other Possibilities? Trump has pledged to "unleash" American oil and gas and these 22 US stocks have developments that are poised to benefit.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.The analysis only considers stock directly held by insiders. It does not include indirectly owned stock through other vehicles such as corporate and/or trust entities. All forecast revenue and earnings growth rates quoted are in terms of annualised (per annum) growth rates over 1-3 years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com