
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Only Three Days Left To Cash In On Tele2's (STO:TEL2 B) Dividend
It looks like Tele2 AB (publ) (STO:TEL2 B) is about to go ex-dividend in the next 3 days. The ex-dividend date is two business days before a company's record date in most cases, which is the date on which the company determines which shareholders are entitled to receive a dividend. It is important to be aware of the ex-dividend date because any trade on the stock needs to have been settled on or before the record date. Meaning, you will need to purchase Tele2's shares before the 12th of October to receive the dividend, which will be paid on the 16th of October.
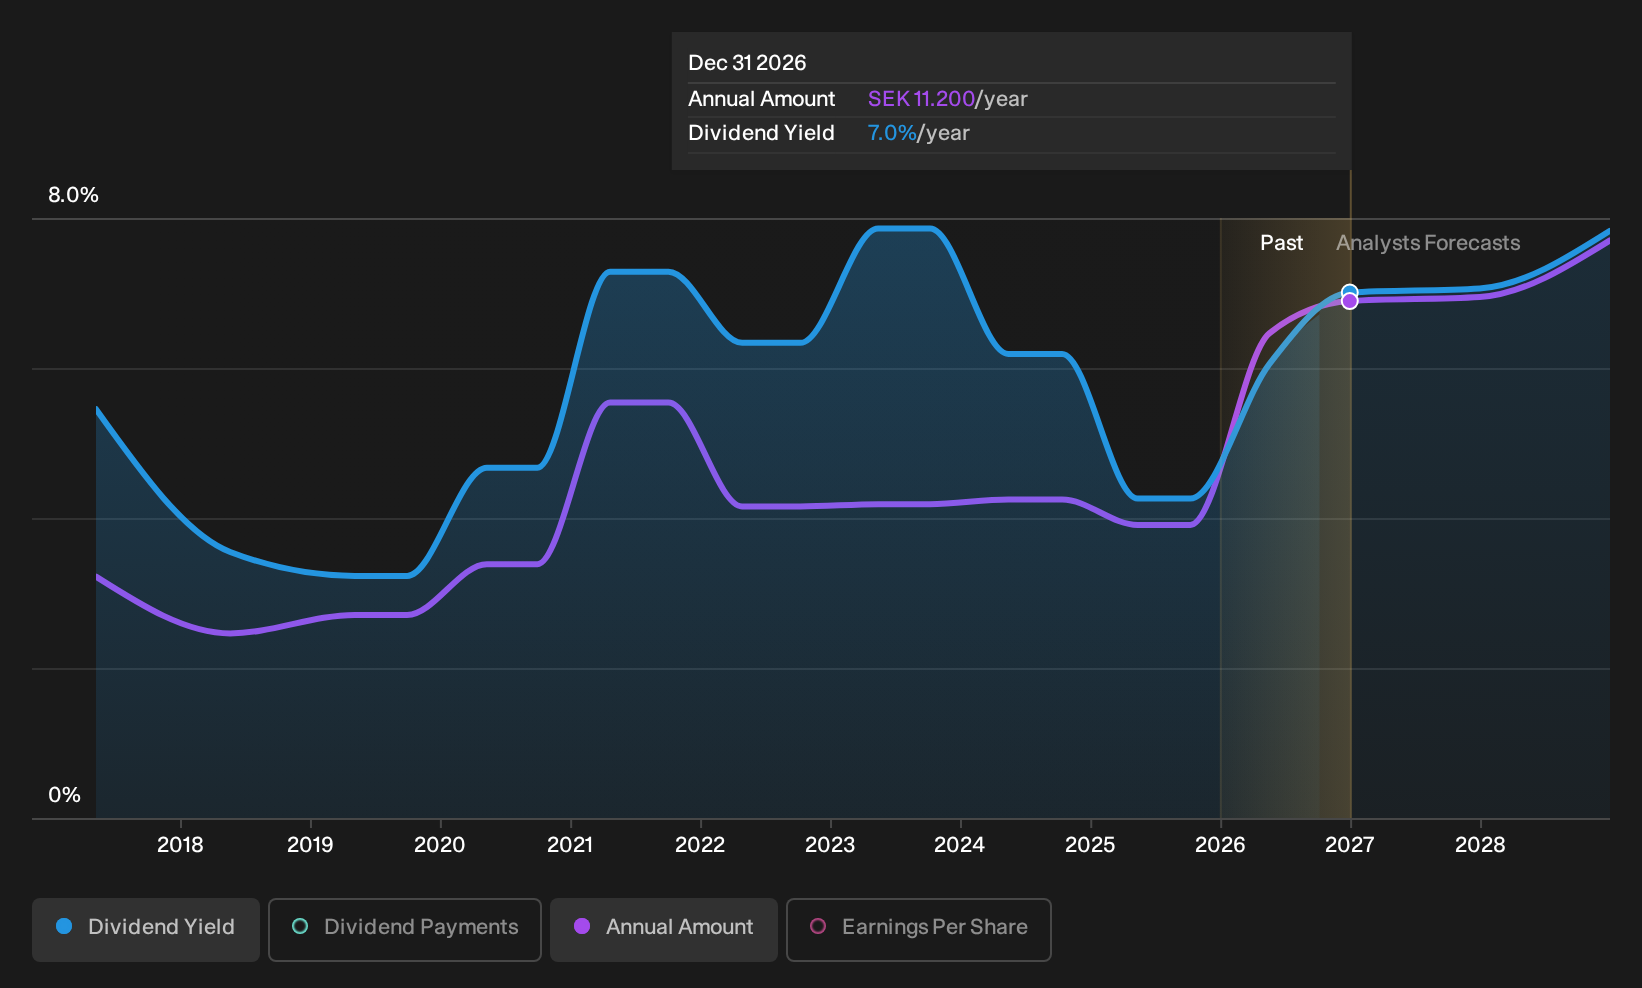
The company's next dividend payment will be kr05.25 per share, on the back of last year when the company paid a total of kr10.50 to shareholders. Based on the last year's worth of payments, Tele2 stock has a trailing yield of around 6.6% on the current share price of kr0159.85. If you buy this business for its dividend, you should have an idea of whether Tele2's dividend is reliable and sustainable. So we need to investigate whether Tele2 can afford its dividend, and if the dividend could grow.
Dividends are typically paid out of company income, so if a company pays out more than it earned, its dividend is usually at a higher risk of being cut. Tele2 is paying out an acceptable 72% of its profit, a common payout level among most companies. Yet cash flow is typically more important than profit for assessing dividend sustainability, so we should always check if the company generated enough cash to afford its dividend. It paid out 75% of its free cash flow as dividends, which is within usual limits but will limit the company's ability to lift the dividend if there's no growth.
It's encouraging to see that the dividend is covered by both profit and cash flow. This generally suggests the dividend is sustainable, as long as earnings don't drop precipitously.
See our latest analysis for Tele2
Click here to see the company's payout ratio, plus analyst estimates of its future dividends.
Have Earnings And Dividends Been Growing?
Businesses with strong growth prospects usually make the best dividend payers, because it's easier to grow dividends when earnings per share are improving. If business enters a downturn and the dividend is cut, the company could see its value fall precipitously. This is why it's a relief to see Tele2 earnings per share are up 6.7% per annum over the last five years. While earnings have been growing at a credible rate, the company is paying out a majority of its earnings to shareholders. If management lifts the payout ratio further, we'd take this as a tacit signal that the company's growth prospects are slowing.
The main way most investors will assess a company's dividend prospects is by checking the historical rate of dividend growth. Since the start of our data, 10 years ago, Tele2 has lifted its dividend by approximately 7.0% a year on average. We're glad to see dividends rising alongside earnings over a number of years, which may be a sign the company intends to share the growth with shareholders.
Final Takeaway
Is Tele2 an attractive dividend stock, or better left on the shelf? Earnings per share growth has been unremarkable, and while the company is paying out a majority of its earnings and cash flow in the form of dividends, the dividend payments don't appear excessive. In summary, while it has some positive characteristics, we're not inclined to race out and buy Tele2 today.
If you're not too concerned about Tele2's ability to pay dividends, you should still be mindful of some of the other risks that this business faces. Our analysis shows 4 warning signs for Tele2 that we strongly recommend you have a look at before investing in the company.
Generally, we wouldn't recommend just buying the first dividend stock you see. Here's a curated list of interesting stocks that are strong dividend payers.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team (at) simplywallst.com.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.