
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
How Investors May Respond To FMC (FMC) Brazil Herbicide Filing
- FMC Corporation has filed a regulatory dossier in Brazil for rimisoxafen, a first in class dual mode of action herbicide targeting resistant broadleaf weeds in large soybean and corn acreage, following its prior submission to the U.S. Environmental Protection Agency in July 2026.
- This move underscores FMC’s push to grow its portfolio of proprietary herbicide active ingredients in high value crops, as growers seek new tools against Amaranthus species that are already resistant to common chemistries.
- We will now examine how FMC's investment narrative could be influenced by the Brazil filing for its dual mode herbicide.
Scan FMC's weed control breakthrough against a curated field of agriculture and materials players by checking out the 33 best rare earth metal stocks that could be setting up their own breakout stories.
FMC Investment Narrative Recap
To own FMC, an investor needs to believe the herbicide and broader crop protection pipeline can gradually offset pricing pressure, generic competition, and the drag from legacy products. The rimisoxafen filing in Brazil fits that thesis, but it does not change the near term reality of weak pricing guidance in 2026, especially in the non diamide portfolio.
The key short term swing factor remains whether new proprietary actives can ramp volumes fast enough to support EBITDA and help service FMC's debt load, given interest expenses of around US$275 million to US$285 million guided for 2026. The biggest risk is that regulatory or market adoption hurdles slow this ramp, leaving leverage and earnings pressure in place.
Among recent developments, the push to advance Isoflex and Dodhylex through regulatory processes in Brazil sits closest to the rimisoxafen story. FMC is trying to build a cluster of proprietary actives in a single, very large row crop region. Success here would give the firm more control over its product mix and potentially reduce reliance on older, more exposed chemistries.
Execution risk is real. Rimisoxafen is not yet registered anywhere, and Brazil remains a tightly regulated market where scrutiny of crop chemicals is high. If approvals for these new actives take longer than investors expect, or if adoption lags because growers stay focused on cheaper generics, the timing of any EBITDA recovery and debt reduction at FMC could slip.
What The Brazil Filing Means Against FMC's Forecasts
FMC's narrative projects US$3.9b revenue and US$313.5 million earnings by 2029. Analysts are incorporating 6.6% yearly revenue growth and an earnings improvement of about US$3.0b, from a loss of US$2.7b today to that 2029 profit figure.
Uncover why FMC's fair value indicates a 49% potential upside to its current price that may not last much longer.
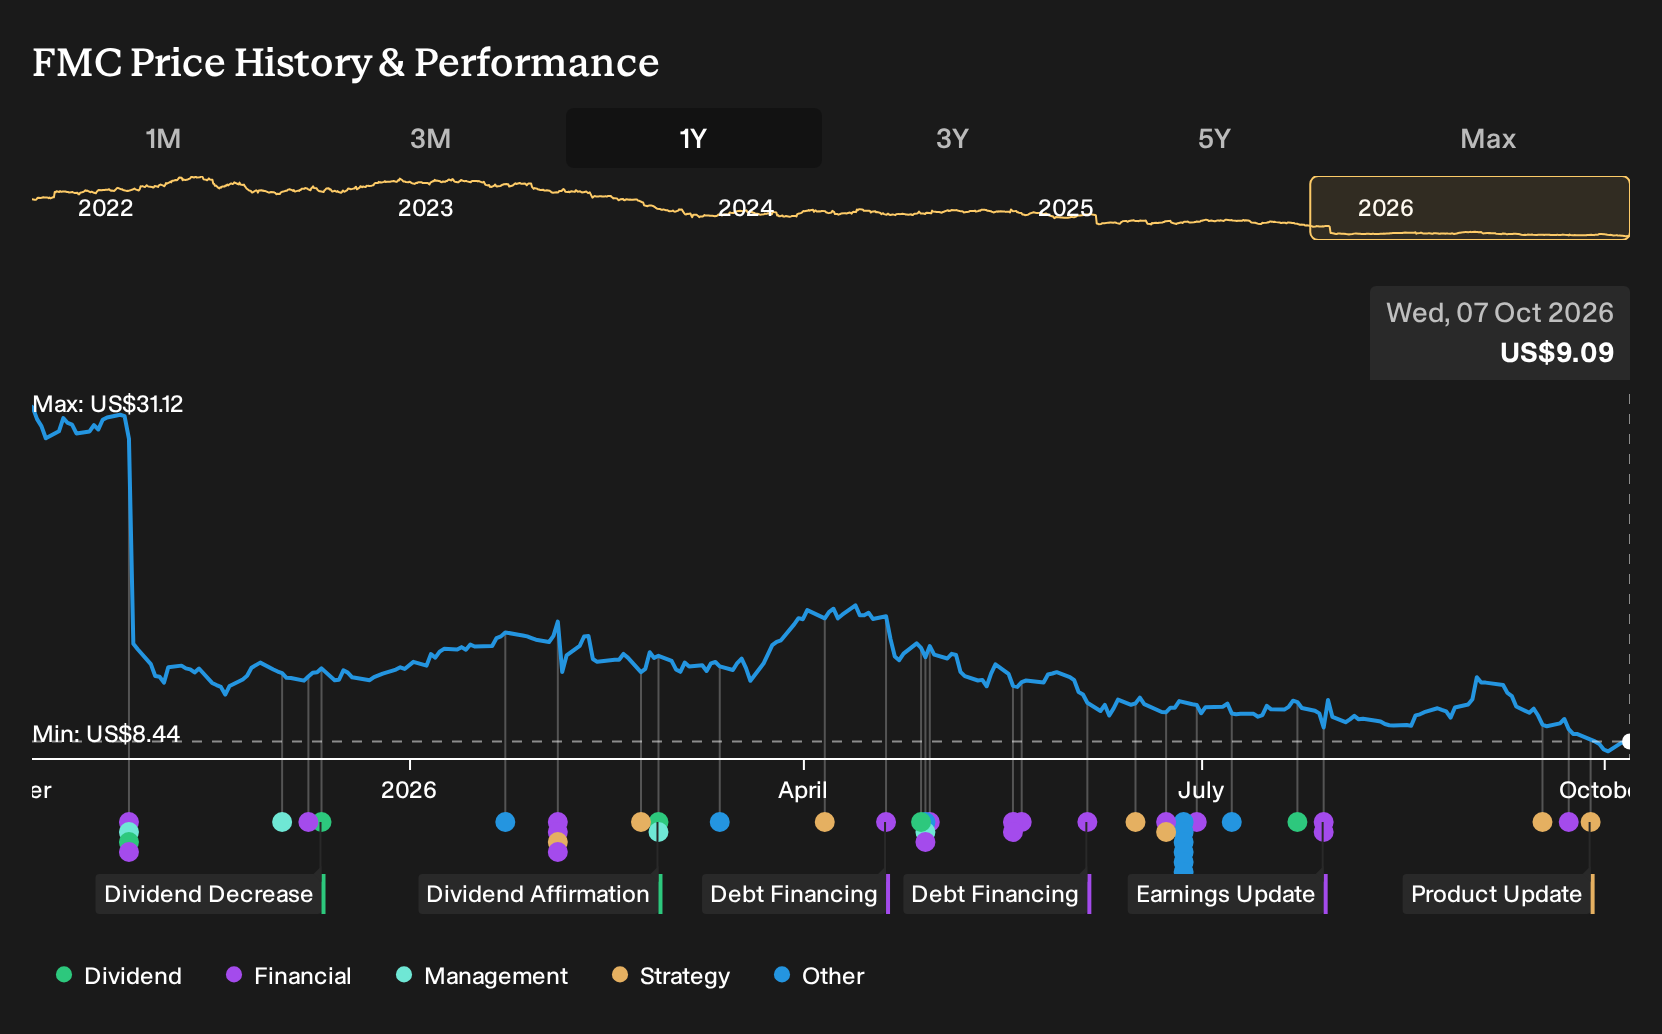
Exploring Other Perspectives
Some bullish analysts frame FMC as a deleveraging story instead of a pure pricing risk story, and before this rimisoxafen news they were already penciling in revenue of about US$4.6b and earnings near US$592.9 million by 2029. You can compare that optimism with the more cautious forecasts and decide which camp you lean toward.
Explore 4 other FMC fair value estimates, including one that suggests as much as 162% upside from the current price.
Decide For Yourself
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your FMC research is our analysis highlighting 3 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for FMC. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate FMC's overall financial health at a glance.
Looking For More Investment Ideas Beyond FMC?
If the rimisoxafen story has you rethinking where crop chemistry fits in your portfolio, it can help to set FMC alongside a broader watchlist of potential opportunities. The Simply Wall St screener lets you filter by quality, balance sheet strength, income focus, and more, so you can benchmark this stock against a range of different profiles.
- For investors who care most about resilient balance sheets and solid fundamentals, start with a list of solid balance sheet and fundamentals (25 results) that can help you stress test ideas against tougher conditions.
- If potential mispricing is your priority, scan the 29 high quality undervalued stocks to spot companies where quality metrics and current pricing look out of sync.
- Income focused readers who want yield alongside staying power can review a curated 8 dividend fortresses that screens for higher payout levels backed by stronger fundamentals.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com