
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
What Investors Might Be Missing On ANTA Sports Products (SEHK:2020)
ANTA Sports Products (SEHK:2020) has completed the purchase of a 29.06% stake in PUMA SE, becoming its largest shareholder. This acquisition strengthens the Chinese sportswear group’s presence in the global athletic market.
Despite the PUMA stake marking a clear push overseas, ANTA Sports Products’ recent trading tells a more cautious story, with the share price at HK$71.35 and a year to date share price return down 12.88% while the 1 year total shareholder return has declined 17.42%, pointing to fading momentum even as management pursues expansion.
Look beyond ANTA Sports Products and assess other athletic and consumer brands that our analysts have filtered into the 619 high quality undiscovered gems list, which features companies with strong fundamentals and room to prove themselves.
The PUMA stake plants a new flag for ANTA Sports Products, while the share price has drifted. Is most of the re-rating already spent, or is the market still underpricing this shift?
Most Popular Narrative: 32% Undervalued
Against a last close of HK$71.35, the most followed valuation storyline for ANTA Sports Products points to a fair value of around HK$104.62, which implies a wide gap that investors need to test against their own expectations.
The deployment of advanced AI technologies in operations, product design, and marketing is set to increase efficiency and sales conversion rates, which may enhance operating profit margins and contribute to earnings growth.
See why 24 investors see ANTA Sports Products as 32% undervalued.
The narrative applies a 9.16% discount rate to those future cash flows and assumes ANTA Sports Products can keep expanding its multi brand portfolio while margins ease from current levels. That combination, together with analysts’ revenue and earnings forecasts, underpins the HK$104.62 figure and the conclusion that the shares trade at a wide discount today.
Result: Fair Value of HK$104.62 (UNDERVALUED)
Still, rising competition in China and higher advertising and R&D spending could squeeze ANTA Sports Products’ margins and challenge the upbeat valuation story.
Find out about the key risks to this ANTA Sports Products narrative.
Another View On ANTA Sports Products Valuation
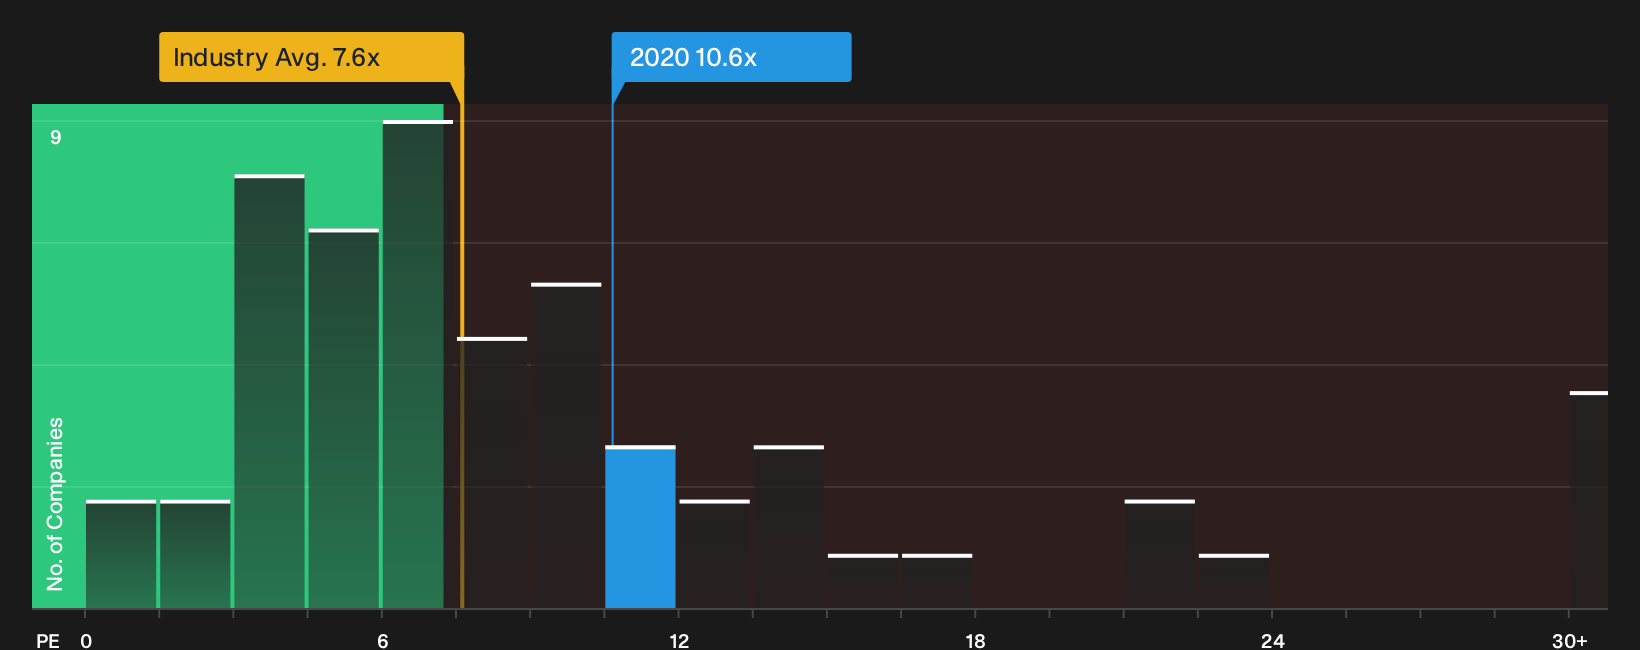
The wide 32% gap to the HK$104.62 fair value comes from a discounted cash flow model. The market sends a different signal when you look at simple pricing. ANTA Sports Products trades on a P/E of 10.6x, slightly above peers at 10.1x and the Hong Kong Luxury industry at 7.6x, and above a fair ratio of 9.5x, which suggests less obvious upside and more room for sentiment to swing.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If this mix of caution and optimism around ANTA Sports Products leaves you undecided, consider reviewing the underlying data yourself, starting with 4 key rewards and 1 important warning sign.
Looking for more investment ideas beyond ANTA Sports Products?
Do not stop at ANTA Sports Products. Use the Simply Wall Street Screener to surface fresh ideas that fit your goals before the market moves without you.
- Target potential mispricing by scanning a 185 high quality undervalued stocks that filters for quality businesses trading below their estimated worth.
- Strengthen your focus on resilience through a list of solid balance sheet and fundamentals (207 results) that highlights companies with robust financial footing.
- Reduce surprises by reviewing a 225 resilient stocks with low risk scores that screens for stocks with lower overall risk profiles.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com