
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Is BioNTech (BNTX) Undervalued On Pipeline Promise Despite Revenue Of €2,650.0 Million And Losses?
BioNTech (NasdaqGS:BNTX) comes into focus after its latest figures showed annual revenue of €2,650.0 million alongside a net loss of €1,686.4 million, prompting investors to reassess expectations for this mRNA and oncology specialist.
Recent trading shows BioNTech losing near term momentum, with the share price down 3.1% over the past week and 8.2% over the last month, even though the 90 day share price return of 2.44% contrasts with a much weaker 5 year total shareholder return that has fallen 61.44%.
Scan beyond BioNTech and compare its recent setbacks with a curated 29 high quality undervalued stocks that combines solid cash flows with balance sheets built to handle tougher conditions.
Bulls view BioNTech as a discounted entry into mRNA and oncology, while bears point to losses and a long pipeline road. Which side do the current valuation markers appear to favor next?
Most Popular Narrative: 19% Undervalued
BioNTech's most followed valuation storyline pegs fair value at $118.06 against a last close of $95.25, which frames the current share price as a discount that depends heavily on oncology execution and the Covid pivot.
Robust pipeline expansion in oncology, with multiple late-stage (Phase II/III) clinical trials for BNT327 and mRNA cancer immunotherapies across high-prevalence cancers (lung and breast), is described as positioning BioNTech to launch multiple new products, potentially driving top-line revenue growth and enhancing earnings visibility. Deep investment and advances in mRNA platform technologies, supported by the planned CureVac acquisition and expanding R&D infrastructure, are cited as enhancing BioNTech's ability to compete in the market for personalized medicine, targeting broader patient populations and supporting margin expansion.
See why 71 investors see BioNTech as 19% undervalued.
Result: Fair Value of $118.06 (UNDERVALUED)
Still, the BioNTech story can break if Comirnaty demand keeps fading, or if key oncology trials disappoint, leaving high R&D spend without matching new revenue streams.
Find out about the key risks to this BioNTech narrative.
Another View On BioNTech's Valuation
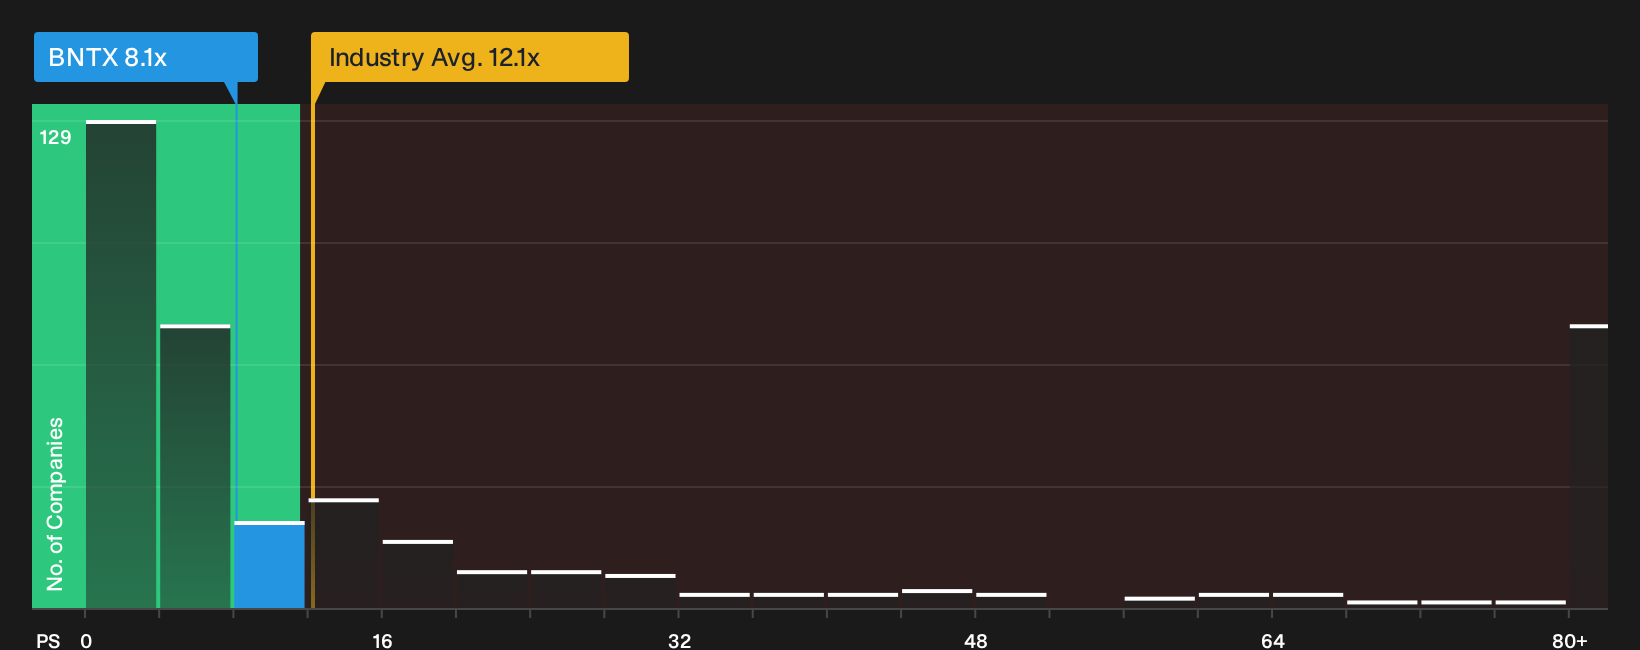
While the analyst narrative frames BioNTech as 19% undervalued against a fair value of $118.06, the current P/S ratio of 8.1x paints a different picture. That level is higher than the peer average of 5.1x and also above a fair ratio estimate of 6.7x, which suggests less margin for error if execution slips. Which signal do you treat as the anchor for your own work?
For investors who prefer to lean on this kind of relative pricing check, the fuller breakdown of how the market could move toward that fair ratio adds useful context, especially when you compare BioNTech against other drug developers using the same lens. See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Looking For More Investment Ideas Beyond BioNTech?
Do not stop with BioNTech. Use the Simply Wall Street screener to pressure test your thesis against fresh opportunities that fit different risk and income profiles.
- Target resilient balance sheets and steady fundamentals by scanning the list of solid balance sheet and fundamentals (25 results) that many investors overlook when volatility rises.
- Hunt for mispriced opportunities by reviewing the 20 high quality undiscovered gems before more capital crowds into the same limited group of quality businesses.
- Prioritise sleep-at-night stability by weighing companies in the 31 resilient stocks with low risk scores so you are not forced into tough decisions at the worst possible time.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com