
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Schneider National (SNDR), What Is Behind The Fresh Attention?
Schneider National (SNDR) is back on investor radar after fresh attention on its multimodal trucking, intermodal, and logistics network across North America. This has prompted a closer look at how the business is currently priced.
Recent trading tells a mixed story for Schneider National. The share price is down 11% over the past month and 16% over the past quarter, yet the year-to-date share price return of 15.6% and 1-year total shareholder return of 36.4% point to momentum that has cooled rather than reversed.
Scan beyond Schneider National and identify other transport and logistics stocks with fresh price momentum and solid business profiles using our hand-picked 29 high quality undervalued stocks.
Schneider National’s slide over the past quarter sits awkwardly against its stronger 1-year and multi-year returns. Is this about weaker conviction in the business, or a reset in sentiment that changes how the valuation stacks up?
Most Popular Narrative: 17% Undervalued
On the widely followed thesis, Schneider National screens as undervalued, with a fair value of $37.50 against a last close of $31.19 and a discount rate of 8.3% anchoring the model.
Continued investment in technology and AI driven tools across Schneider National’s logistics, driver support and recruiting operations, including reported 17% productivity gains in frontline logistics staff and ongoing cost savings programs of US$40 million in both 2025 and 2026, is expected by some analysts to lead to further operating expense efficiency that they believe can support higher net margins and earnings over time.
See why 6 investors see Schneider National as 17% undervalued.
Result: Fair Value of $37.50 (UNDERVALUED)
Still, the thesis on Schneider National can be knocked off course if freight demand softens again, or if Dedicated customer churn and competition squeeze margins harder than expected.
Find out about the key risks to this Schneider National narrative.
Another View On Schneider National’s Valuation
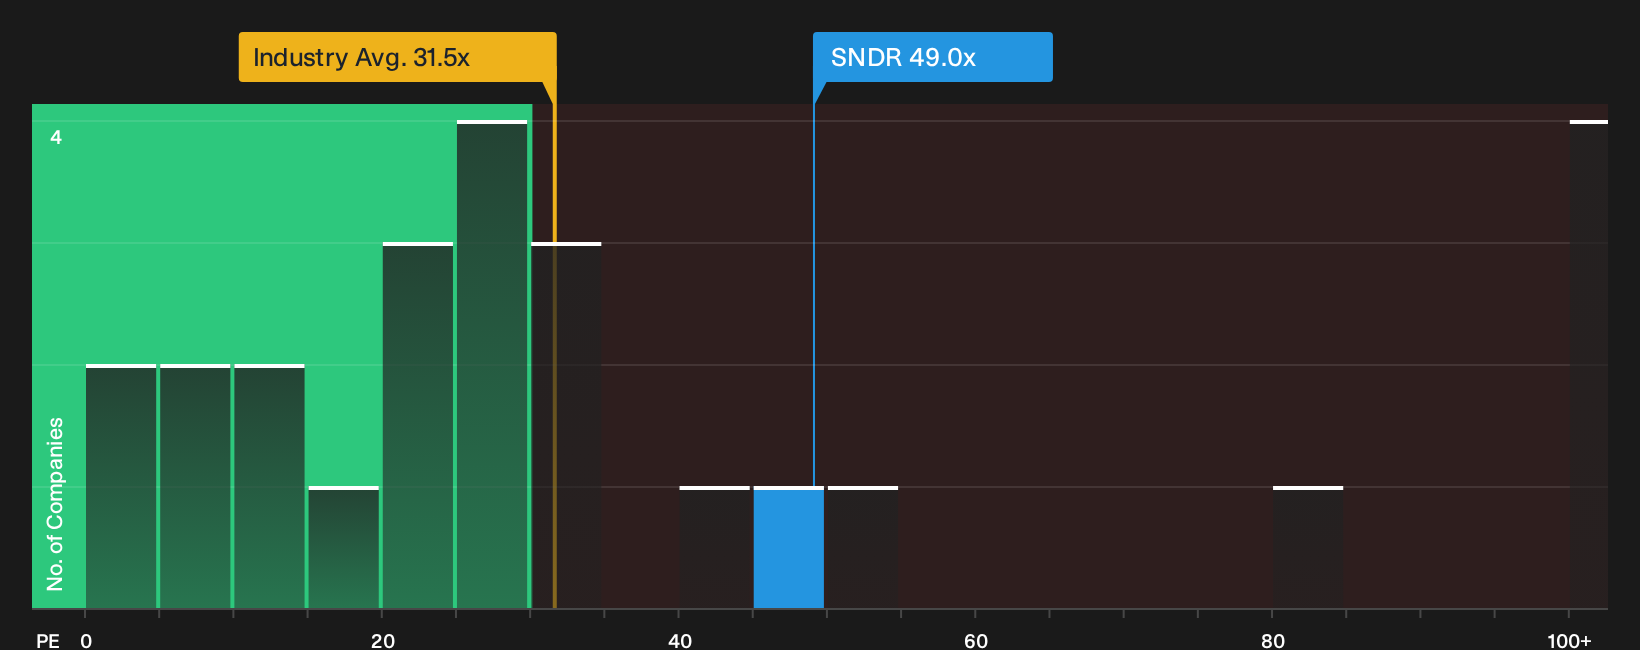
The earlier fair value of $37.50 relies on cash flow and earnings forecasts. A different lens uses the current P/E of 49x, which screens as expensive versus a fair ratio of 34.5x and a US Transportation average of 31.5x, even though peers average a richer 68.4x. So is Schneider National priced for perfection or just catching up?
Investors who want to see how this earnings based picture lines up with cash flow assumptions can walk through the full methodology in our valuation breakdown, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment on Schneider National is split, which is exactly when fresh data can matter most. Move quickly and pressure test your own view using the 2 key rewards.
Looking for more investment ideas beyond Schneider National?
Do not stop at Schneider National. Broaden your watchlist with a fresh set of ideas built from different angles on quality, value, and resilience.
- Target potential mispricing by scanning a curated pool of 29 high quality undervalued stocks that combine solid fundamentals with room for sentiment to shift.
- Build a more resilient portfolio by reviewing a list of solid balance sheet and fundamentals (25 results) that can help you focus on financial strength when conditions turn choppy.
- Get ahead of the crowd by tracking 20 high quality undiscovered gems that have strong business profiles yet attract less attention from the market.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com