
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Kirby (KEX) Looks Undervalued, Is The Valuation Gap Too Wide To Ignore?
Kirby (KEX) has drawn fresh attention after its recent share price move, with the stock down 1% over the past month but still showing a 23% gain year to date.
That mix of a 22.75% year to date share price gain and a 67.04% total shareholder return over the past year suggests momentum in Kirby is still positive, even though the 90 day share price return of 3.69% indicates some cooling in shorter term enthusiasm.
Scan the broader marine and industrial universe for other stocks that show momentum and fundamentals similar to Kirby by running the hand picked 20 high quality undiscovered gems.
Kirby now trades below both analyst targets and one estimate of intrinsic worth, creating a wide valuation gap after a strong year. Is the current share price a discount, or is it already fair?
Most Popular Narrative: 17% Undervalued
Kirby closed at $137.36, while the most widely followed narrative pegs fair value at about $166.17 using a 7.57% discount rate. That gap reflects a view that structural industry factors and capital allocation could support stronger long term cash generation than the price implies today.
Supply constraints and industry-wide aging of the barge fleet are restraining new capacity growth, with industry inland barge construction around 60 to 70 units per year and newbuild returns still about 40% away from justified economics. This supports limited vessel availability, firmer pricing and the potential for higher Marine Transportation revenue and net margins.
See why 12 investors see Kirby as 17% undervalued.
Result: Fair Value of $166.17 (UNDERVALUED)
Still, the Kirby thesis can be knocked off course if medical cost inflation keeps squeezing margins, or if ongoing weakness in oil and gas equipment demand drags on Distribution and Services.
Find out about the key risks to this Kirby narrative.
Another View: Kirby Through The P/E Lens
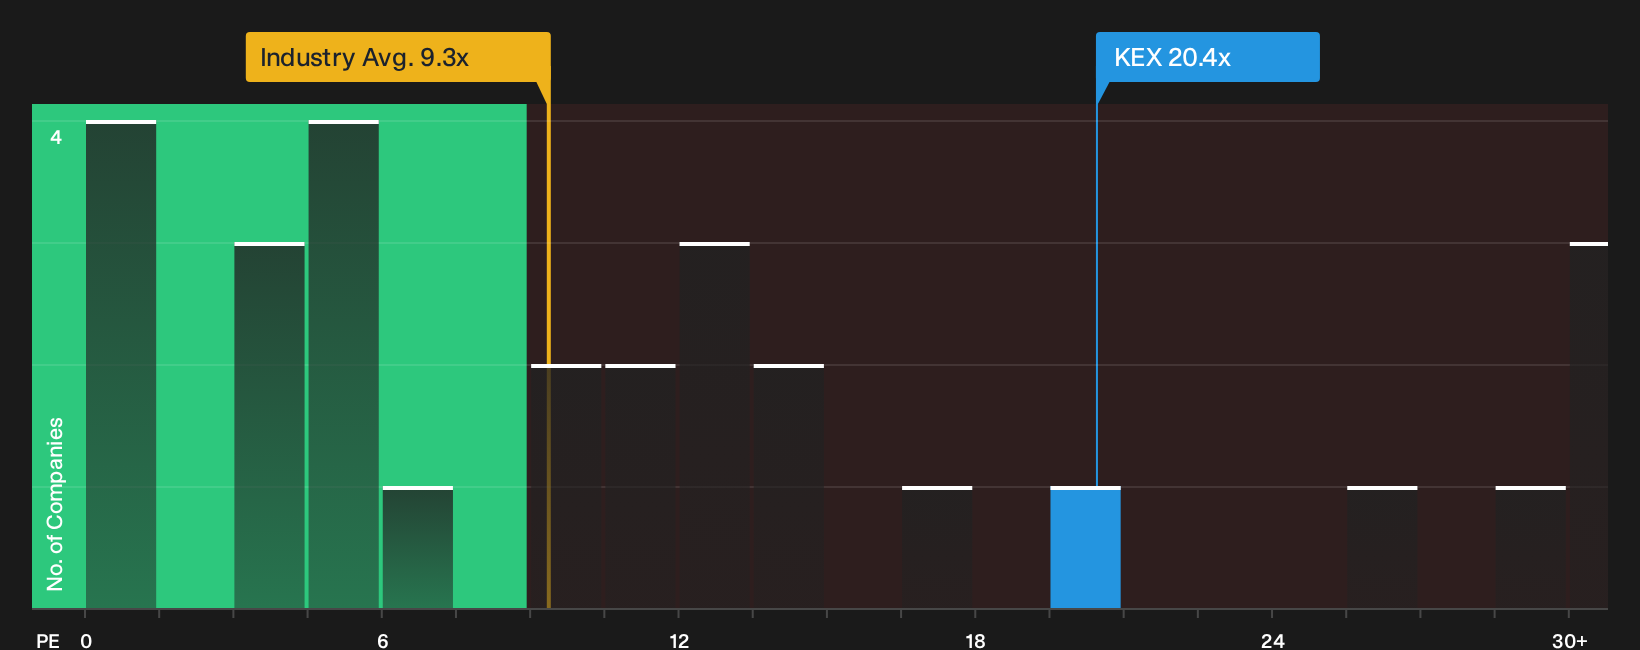
The SWS DCF model points to Kirby trading below an estimate of future cash flow value at $197.42, which supports the idea of an undervalued stock. The earnings multiple tells a different story. Kirby changes hands at a P/E of 20.4x, compared with 9.3x for the US Shipping industry, 14.5x for peers, and a fair ratio of 16.3x. That kind of premium can reward patience if the long term thesis plays out. However, how comfortable are you paying up on today’s earnings for a company that already screens as expensive on this metric?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment around Kirby is mixed enough that you probably should not outsource the conclusion to anyone else. Take a few minutes to test the upside for yourself by reviewing the 3 key rewards.
Ready For More Investment Ideas Beyond Kirby?
If Kirby has you thinking harder about valuation and momentum, do not stop there. Fresh ideas often come from comparing it with very different opportunities.
- Accelerate your hunt for long term upside by scanning companies that our models flag as mispriced using the 29 high quality undervalued stocks.
- Strengthen your focus on resilience by reviewing a curated list of solid balance sheet and fundamentals (25 results) that can handle tougher conditions without constantly needing fresh capital.
- Target potential yield by lining up income focused opportunities through the 8 dividend fortresses before the most attractive options get crowded.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com