
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Can Houlihan Lokey (HLI) Justify Its Price On Board Changes And Senior Hires?
Houlihan Lokey (HLI) is back in focus after a boardroom change and two senior hires. These developments give investors fresh context for thinking about this advisory focused financial stock.
Recent trading has been softer, with Houlihan Lokey’s share price down 8.7% over the past 30 days and 29.0% year to date, while the 1 year total shareholder return has declined 33.4% but remains positive at 20.4% over three years and 38.7% across five years. This points to longer term holders still being in the green even as momentum has faded ahead of these board and senior hiring announcements.
Compare how Houlihan Lokey stacks up against other advisory-focused financial stocks that also score well on balance sheet strength and fundamentals using our curated list of solid balance sheet and fundamentals (25 results) today.
After a sharp pullback, Houlihan Lokey now sits well below recent levels while still carrying a solid fundamentals tag. Is this the moment to step in, or does patience for a cheaper entry make more sense as the valuation picture comes into focus?
Most Popular Narrative: 18% Undervalued
Houlihan Lokey last closed at $125.22 while the most followed narrative anchors fair value at $153.50. The debate centers on whether the advisory group can deliver on the growth and margin profile reflected in that gap.
The main thing that has to go right is that Houlihan Lokey converts its record Corporate Finance pipelines and growing Capital Solutions and secondaries activity into completed higher fee transactions at a pace that outstrips rising non compensation costs and ongoing investment in technology and data.
See why 7 investors see Houlihan Lokey as 18% undervalued.
Result: Fair Value of $153.50 (UNDERVALUED)
Still, the Houlihan Lokey narrative can crack if muted sponsor activity keeps larger deals on hold, or if rising non compensation costs outpace advisory fee growth.
Find out about the key risks to this Houlihan Lokey narrative.
Another View: Houlihan Lokey Through The P/E Lens
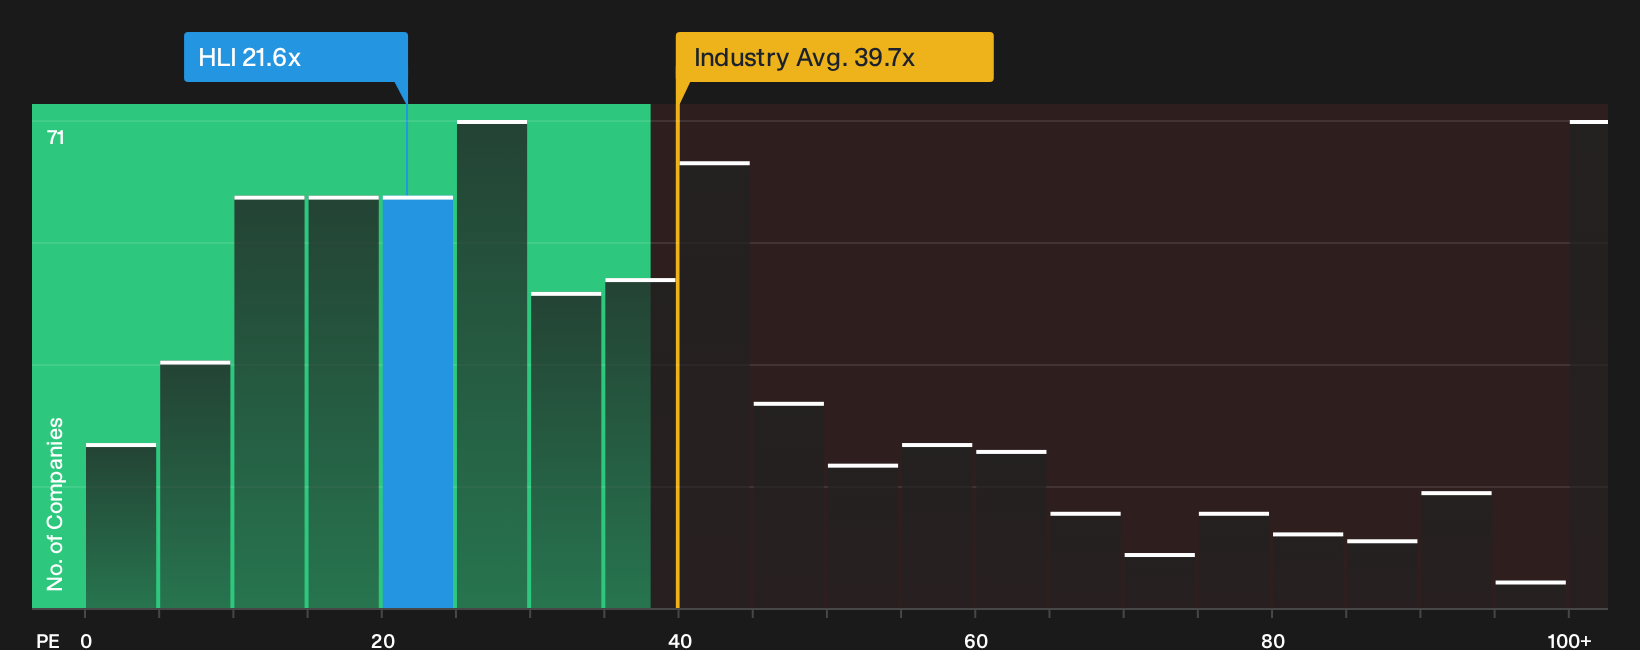
That fair value of $153.50 leans on future earnings power. A simpler yardstick looks at Houlihan Lokey on today’s P/E. The stock trades at 21.6x earnings, which is cheaper than the US Capital Markets group on 39.7x, yet far richer than its own fair ratio of 13x.
That spread means investors are paying a premium to Houlihan Lokey’s historical and modeled relationship between price and earnings, even though the wider industry trades at an even higher multiple. The gap can work in either direction. It could compress toward the peer level or drift closer to the fair ratio. Which side of that trade off feels more realistic to you?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment on Houlihan Lokey is mixed, with some investors focused on valuation gaps and others on the underlying rewards narrative. Act quickly, review the data for yourself, and pressure test both sides of the story by weighing the 4 key rewards.
Looking for more Houlihan Lokey sized investment ideas?
Do not stop your research with Houlihan Lokey. Use the Simply Wall Street Screener to line up fresh candidates that fit the kind of portfolio you actually want to build.
- Target potential upside by reviewing a curated set of 29 high quality undervalued stocks that combine quality fundamentals with prices that screen as below their estimated worth.
- Build a steadier income stream by focusing on 8 dividend fortresses that pair higher yields with fundamental checks on balance sheets and cash generation.
- Lower the overall risk profile of your portfolio by scanning 31 resilient stocks with low risk scores selected for resilience across a broad set of financial health metrics.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com