
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Is Vault Minerals (ASX:VAU) Undervalued On Its Daisy Milano Contract Extension?
Vault Minerals (ASX:VAU) has extended its mining services contract with Macmahon Underground at the Daisy Milano Gold Mine in Western Australia. The agreement keeps operations in place until October 2028 and provides longer-range operational visibility for investors.
At a recent share price of A$5.95, Vault Minerals has seen short term momentum cool with a 30 day share price return down about 10%. However, the 90 day share price return of roughly 22% and a one year total shareholder return of about 29% still point to stronger longer term gains and renewed interest as contracts like Daisy Milano are extended.
Scan how Vault Minerals compares with other ASX resource stocks showing contract-backed momentum by reviewing the 36 elite gold producer stocks in one place.
The recent pullback in Vault Minerals after solid multi year returns raises a simple tension: Are you seeing sentiment cool off, or the market reassessing what the underlying business is worth?
Most Popular Narrative: 31% Undervalued
On RockeTeller’s numbers, Vault Minerals trades at A$5.95 against a narrative fair value of A$8.67. That gap frames the current pullback as a valuation question rather than just a mood swing in the gold space.
"Valuation feel: On this simplified FCF model, Vault looks cheap if the A$916M annualised free cash flow number is sustainable. The issue is sustainability. One strong quarter during a high gold price environment can make annualised FCF look very powerful. The market will want proof that Vault can maintain high cash generation across multiple quarters, keep AISC controlled, and replace reserves."
See why 26 investors see Vault Minerals as 31% undervalued.
According to RockeTeller, that narrative leans heavily on Vault Minerals already being a multi mine producer with 3.997Moz of reserves and a debt free balance sheet, rather than a speculative drill story. The simplified A$916m annualised free cash flow input, when capitalised at 10x, leads to the A$8.67 per share fair value that sits well ahead of today’s share price.
The same narrative also flags the catch. The free cash flow snapshot comes from a strong gold price period and from a business that still needs to keep AISC within guidance, extend mine lives at Leonora, Mount Monger, Deflector and Sugar Zone, and then potentially integrate into a combined Regis group. In practice, that means the gap between A$5.95 and A$8.67 is tied to operational delivery across several mines and the outcome of the Regis scheme process, not just the Daisy Milano contract extension in isolation.
For investors comparing stories across the sector, the key takeaway is that this valuation view treats Vault Minerals as a mature producer where execution, reserve replacement and capital discipline drive value, rather than a binary exploration bet. It frames the recent 30 day pullback of about 10% against a three year total shareholder return of roughly 199% and a five year total shareholder return near 244%, then asks whether the current price still reflects the company’s cash generation and reserve base outlined in the RockeTeller work.
Result: Fair Value of A$8.67 (UNDERVALUED)
Still, the Regis merger outcome and any slip on AISC or reserve replacement could quickly challenge the current Vault Minerals undervaluation story.
Find out about the key risks to this Vault Minerals narrative.
Another View On Vault Minerals’ Valuation
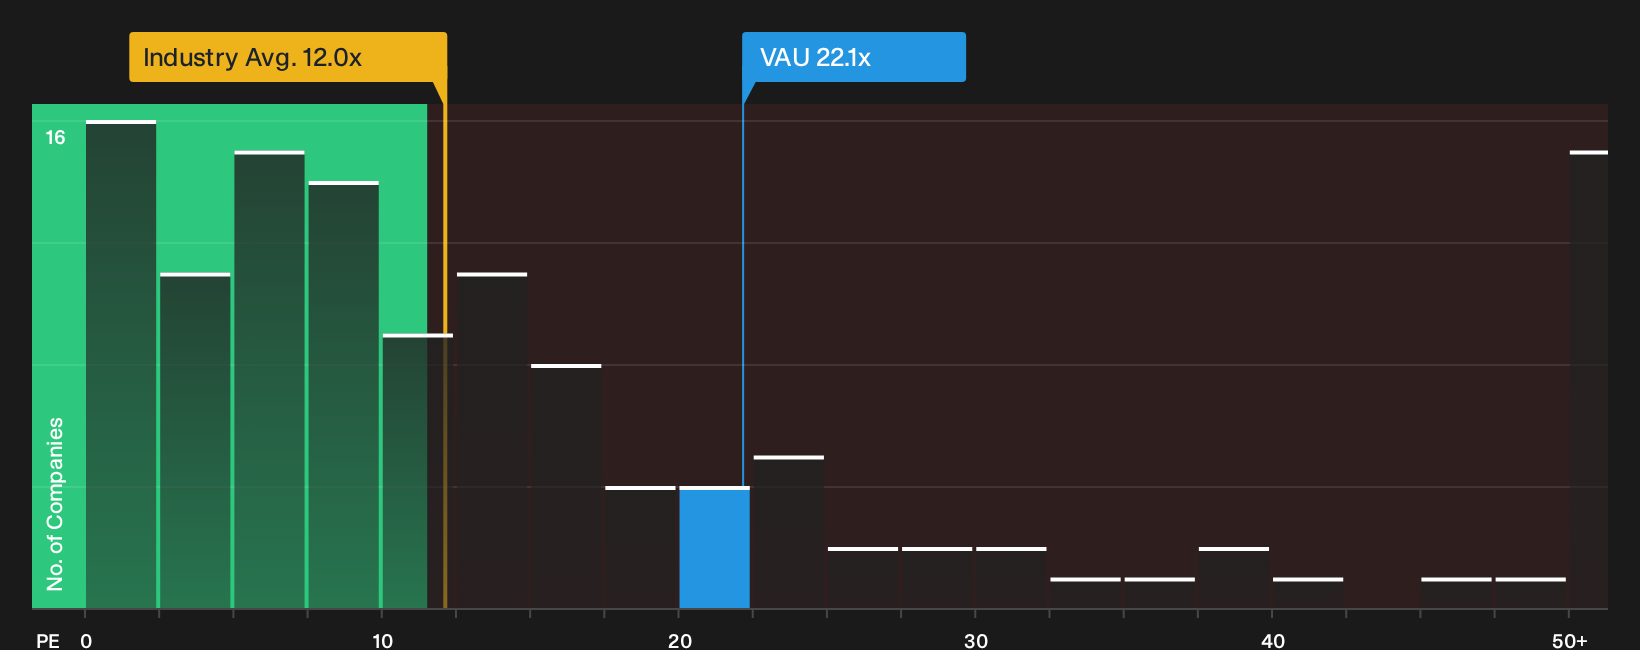
That A$8.67 fair value from RockeTeller paints Vault Minerals as undervalued. The SWS fair ratio tells a different story. At a P/E of 22.1x, VAU trades well above the 16.4x fair ratio, the 12x Australian metals and mining average, and the 12.2x peer group. That gap points to valuation risk if sentiment cools again.
For investors comparing these signals, the question is simple: Does the earnings multiple contract toward the fair ratio, or does future delivery have to catch up with today’s price to keep VAU looking reasonable.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If the Vault Minerals story so far seems conflicted, consider using that to your advantage by checking the data yourself and quickly weighing both sides. To see what optimists are focused on, review the 3 key rewards.
Looking For More Investment Ideas Beyond Vault Minerals?
Vault Minerals might be front of mind today, but the next opportunity you act on could come from a very different corner of the market.
Use the Simply Wall St screener to quickly surface focused shortlists that match what you care about right now. Do not let the next idea pass by unnoticed while attention is locked on a single stock.
- Hunt for mispriced quality and see which companies combine strong fundamentals with attractive valuations through the 5 high quality undervalued stocks.
- Secure potential income ideas first and filter for dependable payers using the 5 dividend fortresses.
- Prioritise resilience under pressure and examine companies that show sturdier profiles with the 7 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com