
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
iFAST (SGX:AIY) Launches Its First ETFs But Is The Valuation Story Already Priced In
iFAST’s First ETFs Hit The Singapore Market
iFAST (SGX:AIY) has moved into ETF issuance, launching four UCITS funds on the Singapore Exchange that track AI and major Asian equity markets including Japan, Korea and Taiwan.
Investors have seen mixed signals from iFAST’s stock recently. The share price is up 1.87% over the past day to SGD8.17, yet down 9.42% over 30 days and 14.18% year to date. The 3-year total shareholder return of 43.93% contrasts with a decline of 12.47% over the past year. This suggests that longer term holders are still ahead even as near term momentum has faded, and this ETF launch becomes a fresh catalyst that could shift how the market prices growth potential and risk around the broader digital wealth platform story.
Scan beyond iFAST to see how other AI oriented ETFs and related plays stack up across our curated list of 147 AI small caps.
ETF issuance opens a new chapter for iFAST while the share price has already given back a chunk of prior gains. Is meaningful upside still ahead, or has most of the easy money already gone?
Most Popular Narrative: 32% Undervalued
The most followed narrative on iFAST puts fair value at SGD11.97 per share, well above the last close at SGD8.17, which frames this ETF launch inside a broader long term growth and profitability story built around its digital wealth and banking platforms.
The ongoing ramp-up and onboarding of trustees for the Hong Kong ePension (eMPF) platform is expected to drive strong and recurring revenue growth in the coming quarters, providing higher margin and operating leverage as onboarding completes and opex efficiencies can be realized.
Expansion in product diversity (unit trusts, ETFs, bonds, margin financing) and regional footprint (entry into the U.K., growth in China, initial Macau flows) supports sticky cross-sell opportunities and client retention, underpinned by rising retirement planning needs in core markets, delivering long-term revenue and profitability growth.
See why 23 investors see iFAST as 32% undervalued.
Result: Fair Value of SGD11.97 (UNDERVALUED)
Still, the bullish iFAST story could wobble if execution in China and the U.K. drags longer than expected or if ePension costs stay stubbornly high.
Find out about the key risks to this iFAST narrative.
Another View On iFAST’s Valuation
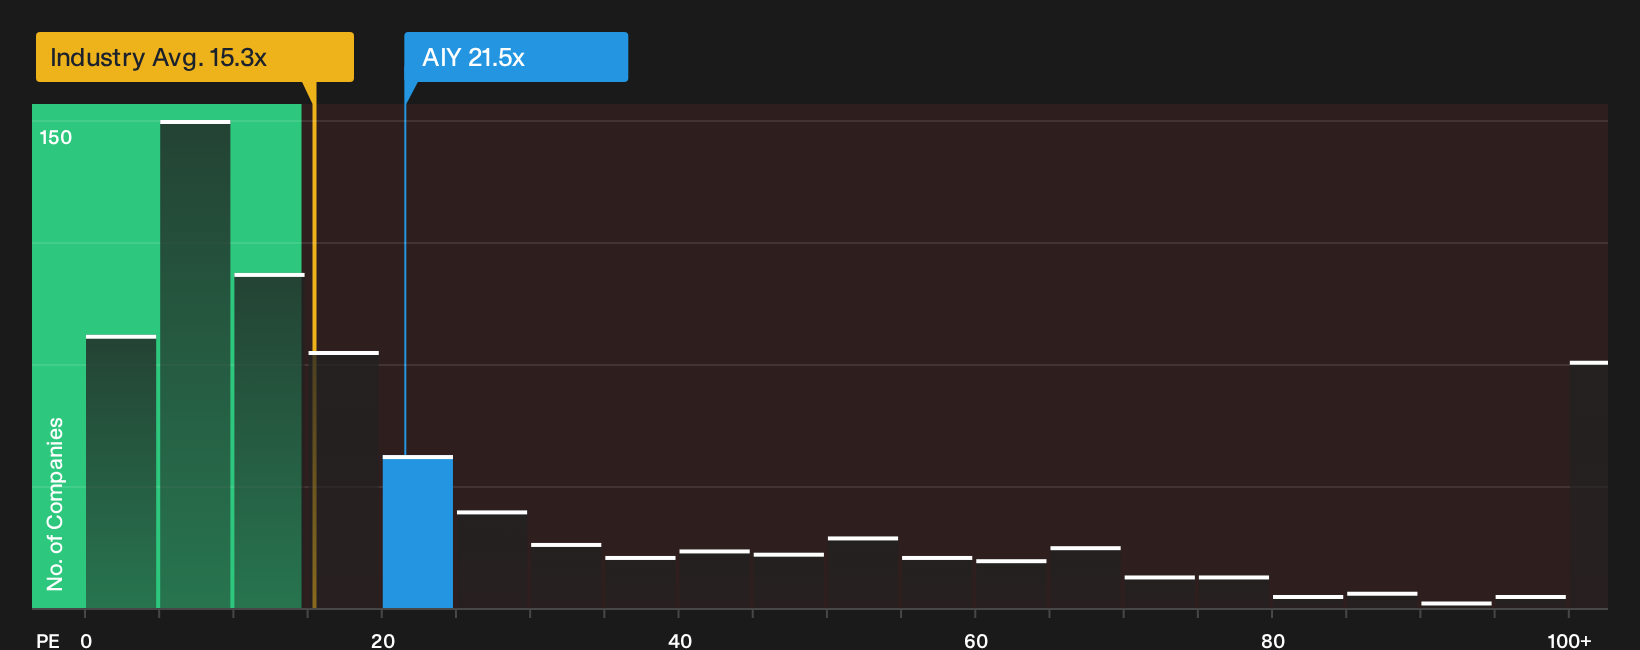
The earlier narrative leaned on cash flow and analyst fair value estimates to argue that iFAST looks undervalued. A different lens using earnings multiples paints a cooler picture. The stock trades on a P/E of 21.5x, while the fair ratio sits at 17.9x and peers are at 8.3x and the wider Asian capital markets group is at 15.3x. That gap suggests investors are already paying a clear premium for iFAST’s profitability and growth profile, so the question is whether you think that premium is justified or whether it leaves less room for upside if expectations slip.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Optimistic or cautious after everything about iFAST so far, the key move now is to test the data yourself and stress your own assumptions against different scenarios. To see what investors currently like most about the business, take a closer look at the 4 key rewards.
Looking For More Investment Ideas Beyond iFAST?
If you want a broader watchlist alongside iFAST, use targeted screeners to surface fresh opportunities and pressure test your portfolio before the crowd spots them.
- Chase value opportunities by scanning a focused set of companies that currently screen as high quality on both fundamentals and valuation using the 185 high quality undervalued stocks.
- Strengthen portfolio resilience by filtering for businesses with cleaner finances and sturdier balance sheets through the list of solid balance sheet and fundamentals (207 results).
- Stay ahead of the market by tracking smaller companies with strong fundamentals that fewer investors are watching via the 619 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com