
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Is Concentra Group Holdings Parent (CON) Undervalued On Its Earnings Beat?
Why Concentra Group Holdings Parent Is Back On Investors’ Radar
Concentra Group Holdings Parent (CON) has jumped into focus after reporting earnings and revenue that topped expectations, extending a four quarter streak of positive surprises and reinforcing the current Zacks Rank #1 rating.
Investors have taken notice of Concentra Group Holdings Parent’s earnings streak, and the momentum is showing up in the tape, with the latest share price at $36.40 and a 90-day share price return of 15.92% contributing to an 87.53% year-to-date gain and a 76.34% total shareholder return over the past year. This signals strong recent enthusiasm around the business compared with where it started the year.
Scan beyond Concentra Group Holdings Parent’s breakout and line up other potential healthcare movers by using the hand picked list of solid balance sheet and fundamentals (25 results) in a similar financial bracket.
After a run to $36.40 and a double digit discount to both intrinsic value estimates and the US$41 analyst target, where does the fair value for Concentra Group Holdings Parent really sit now?
Most Popular Narrative: 9% Undervalued
Concentra Group Holdings Parent is tracking below the most followed fair value estimate of $39.88, with the $36.40 close implying a modest valuation gap that investors are now trying to size against its long term growth story and capital plans.
Employers are intensifying their focus on workforce health compliance and cost control. This is creating fertile ground for growth in workplace injury prevention, drug testing, and onsite wellness programs. Concentra's recent scale expansion through acquisitions and enhanced primary care offerings positions the company to capture a greater share of this expanding market, supporting long-term revenue and margin growth.
See why 3 investors see Concentra Group Holdings Parent as 9% undervalued.
Result: Fair Value of $39.88 (UNDERVALUED)
Still, the bullish narrative around Concentra Group Holdings Parent can unravel if organic visit volumes stay sluggish or if elevated G&A and leverage continue to pressure net income.
Find out about the key risks to this Concentra Group Holdings Parent narrative.
Another View On Concentra Group Holdings Parent’s Valuation
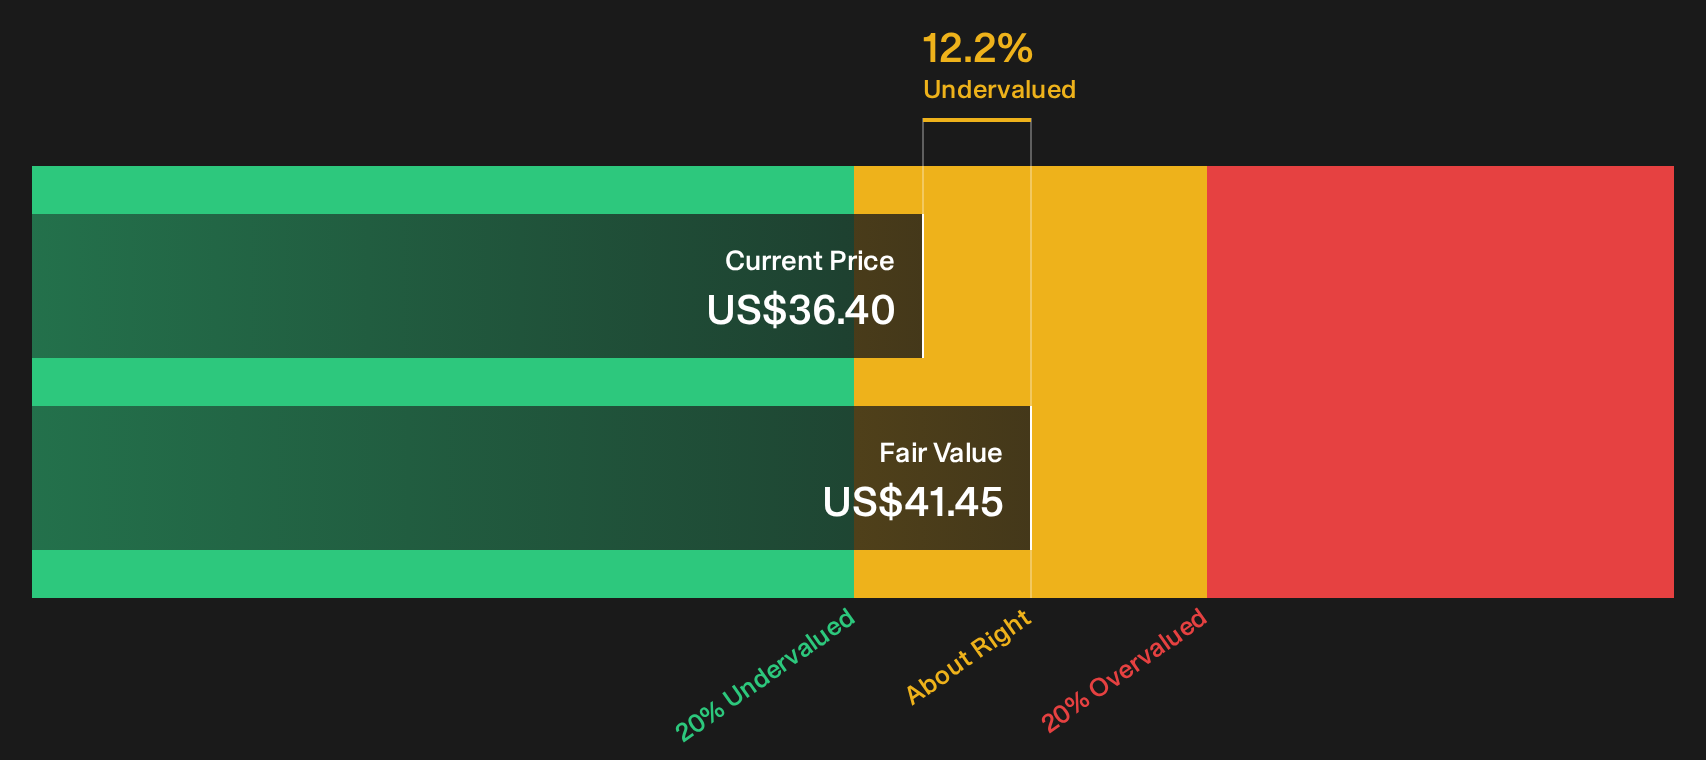
On the first pass, Concentra Group Holdings Parent looks appealing at a $36.40 share price against an $41.45 fair value estimate from the SWS DCF model, which flags the stock as undervalued. A second method tells a different story and is worth weighing before drawing any hard conclusion.
That same SWS DCF model points to a 12.2% gap between price and estimated value. Meanwhile, the P/E of 23.8x sits close to the 23x fair ratio the market could move toward. If earnings growth or debt progress undershoots expectations, the question is whether that discount still appears wide enough to compensate for the risk.
Look into how the SWS DCF model arrives at its fair value.
Next Steps
Whether you feel cautious or encouraged by Concentra Group Holdings Parent so far, the key advantage comes from examining the numbers yourself and weighing them against your own risk tolerance. To balance both the concerns and the potential upsides that others see, review the 3 key rewards and 2 important warning signs.
Looking For More Investment Ideas Beyond Concentra Group Holdings Parent?
If you stop with Concentra Group Holdings Parent, you miss a wider opportunity set. Give yourself options by lining up a few more watchlist candidates now.
- Target potential upside in mispriced businesses by scanning the 29 high quality undervalued stocks that combine solid fundamentals with room for sentiment to catch up.
- Prioritise resilience by reviewing the 31 resilient stocks with low risk scores that focus on steadier earnings profiles and lower overall risk scores.
- Spot less crowded ideas early by working through the 20 high quality undiscovered gems that many investors have not yet focused on.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com