
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Strategy (MSTR) Could Be 13% Above Fair Value After Preferred Dividend Reset
Strategy Inc (MSTR) just reaffirmed a 12.00% annual dividend rate on its Variable Rate Series A Perpetual Stretch Preferred Stock, STRC, alongside fresh semi-monthly cash payouts tied to upcoming October and November record dates.
That preferred dividend decision lands during a volatile stretch for Strategy, with the share price down 6.79% over the last day to US$153.37, even as the 90 day share price return of 63.35% and a five-year total shareholder return of 111.17% point to strong longer-term momentum.
Scan income-focused ideas that echo Strategy's Stretch structure by reviewing the curated 8 dividend fortresses, which currently offers yields above 5% with an emphasis on resilience.
After a sharp one day pullback followed by a powerful 90 day rebound in Strategy stock, the question is simple. Does the current price still reward you for taking this mix of Bitcoin leverage and rich preferred payouts?
Most Popular Narrative: 13% Overvalued
Against a last close of $153.37, the most followed narrative pegs Strategy at a fair value of $136.00. This frames the current price as richer than that scenario implies and puts the focus on how tightly the whole story is tied to Bitcoin driven balance sheet moves.
Strategy relies on continued access to equity and credit markets, having raised US$17b of capital year to date 2026 and targeting ongoing issuance of both MSTR and digital credit. A tougher long term backdrop for risk assets or a credit cycle that is less supportive than management expects could limit the company’s ability to refinance or equitize its convertibles on attractive terms, increase interest expense and dividend burdens, and create headwinds for earnings and free cash flow.
See why 0 investors see Strategy as 13% overvalued.
Result: Fair Value of $136.00 (OVERVALUED)
Still, the whole Strategy story can shift quickly if Bitcoin liquidity weakens for a long stretch, or if Stretch preferreds trade below par and funding costs rise.
Find out about the key risks to this Strategy narrative.
Another View: Strategy Through the P/B Lens
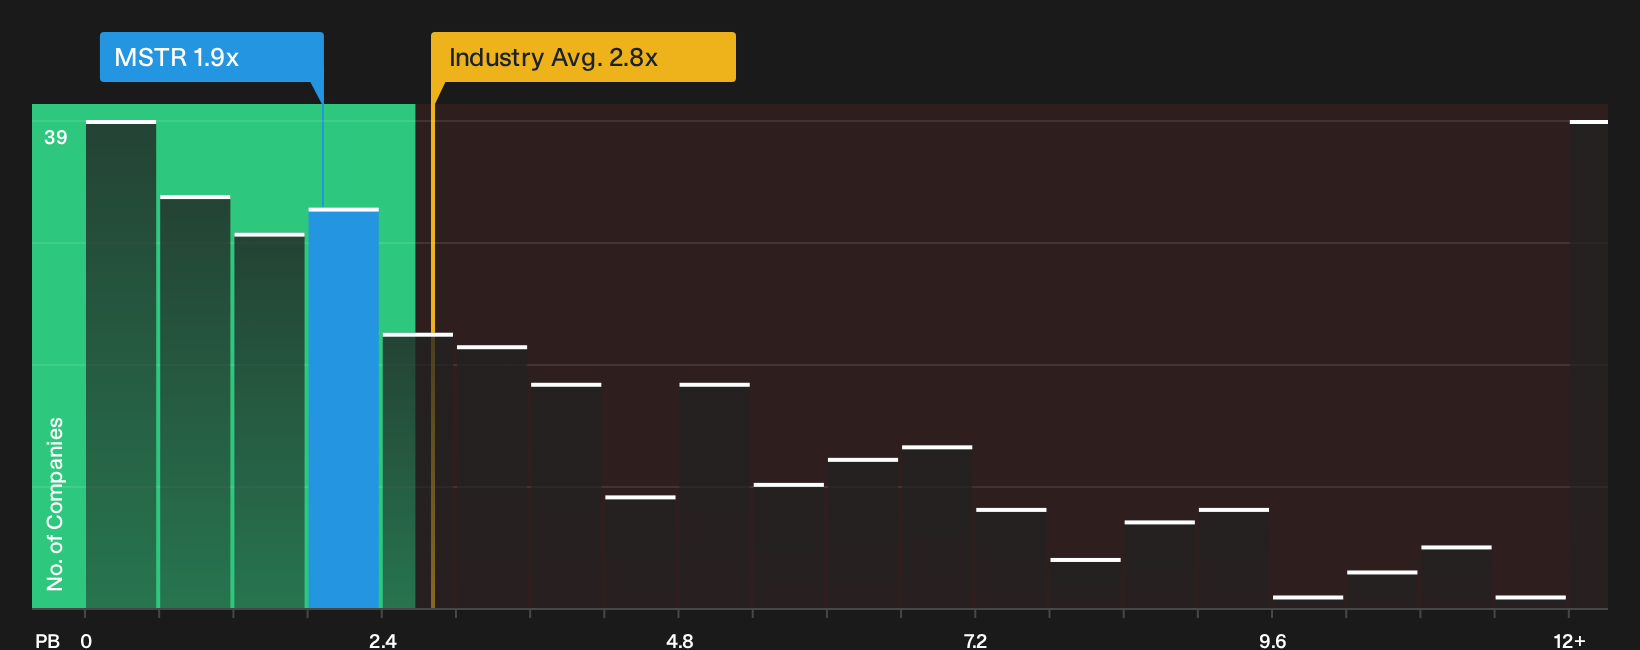
That fair value of $136.00 leans on analysts’ earnings assumptions. A different lens tells a softer story. On P/B of 1.9x, Strategy trades well below the US Software group at 2.8x and far under a peer average of 8.3x. This points to meaningful valuation risk if sentiment turns, but also leaves room for rerating if the bitcoin credit model holds up.
For readers who prefer simple ratio checks over complex cash flow models, the valuation breakdown based on this pricing gap can help you pressure test whether the current premium to the $136.00 fair value feels justified or stretched, especially given Strategy’s bitcoin heavy balance sheet and preferred funding stack, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages in the Strategy story today. Use the data, consider both sides, and move quickly to test your own thesis with the 1 key reward and 2 important warning signs.
Looking for more Strategy Inc investment ideas?
If you stop with Strategy Inc, you only see one angle. Broaden your watchlist with a few focused sets of stocks that match your income and risk preferences.
- Target resilient income by scanning dividend payers that aim for staying power through the 8 dividend fortresses.
- Hunt for mispriced quality and pressure test your valuation views using the curated 29 high quality undervalued stocks.
- Prioritise capital preservation and steadier fundamentals with a hand picked 31 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com