
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Why Veralto (VLTO) Is Back In The Spotlight
Why Veralto Stock Is Back On Investors’ Radar
Veralto (VLTO) has moved into focus after an analyst upgrade tied directly to rising earnings estimates and growing use of digital workflow and connected software solutions across its business.
Veralto’s share price has eased 0.8% over the past day to around $95.73. The 90-day share price return of 3.9% points to gradually improving momentum, even as the 1-year total shareholder return, which includes dividends, is down 7.4% and the 3-year total shareholder return remains positive at 30.3%.
Scan the market for other companies that combine earnings momentum with recurring software revenue by checking out our hand picked 29 high quality undervalued stocks alongside Veralto.
Veralto has already rewarded longer term holders, yet the recent upgrade and earnings reset suggest the debate now shifts. Is most of the easy move behind the stock, or does the current valuation still leave clear upside on the table?
Most Popular Narrative: 15.1% Undervalued
Veralto’s most followed valuation narrative puts fair value at about $112.76, compared with the latest close near $95.73. That gap rests on a view that recurring software revenue, water exposure and capital allocation can support higher earnings power over time.
Increased adoption of digital workflow and connected software solutions (notably in PQI and Water Quality) is supporting high-margin, recurring revenue streams (now 61% of total sales), improving business predictability and supporting higher net margins and EPS growth.
See why 14 investors see Veralto as 15% undervalued.
Result: Fair Value of $112.76 (UNDERVALUED)
Still, Veralto’s story can change quickly if weakness in China’s Water Quality segment persists, or if rising input costs and integration spending squeeze margins more than expected.
Find out about the key risks to this Veralto narrative.
Another View On Veralto’s Valuation
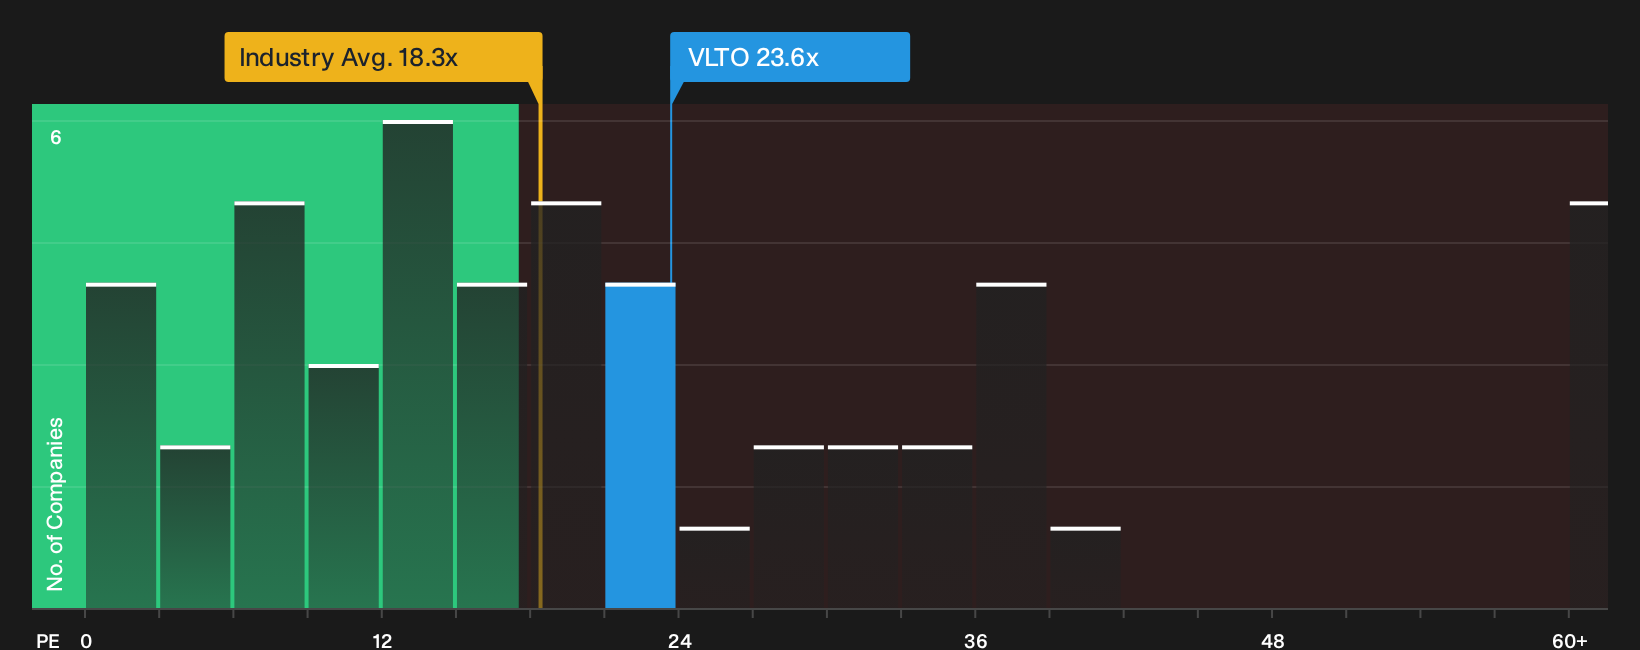
On the flip side, Veralto’s current P/E of 23.6x sits above the US Commercial Services industry at 18.3x and also above its own fair ratio of 21.2x. That points to some valuation risk if the share price drifts back toward that fair ratio benchmark.
For a closer look at how this pricing stacks up against peers and what the fair ratio implies for future moves, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals around Veralto’s valuation and business momentum make this a good moment to look under the hood yourself and consider acting before sentiment shifts again, starting with the balance between 3 key rewards and 1 important warning sign
Looking For More Ideas Beyond Veralto?
If Veralto has you thinking harder about where to put fresh capital, do not stop at a single opportunity. Cast the net wider and give yourself more options across quality, value, and resilience.
- Target resilient compounding by scanning a 8 dividend fortresses that may appeal if you want income potential backed by sturdier balance sheets and cash flows.
- Hunt for mispriced opportunities by reviewing a focused 20 high quality undiscovered gems that could reveal lesser known businesses with stronger fundamentals than their valuations suggest.
- Guard your downside by filtering a 31 resilient stocks with low risk scores that aims to highlight companies with sturdier financial profiles and lower overall risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com