
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
What Acadia Pharmaceuticals (ACAD)'s Phase 2 Readout Means For Shareholders
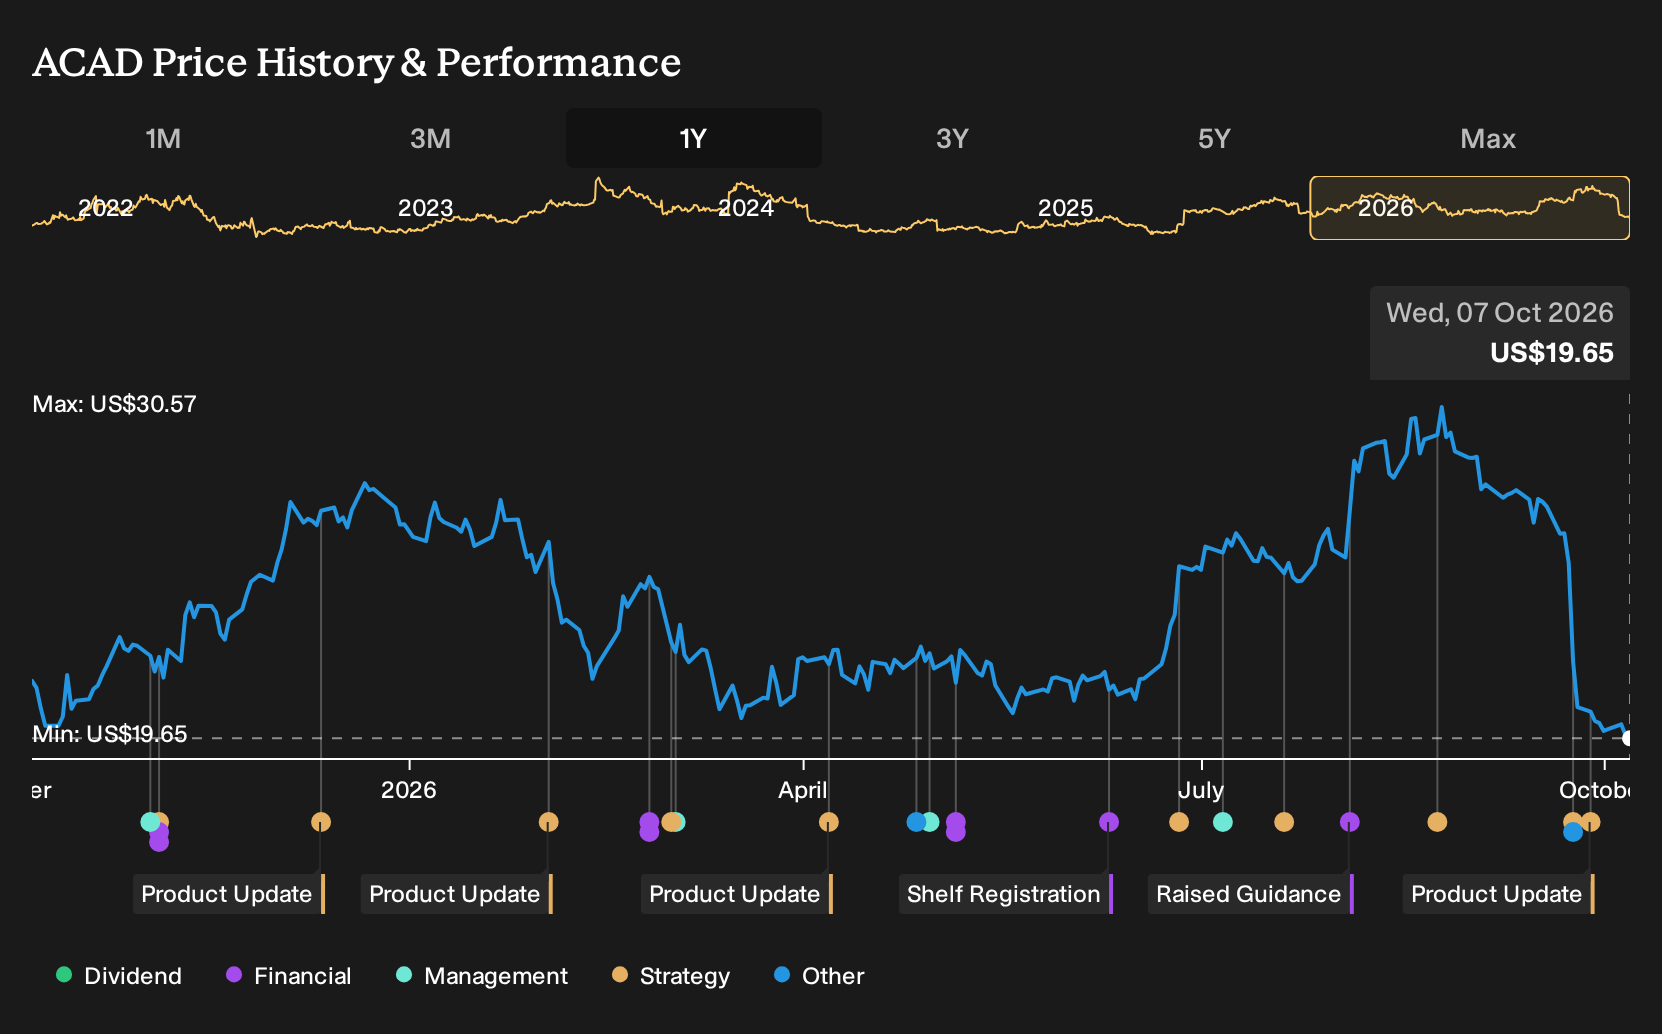
- Acadia Pharmaceuticals reported past Phase 2 RADIANT topline data for remlifanserin in Alzheimer’s disease psychosis and received a USPTO Notice of Allowance for a Rett syndrome dosing patent on trofinetide, which is expected to extend U.S. protection for DAYBUE formulations to March 28, 2041.
- The combination of a potentially longer DAYBUE patent runway and a Phase 3 enabling remlifanserin dataset directly affects how durable Acadia Pharmaceuticals’ current franchises and late stage pipeline may appear to investors.
- We will look at how Acadia Pharmaceuticals’ investment narrative lines up with extended DAYBUE patent coverage after the remlifanserin readout.
Acadia Pharmaceuticals Investment Narrative Recap
To own Acadia Pharmaceuticals, you need to believe DAYBUE and NUPLAZID can support the current business while the broader neurology pipeline creates new treatment areas over time. The immediate operating focus is keeping Rett and Parkinson’s psychosis demand steady as trofinetide launches outside the U.S. and R&D is trimmed but not starved.
Right now the key near term swing factor is confidence in remlifanserin after a mixed Phase 2 RADIANT readout, with analysts already cutting implied success odds. The biggest risk is that sentiment around dementia related psychosis continues to weaken, leaving the pipeline contribution to future earnings looking far lower.
The patent Notice of Allowance for trofinetide weight banded dosing is the announcement that matters most here. It potentially extends U.S. protection on DAYBUE formulations to March 28, 2041, on top of the existing Rett syndrome method of use patent that runs to July 2036. This shapes how durable that cash flow stream might be.
For investors, longer U.S. coverage for DAYBUE changes how DAYBUE, NUPLAZID and remlifanserin stack together as a portfolio of neurological assets. It gives Acadia Pharmaceuticals more time to work through Phase 3 execution on remlifanserin and the rest of the pipeline, while keeping attention on real risks around long term pricing, treatment persistence and competition.
What The Current Forecasts Assume For Acadia Pharmaceuticals
Acadia Pharmaceuticals' analyst narrative points to revenue of US$1.7b and earnings of US$328.0 million by 2029. That set of estimates rests on 13.4% yearly revenue growth and an earnings decline of US$52.5 million from US$380.5 million today.
Uncover why Acadia Pharmaceuticals' fair value indicates a 64% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
One alternate view focuses on DAYBUE rather than remlifanserin. Bullish analysts were already assuming faster global uptake and saw room for revenue near US$1.9b and earnings of about US$575.3 million by 2029. That is far more optimistic than consensus, and this new Acadia Pharmaceuticals patent news could push those opinions even further apart.
Explore 5 other Acadia Pharmaceuticals fair value estimates, including one that suggests potential upside of as much as 360% from the current price.
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Acadia Pharmaceuticals research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Acadia Pharmaceuticals. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Acadia Pharmaceuticals' overall financial health at a glance.
Looking For More Investment Ideas Beyond Acadia Pharmaceuticals?
Once you have a view on Acadia Pharmaceuticals, it can help to widen the lens and compare it with other companies that match your risk profile and goals. The Simply Wall St Screener lets you filter for traits like balance sheet strength, dividend income, or underappreciated quality so you can build a watchlist that actually fits how you want to invest.
- If capital preservation and lower volatility matter most to you, start with a focused group of 31 resilient stocks with low risk scores that score well on resilience and stability metrics.
- For those hunting for mispriced quality, narrow your search to our curated 29 high quality undervalued stocks that combine stronger fundamentals with what may be discounted valuations.
- Income oriented investors can zero in on yield by scanning a targeted 7 dividend fortresses that couples higher payouts with an emphasis on durability.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com