
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Atlas Energy Solutions (AESI) Could Be 31% Undervalued As AI Power Deals Draw Attention
Why Atlas Energy Solutions Is Back On Investors’ Radar
Atlas Energy Solutions (AESI) drew fresh attention after its ProjectCo unit agreed to buy 283 MW of Caterpillar natural gas generation equipment, supported by a cost reimbursement deal with a leading frontier AI lab as offtaker.
Those commitments build on Atlas existing Global Framework Agreement with Caterpillar and tie directly into power needs for data centers, which places the stock firmly in the discussion around energy infrastructure for AI workloads.
Atlas Energy Solutions has seen mixed momentum, with the share price down 7.43% over the past 30 days and 12.32% over 90 days, yet still showing a 28.19% year to date share price return and a 7.41% one year total shareholder return, as investors weigh recent power agreements against a longer three year total shareholder return decline of 33.26%.
Spot 92 AI infrastructure stocks that, like Atlas Energy Solutions, are being pulled into the surge in power demand from data center and AI customers.Atlas Energy Solutions now has AI linked power orders, a falling three year return and a recent pullback on the screen. Does that mix still skew the risk reward toward buyers at today’s price once valuation is unpacked?
Most Popular Narrative: 31% Undervalued
Atlas Energy Solutions most followed valuation storyline points to a fair value of $18.00 compared with the last close at $12.46. This narrative places significant emphasis on how the emerging power arm scales alongside the legacy sand and logistics business.
The launch of Atlas' Power business following the Moser Energy Systems acquisition is now being advanced through a 120 MW behind the meter power purchase agreement in Socorro, Texas and a growing pipeline of Caterpillar backed generation equipment. Together, these elements can create a second long dated revenue stream with contracted visibility and potential support for net margins once projects are online.
See why 35 investors see Atlas Energy Solutions as 31% undervalued.
Result: Fair Value of $18.00 (UNDERVALUED)
Still, Atlas Energy Solutions has real execution risk if heavy growth capex in power fails to attract long duration AI contracts, or if weaker Permian completion activity keeps sand volumes under pressure.
Find out about the key risks to this Atlas Energy Solutions narrative.
Another View On Atlas Energy Solutions’ Valuation
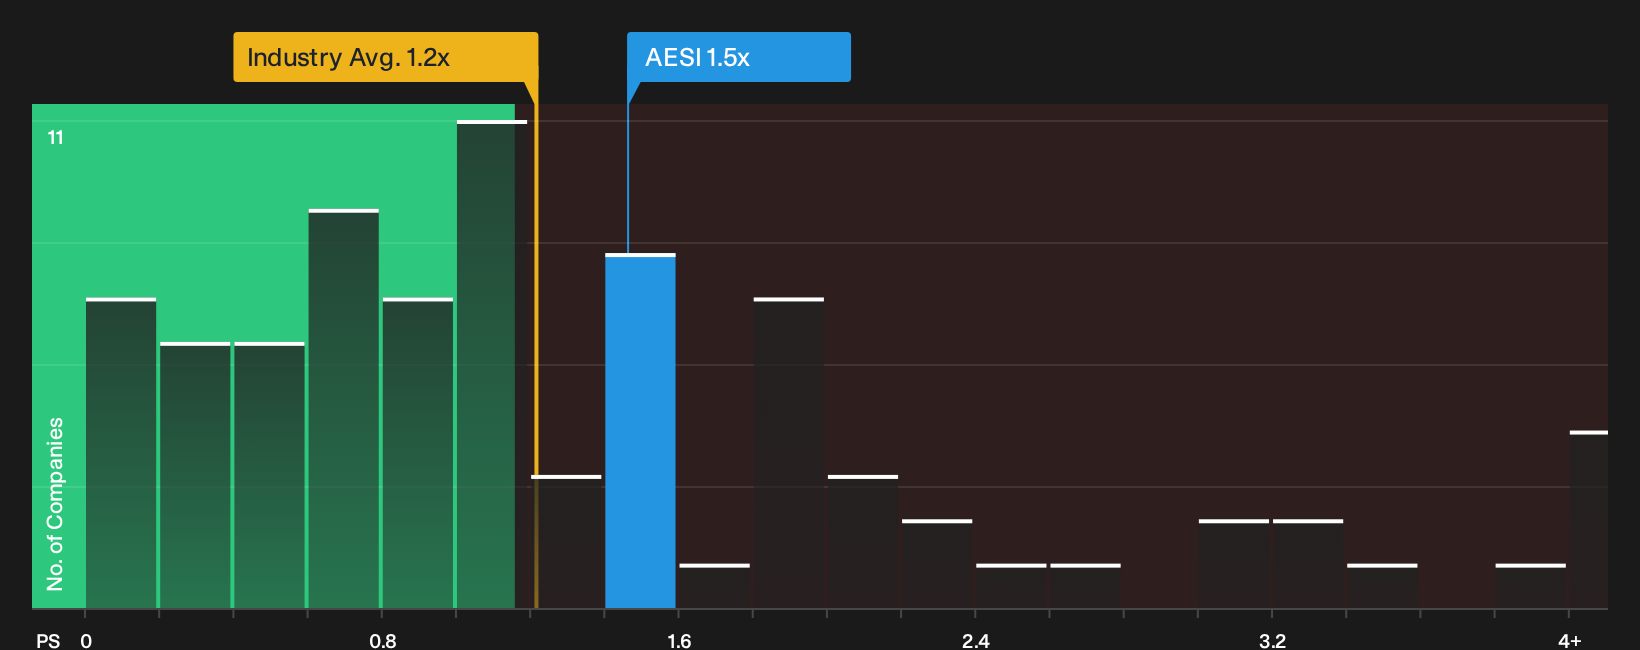
Atlas Energy Solutions looks inexpensive against the $18.00 fair value narrative, yet the current P/S of 1.5x is higher than the US Energy Services industry at 1.2x and above a fair ratio of 0.8x. That gap points to real downside risk if sentiment shifts back toward those lower multiples.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If the mixed messages around Atlas Energy Solutions leave you unsure, move quickly to review the underlying figures and compare the narrative with your own return expectations, starting with 1 important warning sign.
Looking For More Atlas Energy Solutions Style Ideas?
Do not stop at Atlas Energy Solutions. Use this pullback as a chance to refresh your watchlist with new ideas that match your risk and return preferences.
- Target potential mispricing by scanning for companies that combine strong fundamentals with appealing valuations through the 29 high quality undervalued stocks.
- Build a steadier income stream by focusing on businesses offering higher yields and robust payout profiles using the 7 dividend fortresses.
- Sleep easier at night by concentrating on resilient businesses with cleaner balance sheets via the 31 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com