
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Walmart (WMT) Expands Digital Profit Engines, Is The Stock Fully Priced?
Walmart (WMT) has quietly turned its digital arm into a profit engine, with Walmart Connect advertising and e-commerce activity supporting margin expansion as automation, store fulfillment and new media partnerships pull more business into higher margin channels.
The recent focus on Walmart Connect and e-commerce comes as the 1-year total shareholder return sits at 4.71%, while the share price has eased about 5.2% over 90 days. This hints that short-term momentum has cooled, even as the 3-year total shareholder return of around 111% points to a much stronger longer-run story.
Scan how Walmart’s digital push compares with other retailers leaning on tech, automation and media by reviewing our curated list of 27 high quality undervalued stocks.
Recent gains have cooled while Walmart’s digital profit pools keep expanding. That mix sets up a simple test for the valuation work next. Does the current price still compensate you for the digital upside and retail grind?
Most Popular Narrative: 31% Undervalued
According to the most followed Walmart narrative, the fair value sits at $154.58 versus a last close of $107.20. This points to a sizeable valuation gap that hinges on how much weight you place on its newer profit engines.
Walmart’s “Other” SBU is poised for continued success, leveraging innovation and agility to capture new market share. While risks exist, the segment’s performance and strategic initiatives suggest a promising outlook. Investors and stakeholders should watch for further developments in digital integration and specialty category expansion as key drivers of future growth.
See why 59 investors see Walmart as 31% undervalued.
Result: Fair Value of $154.58 (UNDERVALUED)
Still, the story can break if Walmart’s digital momentum slows, or if the “Other” segment stumbles on execution and competitive pressure in newer categories.
Find out about the key risks to this Walmart narrative.
Another View on Walmart’s Valuation
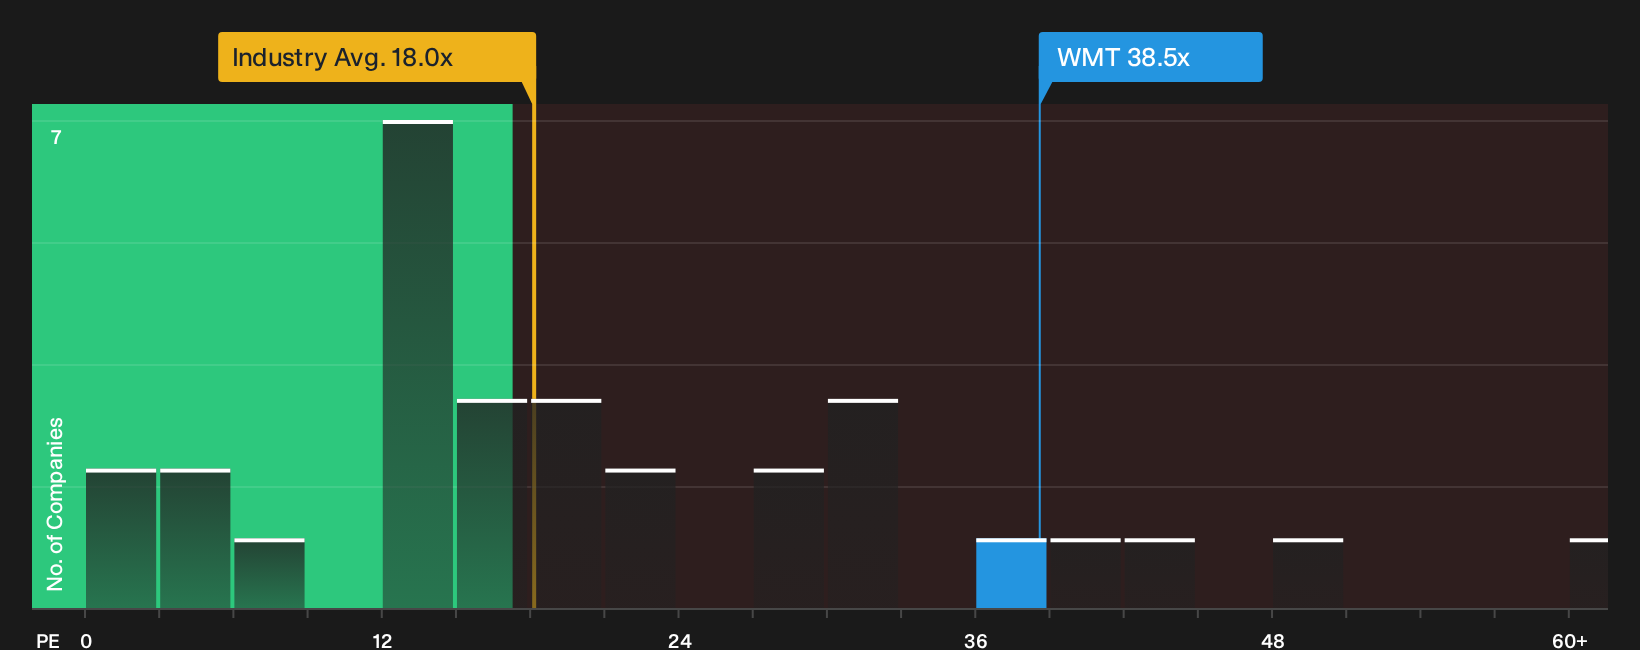
A different lens tells a cooler story. On earnings, Walmart trades at a P/E of 38.5x, which is much richer than both the US consumer retailing industry at 18x and its peer group at 22.6x. It also runs above its own fair ratio of 33.5x, which points to a valuation that already bakes in a lot of optimism. How comfortable are you paying that kind of premium for the future that the narrative assumes?
See what the numbers say about this price in the fuller valuation breakdown, then decide how much weight to give this richer P/E picture versus the fair value story from the narrative. See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Comfortable with the bullish tone so far, or slightly skeptical about how much optimism is already in Walmart’s price? Move quickly to stress test the positives and see the 2 key rewards.
Looking for more investment ideas beyond Walmart?
If Walmart’s story has your attention, widen your opportunity set now, because staying focused on a single retailer can mean missing out on other compelling setups.
- Target reliable cash generators by scanning companies with resilient payouts and income potential using the 8 dividend fortresses.
- Hunt for quality at a discount by checking the 19 high quality undiscovered gems that pair strong fundamentals with limited market attention.
- Prioritize resilience over drama by reviewing a 31 resilient stocks with low risk scores that spotlights businesses with steadier risk profiles and sturdier financial footing.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com