
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
3 Financial Stocks Retail Investors Are Watching As Higher Long Term Rates Hold
Higher long term interest rates are unsettling plenty of stocks, yet they can also reshuffle winners in the financial sector. If central banks stay firmly focused on inflation and bond yields remain elevated, some insurers and asset managers with exposure to life policies, annuities and short duration fixed income could see their business mix change in important ways. This article walks through three such stocks from our screener and explains how the recent IMF warnings and bond market turmoil might matter for each one.
These three examples are only a sample, and the full screen surfaced 28 more financial firms with equally interesting yield stories and business narratives that are not covered below. To see the wider field and start sorting for your own highest conviction ideas, head straight into the Beneficiaries of Higher Long-Term Interest Rates (Yield-Sensitive Financials) screener
Apollo Global Management (APO)
Apollo Global Management sits near the center of this higher long term yield theme because its credit engine and retirement platform both lean heavily on bond income, spreads and long dated commitments that can look more attractive when policy rates stay firm.
Apollo Global Management runs a broad alternatives platform spanning private equity, real assets and large credit and retirement businesses that sit squarely in the higher yield, long duration income theme. Recent revenue shows about US$6.5b from Asset Management, US$1.4b from Principal Investing and roughly US$25.9b from Retirement Services, with the stock valued around US$68.1b by market cap.
"Apollo's inclusion in the S&P 500 is expected to broaden its shareholder base, leading to potential growth in public market exposure and thus possibly driving future revenue increases."
How any single pressure on long duration credit returns might shift will be important for how that story translates into margins.
If that pressure point matters to your thesis, read the full narrative for Apollo Global Management to see how Apollo Global Management’s model could be accelerating or stalling under stickier yields.

Banco BTG Pactual (BOVESPA:BPAC11)
Banco BTG Pactual plugs neatly into this higher long term rate theme because its investment, credit and insurance activities all lean on earning a spread on client cash, with a large R$45.7b investment banking arm and a roughly R$378.4b market value that keeps it firmly in big bank territory.
Banco BTG Pactual combines investment banking, credit, wealth and insurance related services, so higher long term yields directly affect how it prices savings products, manages client float and competes for investors who want more income.
"Accelerating digital adoption and the bank's ongoing investment in its digital platform are driving lower cost-to-serve and supporting expansion into new client segments, which should further boost topline revenue growth and steadily improve net margins."
What really matters now is how one quiet shift in its funding mix shapes those margin gains if higher yields stick around.
That quiet shift could be the real story, and the full narrative for Banco BTG Pactual explains how Banco BTG Pactual’s digital engine and funding mix might be accelerating or masking risk.

Alerus Financial (ALRS)
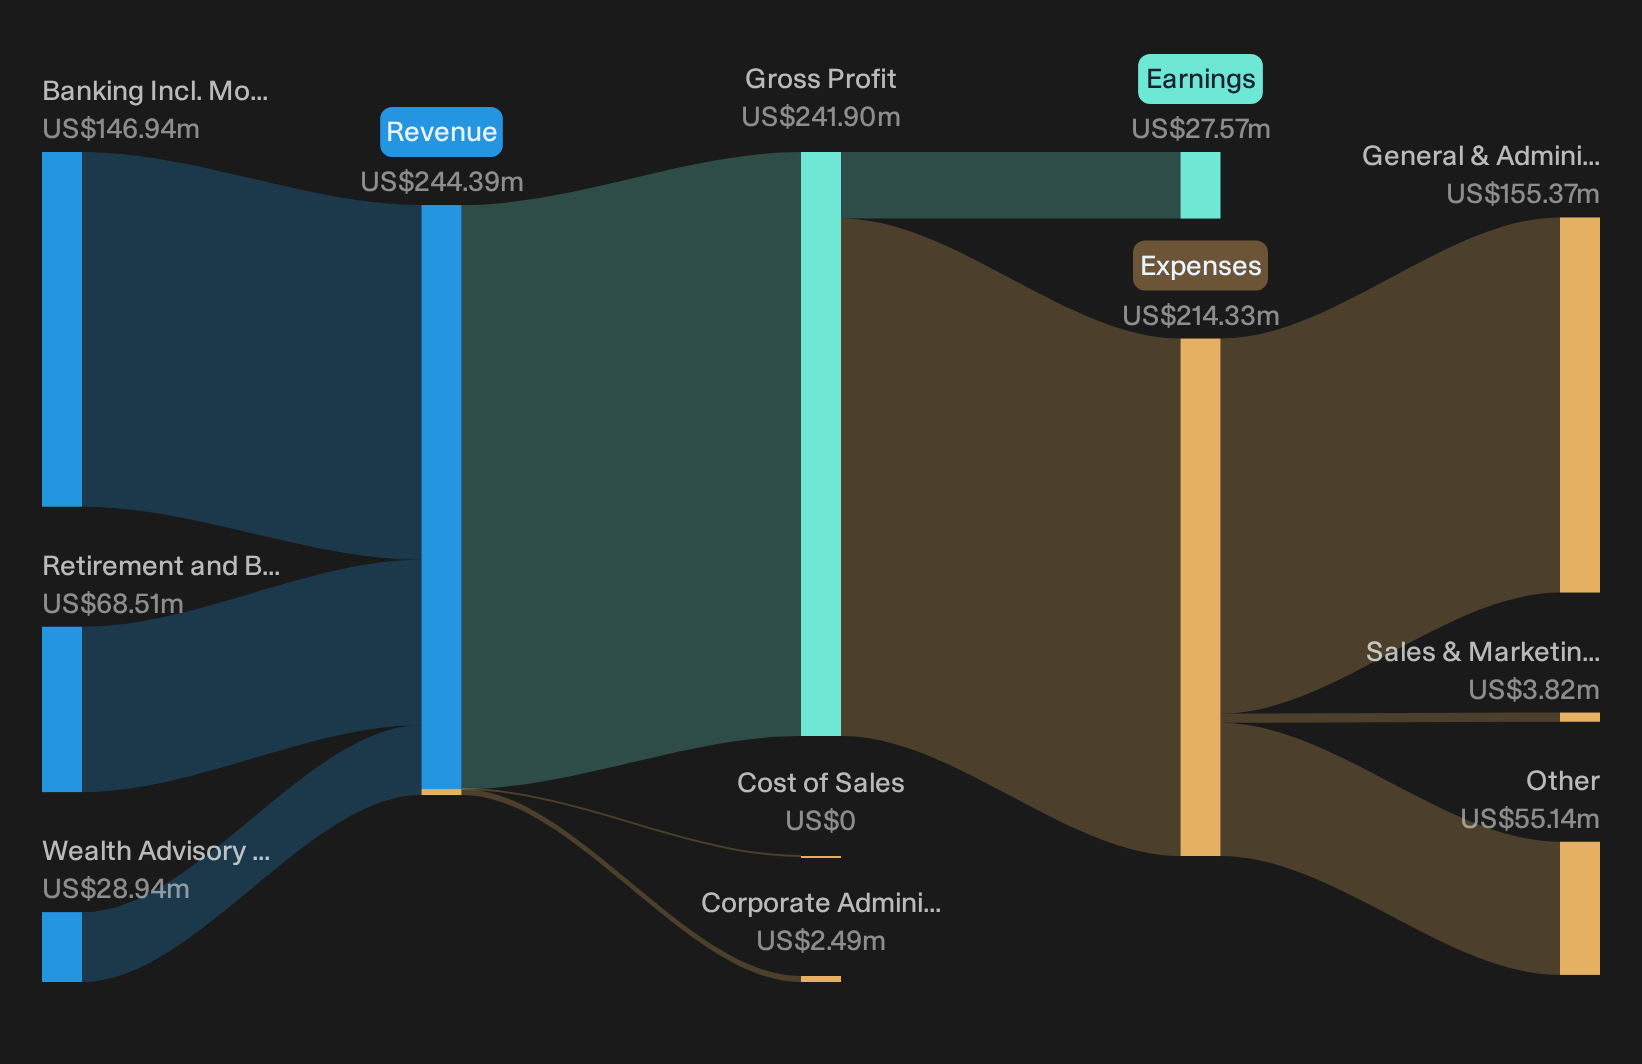
Alerus Financial blends a traditional regional bank with sizeable retirement and wealth services. This mix fits the higher long term yield theme because net interest income and cash on deposit can earn more when rates stay firm. Banking including mortgage brings in about $147 million of revenue, retirement and benefit services about $69 million, and wealth advisory around $29 million, with the stock valued near $807 million by market cap.
Alerus Financial ties directly into this yield sensitive screener because the bank’s lending book and retirement float both can earn more when central banks keep policy tight and bond markets price in higher long term yields. A roughly 2.72% dividend, a sizeable fee income base, and forecasts for strong earnings growth provide rate focused investors with a mix of income and potential upside, depending on how one unseen pressure on long term funding costs develops.
That unseen pressure on long term funding costs could be crucial, so review the Alerus Financial financial health report to see what the market might be missing.
Seeking Fresh Alternatives Before They Fly
Momentum can move fast, and the cleanest breakout ideas often get caught once the crowd piles in. Scan these fresh, under the radar lists while it matters and consider acting while they are still developing.
- Spot income workhorses built to keep paying by reviewing the 8 dividend fortresses and identifying which payouts still look supported while the yield story is in your favor.
- Track developments in AI infrastructure demand through the 91 AI infrastructure stocks and see which enablers could be positioned to participate in trends in compute, data center and networking activity.
- Explore potential beta drivers for your portfolio with the 19 high quality undiscovered gems and review under followed companies before attention and liquidity increase.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com