
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
SK Hynix (NasdaqGS:SKHY) Stock Looks Like A Bargain On Its 9% Rise
SK hynix has logged an 8.7% gain year to date, and with the share price now reflecting a mix of AI-related demand expectations and corporate structure questions, the real issue is how well its earnings underpin that move.
- The year to date rise of 8.7% puts real weight on whether SK hynix's current earnings profile can carry the price investors are paying today.
- Fresh headlines around a possible US IPO of subsidiary Solidigm highlight ownership complexity that can influence how investors weigh SK hynix's future profit stream and capital needs.
- The analysts covering SK hynix have run their own numbers. See what analysts think SK hynix's shares could be worth.
For investors, the debate is whether the current SK hynix share price is justified by the earnings it is generating relative to the industry average.
To see how this earnings question plays out across similar AI exposed chipmakers, compare SK hynix against a wider set of 91 AI infrastructure stocks.
Is SK hynix Still Cheap on Earnings?
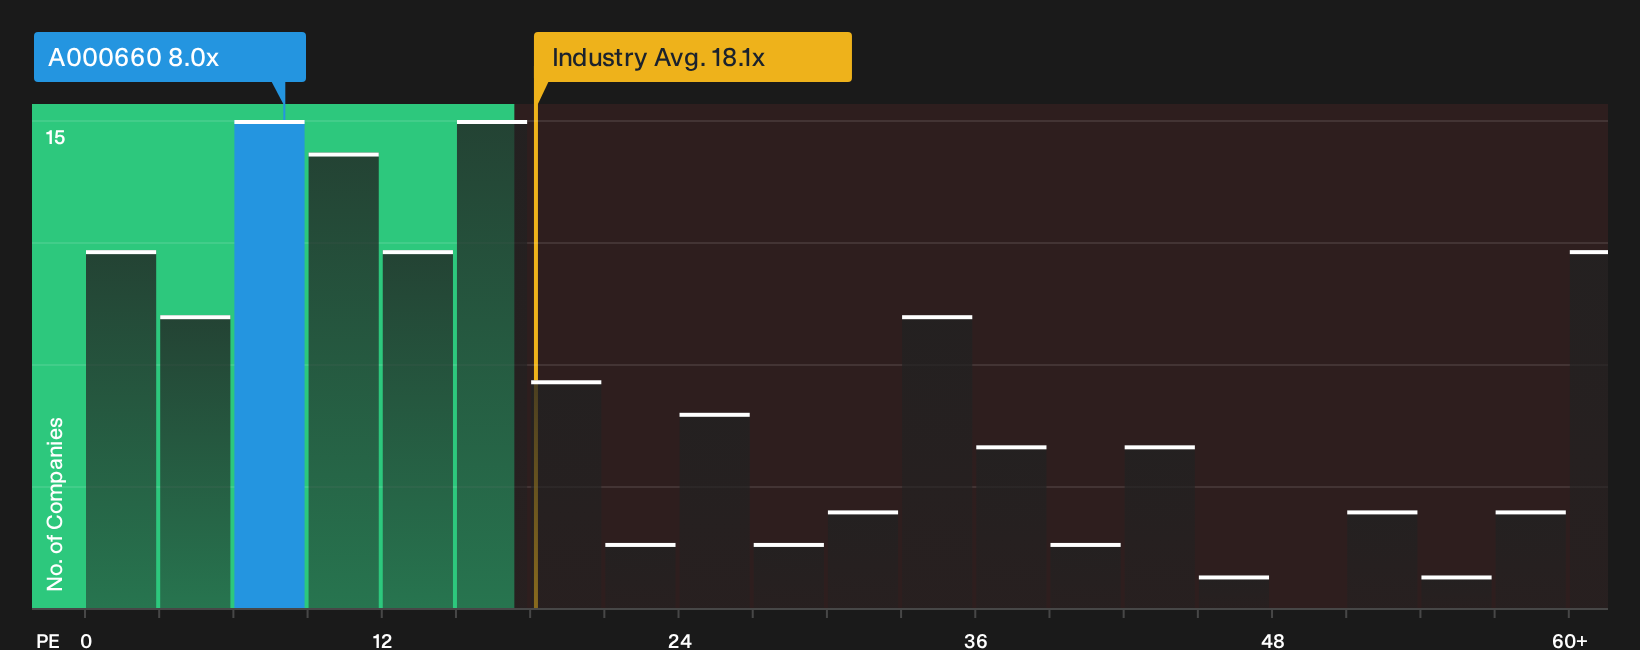
The P/E ratio suits SK hynix because the current debate is really about how much investors are paying for each unit of earnings tied to AI memory demand. On this metric, SK hynix trades at about 8.0x earnings, which is far below the semiconductor sector average of roughly 53.3x. That gap signals the market is pricing the stock at a steep discount to what is being paid for profits across the wider chip industry.
Compared with a broader peer set on roughly 63.7x, SK hynix appears even more heavily undervalued on P/E. Because the recent Solidigm IPO headlines have raised questions about the corporate structure rather than the income line, the low multiple indicates that those governance concerns are weighing on the share price more than the current earnings base. For investors, the key question is whether that discount compensates enough for the added complexity in the story. Explore the numbers behind SK hynix's P/E valuation.
The SK hynix Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the SK hynix P/E puzzle leaves off by spelling out which future paths for growth, profitability and earnings would need to be true for the stock to look meaningfully higher or lower than today's quote. Each scenario links its number to a clear view on where SK hynix's expansion prospects, margin profile and key risks could head, giving you something concrete to revisit as fresh information comes through.
A written, number-driven view on SK hynix helps you pin down what would need to happen around Solidigm's potential US listing and AI memory demand for today's valuation to look reasonable over time. It gives you a clear set of assumptions to revisit as chip supply plans from buyers like AMD evolve and fresh data points on governance, capital needs and profitability come through.
Share your own Narrative for SK hynix and set out the assumptions behind your valuation.
One more angle on SK hynix that could change the picture
Valuation only tells part of the story for SK hynix, because separate checks have highlighted specific business risks that investors may want to weigh before feeling comfortable with the current setup. Take a closer look at 2 warning signs (2 major) before settling on a valuation.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com