
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Jabil (JBL) Gets A Valuation Check After Strong Results And Fresh Guidance
Jabil (JBL) is back in focus after reporting fourth quarter and full year results on 30 September 2026, alongside fresh guidance for the first quarter and full fiscal 2027.
Jabil’s share price has been choppy in recent weeks, with the stock dipping over the past quarter but still delivering a 28.6% year to date share price return and a 52.8% total shareholder return over the past year. This signals momentum that investors are still willing to pay attention to after this earnings and guidance update.
Scan how Jabil’s earnings story compares with other manufacturing and tech-focused contractors by reviewing our curated list of 90 robotics and automation stocks in similar supply chain and automation niches.
The recent climb to $309.19 after mixed short term moves leaves a simple puzzle. Are investors reacting to Jabil’s stronger reported results, or focusing more on changing sentiment as the valuation case is re rated next?
Most Popular Narrative: 28% Undervalued
Against Jabil’s last close at $309.19, the most followed narrative points to a fair value near $430, implying a wide valuation gap built on specific growth and margin assumptions rather than sentiment alone.
The expansion in India, particularly in Gujarat, to support photonics capabilities indicates growth potential in a promising market, likely enhancing future revenues from domestic demand and infrastructure projects. Jabil's acquisition of Pharmaceutics International, Inc. opens access to a $20 billion market, suggesting potential revenue growth and improved margins by expanding its pharmaceutical solutions offering.
See why 36 investors see Jabil as 28% undervalued.
Result: Fair Value of $429.56 (UNDERVALUED)
Still, the earnings story can quickly look different if tariff policy shifts hit demand or if segment weakness in EV and renewable customers lasts longer than expected.
Find out about the key risks to this Jabil narrative.
Another View On Jabil’s Valuation
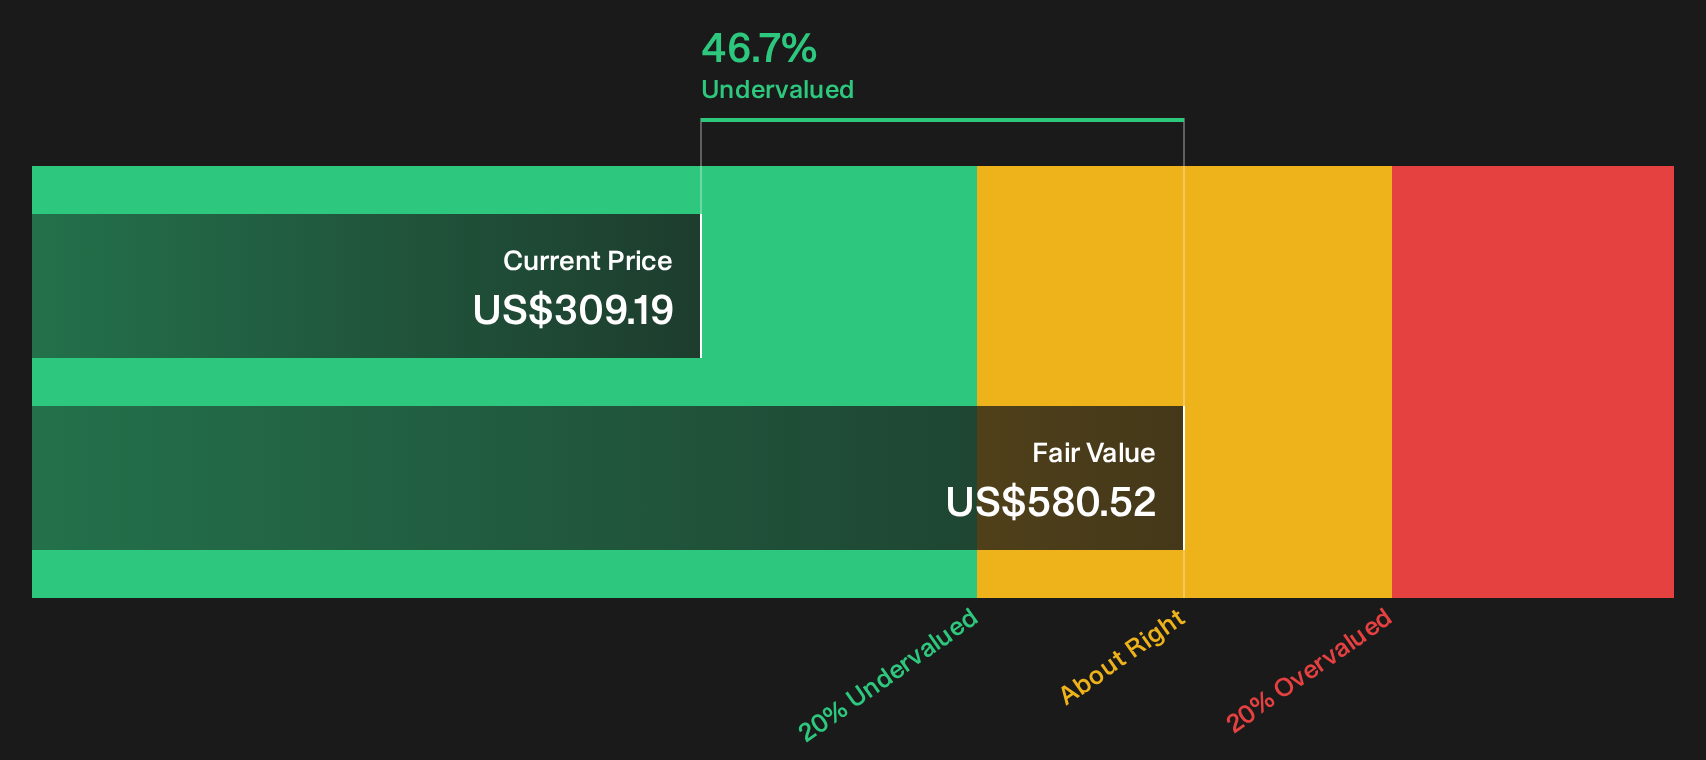
Jabil screens as good value on the SWS fair value work, trading about 46.7% below an estimated worth of $580.53 based on our DCF model. That points to an undervalued stock on cash flow assumptions, so which story do you trust more, the earnings based target or the cash flow one?
For a closer look at how those cash flows are treated over time, including the assumptions built into growth, margins and discount rates, review the SWS DCF model in detail here Look into how the SWS DCF model arrives at its fair value.
Next Steps
If this mix of optimism and caution around Jabil leaves you on the fence, act quickly to review the numbers and sentiment for yourself using the detailed breakdown of 4 key rewards and 1 important warning sign
Looking for more Jabil style investment ideas?
If Jabil’s story has you thinking about what else might be hiding in plain sight, use the Simply Wall St screener to spot other potential opportunities before they move.
- Target resilient balance sheets and stronger fundamentals by running the list of solid balance sheet and fundamentals (25 results) to filter for companies built to handle tougher conditions.
- Hunt for quality trading below estimated worth through the 27 high quality undervalued stocks and see which businesses could be mispriced today.
- Prioritise stability and lower volatility profiles by scanning the 31 resilient stocks with low risk scores so you do not miss companies that fit a steadier approach.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com