
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Allient (ALNT) Stock Still Looks Rich Following Its 298% Run
Allient has been on a powerful run, and the share price now reflects a long stretch of strong returns. For investors, the obvious question is whether that current US$118.63 price tag lines up with what the business is actually earning.
- Allient has returned 298.2% over the past 3 years, which puts a lot of weight on the idea that its earnings can support a much higher valuation than in the past.
- The company’s investment story increasingly hinges on how effectively it can turn its revenue base into consistent profit and cash generation, since that is what ultimately anchors any earnings based valuation.
- There is a second opinion on Allient worth weighing. See what analysts think Allient's shares could be worth.
The issue now is whether Allient’s current earnings profile is strong enough to justify where the stock trades today.
If you want to cross check whether Allient’s earnings based valuation question shows up elsewhere, compare it against a wider set of companies using the 27 high quality undervalued stocks
Is Allient Getting Expensive on Earnings?
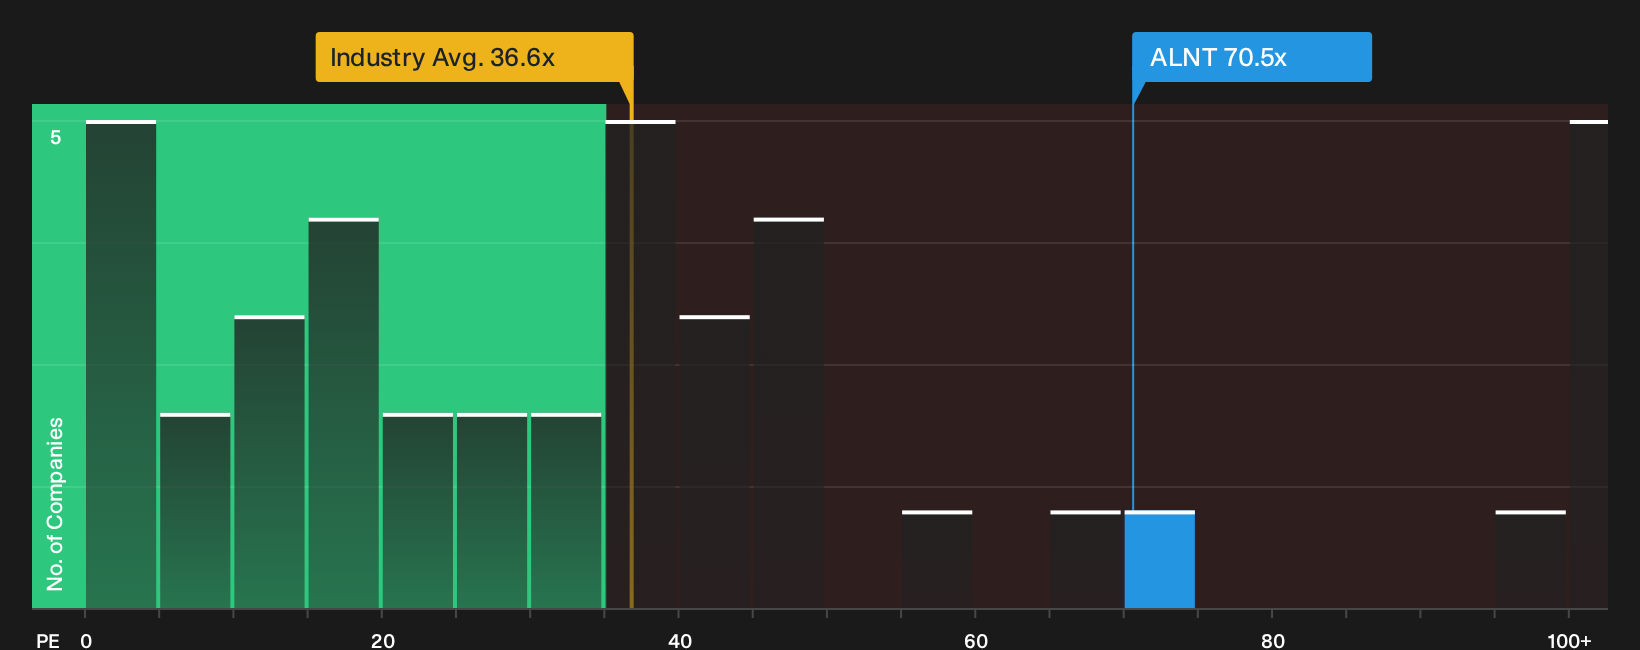
The P/E ratio suits Allient because earnings are central to how investors are judging the business right now. On this measure, the stock trades on a P/E of 70.5x, which is well above both the Electrical industry average of 36.6x and the peer group at 26.4x. That kind of gap implies buyers are willing to pay a much higher price for each dollar of recent profit than they do for similar companies.
The Fair Ratio, which reflects what you might expect given Allient’s own growth profile, margins, size and risk, comes in meaningfully lower than the current market multiple. That leaves the shares looking overvalued on this earnings yardstick and puts more pressure on the business to keep converting its revenue base into durable profit to support that higher bar. For anyone considering Allient today, the key question is whether its earnings quality and runway truly justify paying such a premium multiple compared with peers and the tailored benchmark. Explore the numbers behind Allient's P/E valuation.
The Allient Narrative: What Would Justify Today's Price?
Simply Wall St Narratives take the valuation puzzle around Allient and explain what future revenue growth, profitability and earnings power would need to look like for the stock to be worth materially more or less than today’s price, and they sit on the platform’s Community page. Each narrative treats Allient’s fair value as a specific thesis about how the business might develop over time so you can watch how that idea holds up as new information arrives.
Bullish holders of Allient see much more upside in the automation and defense story than the more cautious crowd focused on execution risks.
Bull case: 9% undervalued
"Allient's strategic positioning at the forefront of industrial automation and digitalization supported by proprietary motion control and electromechanical systems positions it to outsized gains..."
Discover why this Narrative puts Allient at 9% undervalued.
Bear case: roughly fairly valued
"Expectations for continued acceleration in industrial automation, robotics, and data center infrastructure could be overestimating future revenue growth..."
Explore why this Narrative puts Allient at roughly fairly valued.
One more Allient clue worth checking before you move on
There is a separate lens on Allient that sits outside this earnings discussion, where professional forecasts map out what the business might look like a few years from now and give you a different benchmark to compare with today. Explore where analysts expect Allient to be in a few years.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com