
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
City Holding (CHCO), Why Is Its Latest Update Drawing Attention?
City Holding (CHCO) has increased its quarterly dividend to US$1.00 per share, a 15% rise from the previous US$0.87 payout, placing a clear emphasis on shareholder income.
At a share price of US$141.30, City Holding has seen short term share price momentum cool slightly over the past month, even as the 90 day share price return of 7.9% and 1 year total shareholder return of 18.46% point to firmer longer term strength. The dividend hike and recent board appointments are likely reinforcing investor confidence rather than resetting the story.
Capture how City Holding's dividend move fits into the broader hunt for income by scanning our hand picked 8 dividend fortresses that share a similar focus on shareholder payouts.After a 15% dividend lift and a share price near US$141, City Holding now trades only slightly below one set of analyst estimates, but at a much steeper discount to intrinsic value models. Which reference point deserves more weight?
Preferred P/E of 15.2x: Is it justified?
City Holding screens as fully priced on earnings at a P/E of 15.2x when set against US bank peers, even though the SWS DCF output and analyst target suggest different anchors for value.
The P/E ratio compares the current share price to earnings per share, so in plain English it shows how many dollars investors are paying for each dollar of profit. For a regional bank like City Holding, that figure often reflects views on earnings stability, credit risk, and how sustainable current profitability looks.
Here, the stock trades at a P/E of 15.2x while the US Banks industry sits at 11.5x, which points to a clear premium rather than a small tweak in expectations. Against the SWS fair P/E of 10.4x, the market is placing an even heavier price on each dollar of earnings. This is a level the share price could move towards if sentiment changed or if results were closer to existing expectations.
Explore the SWS fair ratio for City Holding.
Result: Price-to-earnings of 15.2x (OVERVALUED)
Still, City Holding faces clear pressure points if earnings growth stalls or credit conditions tighten, which could quickly challenge a premium P/E and the richer dividend story.
Find out about the key risks to this City Holding narrative.
Another View on City Holding's Value
The earnings multiple paints City Holding as expensive, yet the SWS DCF model points the other way. At a share price of US$141.30, the stock is described as trading about 34.9% below an estimated fair value of US$216.96. That gap frames the P/E premium as a potential opportunity rather than just a warning sign. Which reference point do you trust more when income and valuation pull in different directions?
Look into how the SWS DCF model arrives at its fair value.
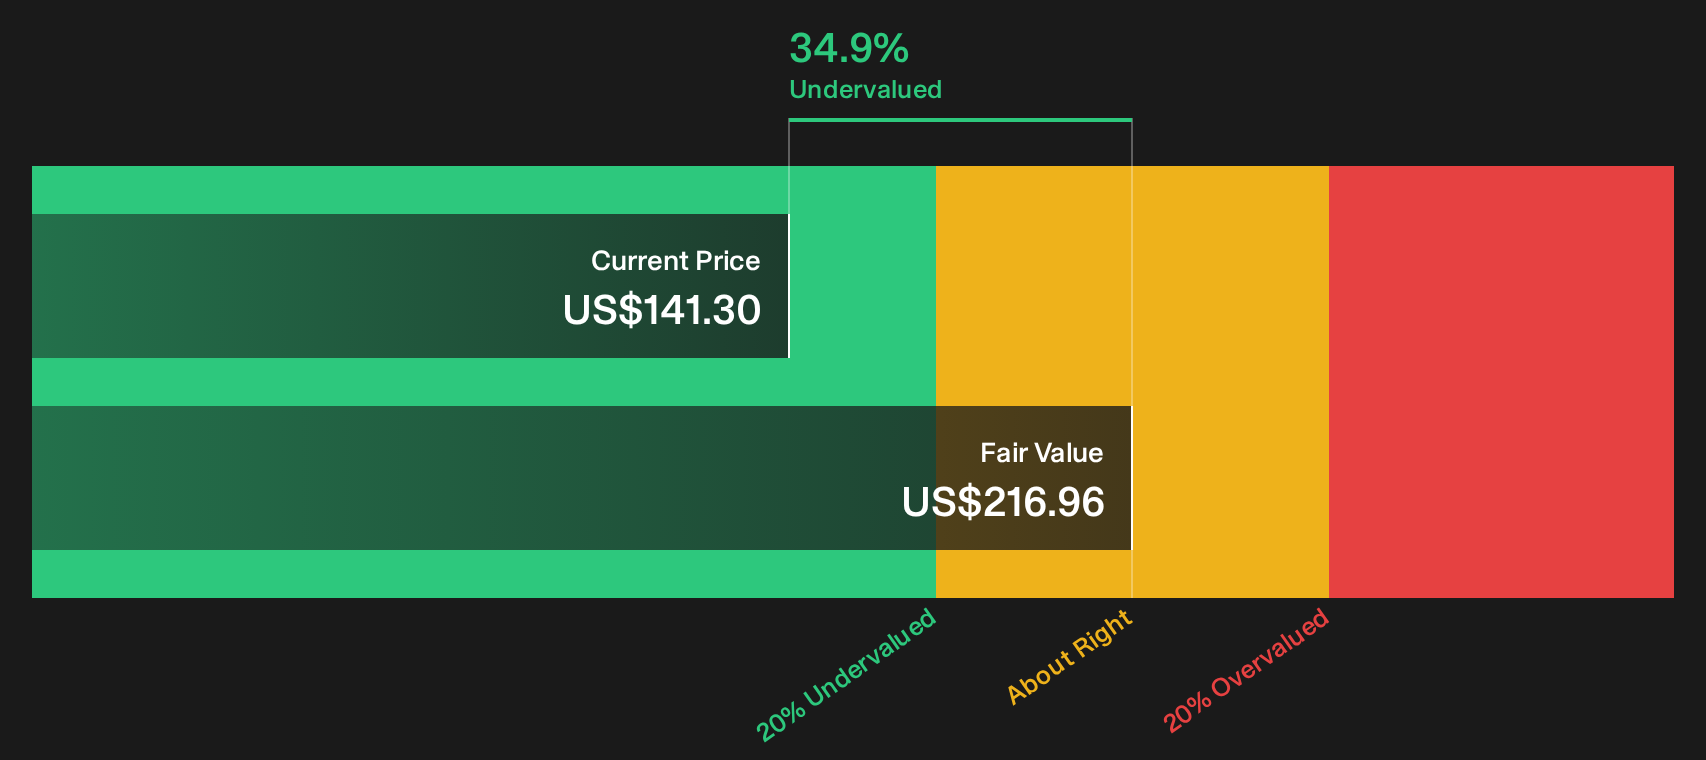
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out City Holding for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 27 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals on City Holding's valuation and income story can feel messy, so move quickly, test the numbers yourself, and weigh both the upside and the risk markers highlighted in the 3 key rewards and 1 important warning sign.
Looking for more investment ideas beyond City Holding?
After weighing City Holding's income profile and valuation clues, broaden your watchlist and pressure test your assumptions against different types of opportunities across the market.
- Target potential mispricings by scanning a curated pool of companies that combine quality fundamentals with attractive valuations using the 27 high quality undervalued stocks.
- Prioritise resilience by reviewing the 31 resilient stocks with low risk scores so you can focus on businesses where balance sheet strength and risk metrics both look more robust.
- Get ahead of the crowd by searching through the 19 high quality undiscovered gems and spot quality ideas before they attract wider attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com