
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
NIKE (NKE) Could Be 6% Undervalued After Its Fiscal 2027 Revenue Warning
NIKE (NKE) just paired softer first quarter figures with a new warning that fiscal 2027 revenue is expected to decline in the high single digits, putting the long term demand story under closer scrutiny.
That guidance hit a stock that was already under pressure, with NIKE’s share price down 19.31% over the past 90 days and the year to date share price return down 45.31%, while the 5 year total shareholder return has declined 75.27%. This points to fading momentum as investors reassess both growth potential and risk.
Scan how other consumer names with steadier expectations are setting up by reviewing the hand picked 27 high quality undervalued stocks that analysts are watching closely around NIKE's reset.
For NIKE at this new, lower share price, the decision gets simple but uncomfortable. Do you step in after the reset, or wait to see how the valuation math now stacks up?
Most Popular Narrative: 6% Undervalued
NIKE closed at $34.61, while the most followed intrinsic value narrative pegs fair value closer to $36.83. This tightens the gap after the recent selloff and frames the fiscal 2027 reset as a valuation test instead of just a growth scare.
Nike runs with a solid operating margin above the ~10% mark, showing it still has some competitive advantage over competitors even with the maturity of its business and a highly competitive industry. Despite currently having a flat revenue growth, its projections point to a slightly below economy growth rate of ~3% over the next couple of years. The fact that the ROIC is almost double its cost of capital is good to see.
See why 20 investors see NIKE as 6% undervalued.
Result: Fair Value of $36.83 (UNDERVALUED)
Still, if NIKE misjudges consumer demand or its high uncertainty rating reflects deeper brand fatigue, that could quickly undermine this 6% undervalued narrative.
Find out about the key risks to this NIKE narrative.
Another View On NIKE: Earnings Multiple Sends A Mixed Signal
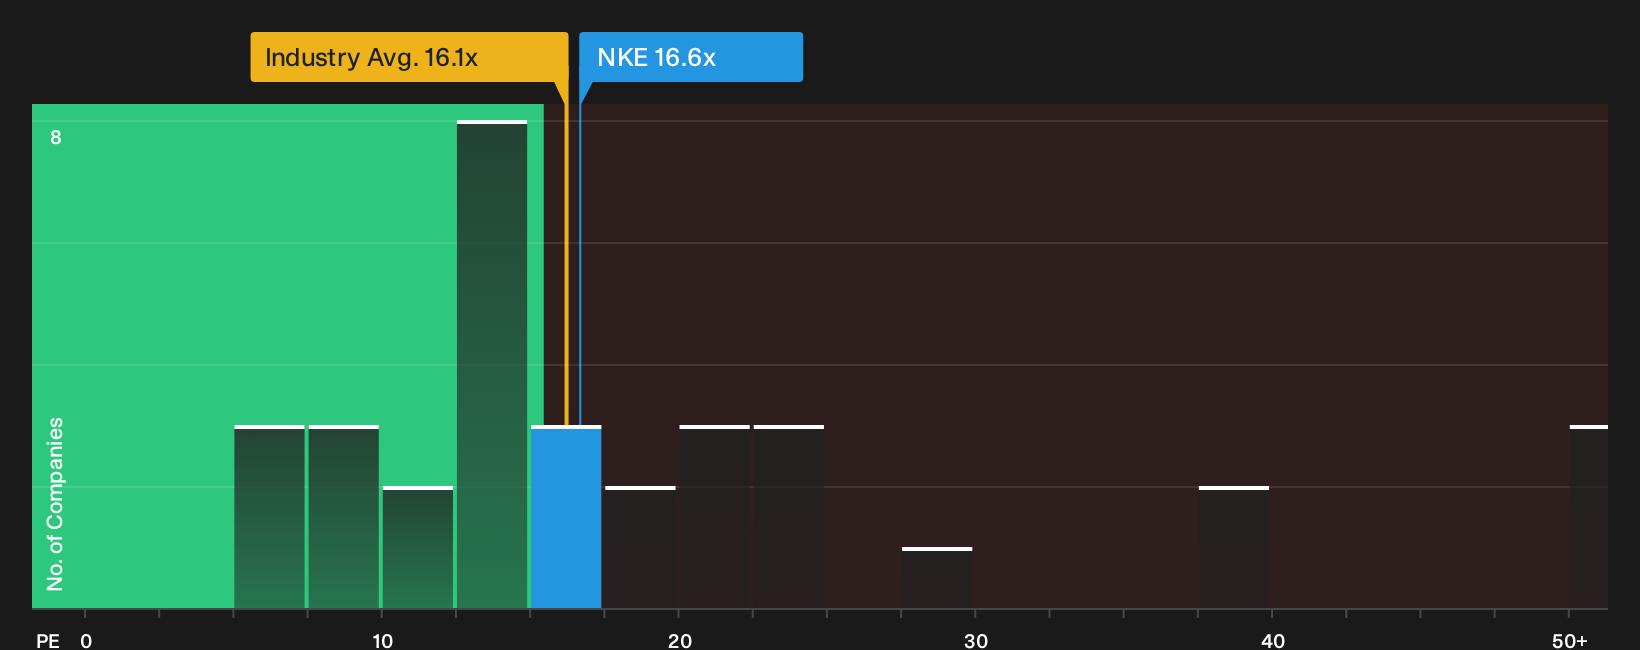
That 6% undervalued fair value story for NIKE sits beside a more cautious read from the earnings multiple. The stock trades on a P/E of 16.6x, which is slightly higher than both the US Luxury industry at 16.1x and its peer average at 15x, while still below an estimated fair ratio of 19.7x.
This mix of a richer tag than rivals but a discount to the fair ratio points to a trade off. Investors are paying more than many peers today, yet the market could still move closer to that 19.7x level if confidence rebuilds. The question is whether you treat that gap as valuation risk or as room for sentiment to repair.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If this NIKE reset feels conflicted rather than clear, move quickly to do your own homework and evaluate both sides of the story for yourself using the 2 key rewards and 1 important warning sign.
Hunting For More NIKE Sized Opportunities?
If NIKE has you reassessing your watchlist, broaden your field of vision now. Fresh ideas often emerge where expectations are calmer and pricing is cleaner.
- Target resilience by scanning companies with robust finances and steady balance sheets through the list of solid balance sheet and fundamentals (25 results).
- Spot potential mispricings by reviewing the 19 high quality undiscovered gems that have strong fundamentals but limited market attention.
- Lower your downside focus by filtering for 31 resilient stocks with low risk scores that aim to keep surprises in check while you pursue long term returns.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com