
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
What Kemper (KMPR)'s Executive Reshuffle Means For Shareholders
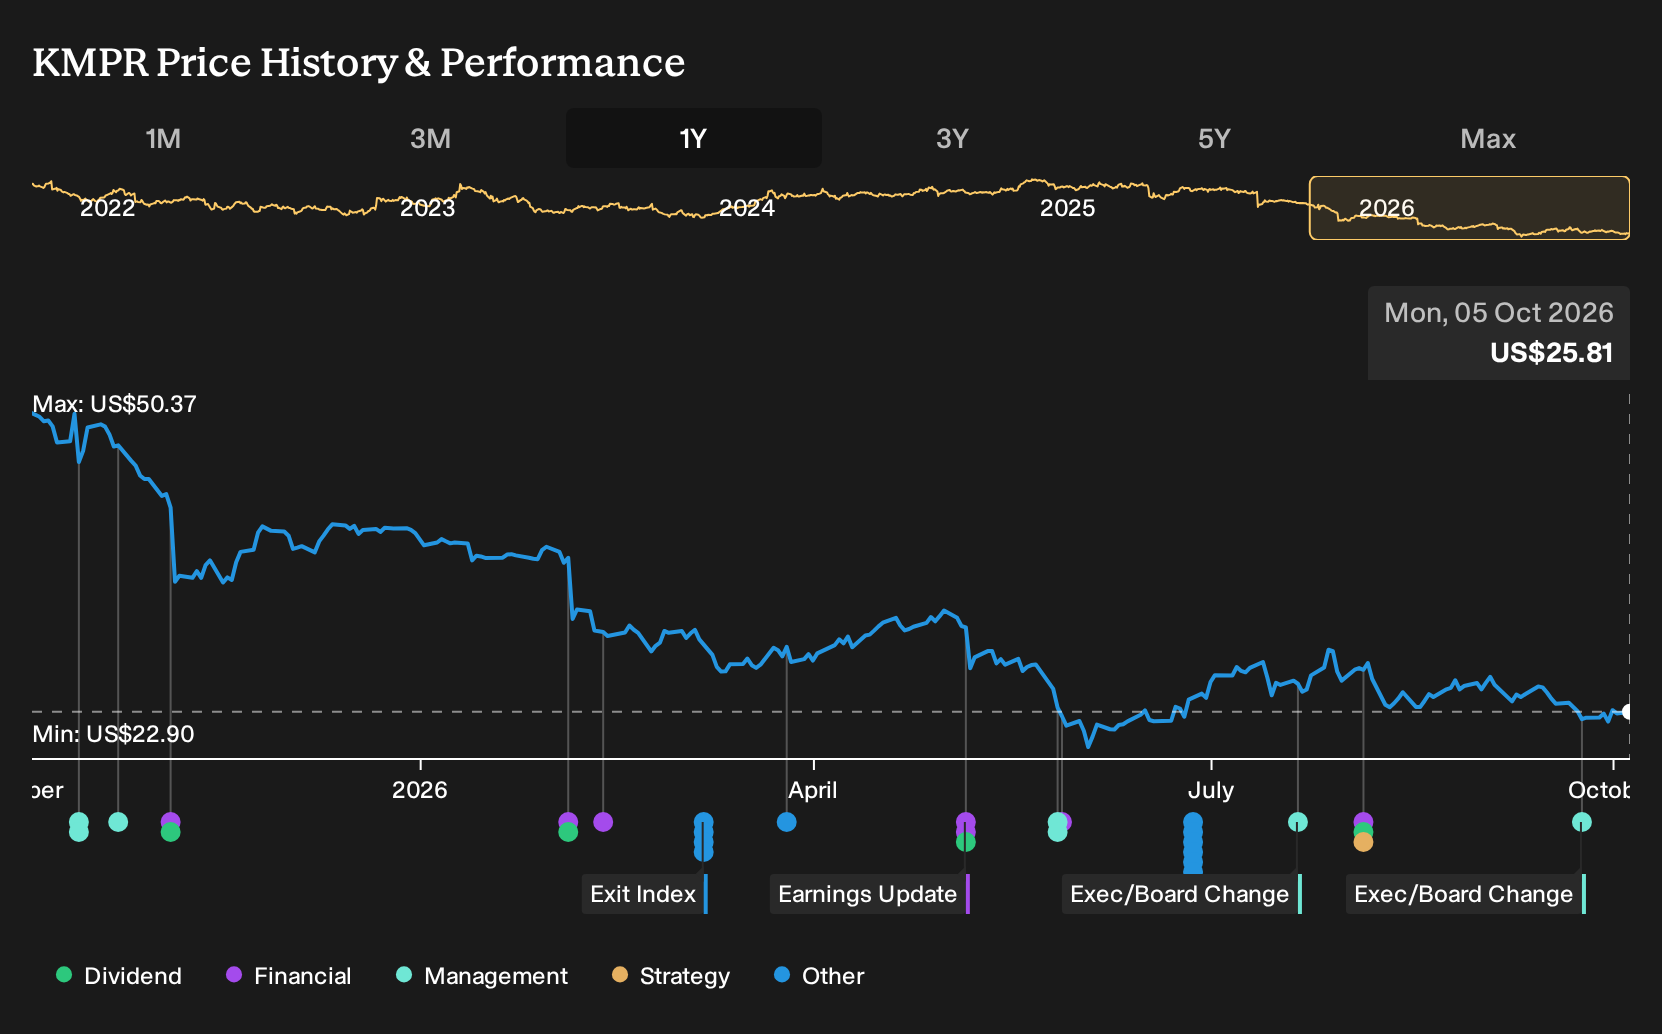
- Kemper Corporation recently created an enterprise Distribution & Marketing organization, appointing Chris Flint as Chief Distribution & Marketing Officer and naming new leaders for P&C Claims and Kemper Life.
- This consolidation of sales, marketing and claims leadership signals a push to tighten execution across nonstandard auto and life operations where cost control and customer reach matter heavily.
- The next area of focus is how Kemper's investment narrative could be influenced by consolidating Distribution and Marketing under a single enterprise leader.
Compare Kemper's push to tighten execution with other insurers reshaping distribution and underwriting by scanning our hand picked list of list of solid balance sheet and fundamentals (25 results).
Kemper Investment Narrative Recap
To own Kemper, you need to believe the company can turn its US$495.5 million loss into sustainable profit while operating in niche auto and life markets that face heavy competition and claims pressure. The short term swing factor remains execution in Specialty Auto and Life, where pricing, risk selection and claims handling shape underwriting results.
The new Distribution & Marketing structure, combined with fresh leadership in P&C Claims and Kemper Life, directly links sales, pricing and claims into one execution chain. If that improves discipline, it could support the path toward the earnings recovery analysts expect. If it does not, the existing pressure on interest coverage and dividend sustainability remains the key risk.
The recent appointment of Todd Williams as Chief Claims Officer in P&C is particularly relevant here. Specialty auto results depend heavily on how quickly and accurately claims are handled, especially when social inflation and litigation risk are in play. A tighter claims organization can support more consistent combined ratios and reduce unpleasant reserve surprises.
For you as a shareholder, that makes claims transformation a practical part of the catalyst story, alongside digital adoption and focus on underserved auto customers. If claims outcomes fail to stabilize, Kemper’s concentration in Specialty P&C and its reliance on higher risk funding sources could keep earnings volatile and limit how much value investors place on any recovery narrative.
Kemper's analyst narrative points to revenue of US$4.3b and earnings of US$527.0 million by 2029, based on an assumed yearly revenue decline of 2.2% and an earnings swing of roughly US$1.0b from the current loss of US$495.5 million to the forecast profit.
Discover how Kemper's fair value indicates a 41% potential upside to its current price that could close faster than many investors expect.
Exploring Other Perspectives
One alternate lens on Kemper leans hard into catastrophe and legal risk. The most pessimistic analysts were already building in only US$4.8b of revenue and US$414.7 million of earnings by 2029, using a low 3.5x P/E. You can read this leadership reshuffle as a possible challenge to that cautious script, or a confirmation. Either way, it is worth comparing both perspectives before you decide what feels more realistic.
Explore 2 other Kemper fair value estimates, including one that suggests as much as 7% downside from the current price.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider forming your own view.
- A great starting point for your Kemper research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Kemper. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Kemper's overall financial health at a glance.
Looking for more Kemper sized investment ideas?
If Kemper has you thinking about where risk, balance sheet strength and future potential line up more cleanly, it can help to scan a broader set of companies before making any decisions.
- For investors who want potential upside without ignoring financial resilience, consider starting with a curated set of companies screened for both value and quality through 27 high quality undervalued stocks.
- If capital preservation matters as much as return, a focus on businesses with sturdier finances can help you sleep better at night, which is where a 31 resilient stocks with low risk scores can be useful.
- When you want ideas that are not already crowded but still backed by solid fundamentals, you can widen your opportunity set with a 19 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com