
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
China Construction Bank (SEHK:939) Raises Fresh AT1 Capital On An Undervalued View
China Construction Bank (SEHK:939) has just completed two RMB 40b capital raisings, including undated Additional Tier 1 bonds, aimed at reinforcing its additional tier 1 capital and meeting evolving regulatory requirements.
At a share price of HK$9.65, China Construction Bank has seen short term share price momentum cool slightly over the past month. A 16.55% 90 day share price return and 23.72% year to date share price return sit alongside a 3 year total shareholder return of 167.30%. This indicates that recent capital raising has been absorbed within a broader period of strong wealth creation for long term holders.
Scan beyond China Construction Bank and compare its capital strength with a curated 226 resilient stocks with low risk scores that has been selected for resilient balance sheets and measured risk profiles.
Bulls see fresh AT1 capital and steady earnings growth as a chance to own China Construction Bank at a large implied discount. Bears focus on regulatory risk and dilution. Which side do the numbers lean toward next?
Most Popular Narrative: 12% Undervalued
Analysts following China Construction Bank see fair value at about HK$10.97, above the last close of HK$9.65. This frames the recent capital raise inside a still supportive valuation gap.
The accelerating wealth accumulation among the rising Chinese middle class is driving continued growth in demand for consumer banking, personal loans, investment services, and wealth management products, as evidenced by industry-leading numbers in personal customers, wealth management AUM, debit/credit card volumes, and insurance fee income. This trend is expected to further boost fee-based revenue growth and support earnings stability going forward.
See why 45 investors see China Construction Bank as 12% undervalued.
Result: Fair Value of HK$10.97 (UNDERVALUED)
Still, if China Construction Bank faces renewed stress in Chinese real estate or sustained pressure on net interest margins, that supportive valuation gap could narrow quickly.
Find out about the key risks to this China Construction Bank narrative.
Another View on China Construction Bank's Valuation
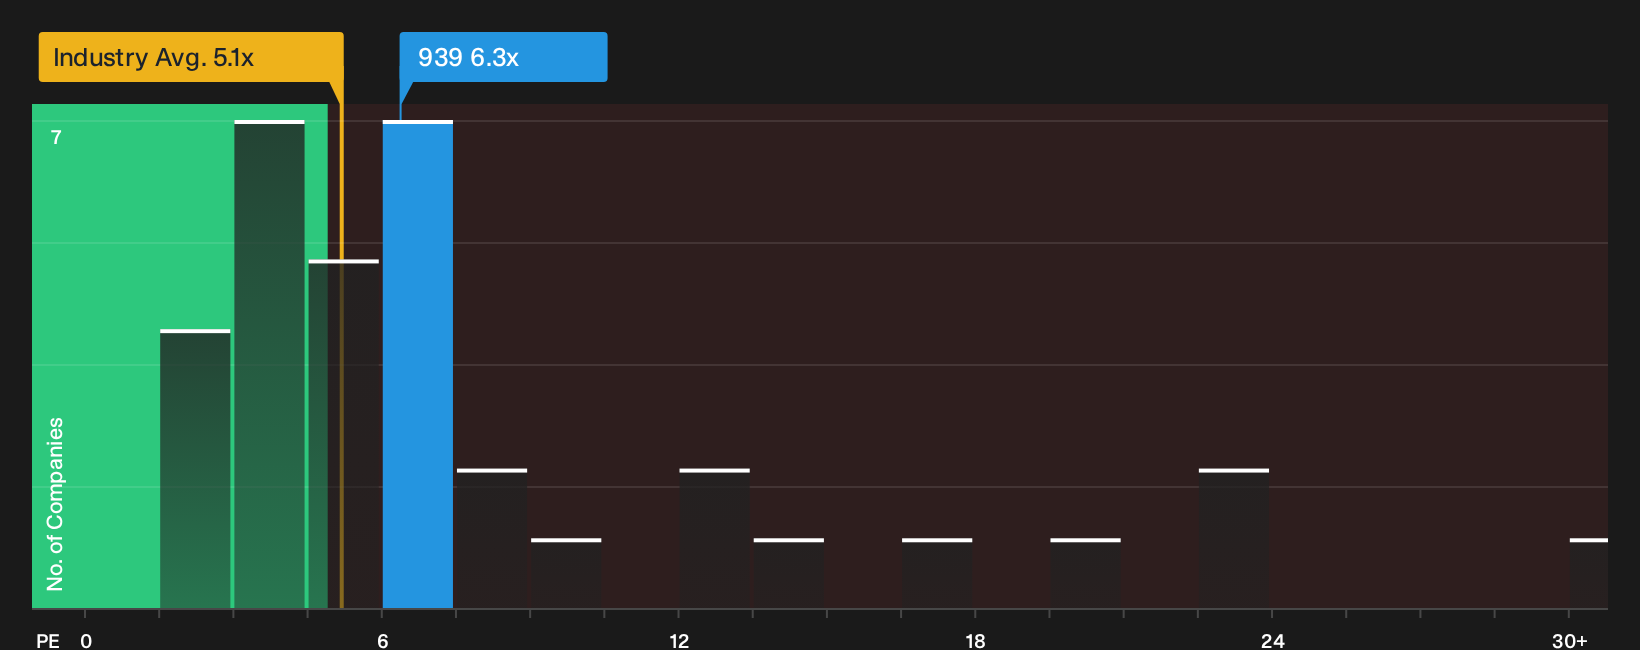
That 12% gap to the HK$10.97 fair value points one way. The P/E ratio points another. China Construction Bank trades on about 6.3x earnings, above the Hong Kong Banks industry at 5.1x, but below a fair ratio of 7.6x that the data suggests the market could move toward.
Paying a higher multiple than the sector but a lower one than the fair ratio leaves you in the middle. It indicates some valuation risk if sentiment moves back toward the industry average, and some potential upside if the stock re rates toward that 7.6x fair ratio. Which outcome do you consider more likely based on your own view of the company and the sector?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment around China Construction Bank in this piece may feel tilted one way. Move quickly, interrogate the data yourself, and weigh the 4 key rewards.
Looking for more investment ideas beyond China Construction Bank?
Do not stop your research with China Construction Bank alone. Use the Simply Wall St screener to quickly surface fresh ideas that match your goals and risk comfort.
- Target resilient income by reviewing 162 dividend fortresses that aim to balance higher yields with robust underlying businesses.
- Hunt for potential bargains by scanning our 185 high quality undervalued stocks sourced from companies with stronger fundamentals than their current pricing suggests.
- Strengthen your core holdings by focusing on a list of solid balance sheet and fundamentals (206 results) that can help anchor your portfolio when conditions get rough.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com