
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
ORIC Pharmaceuticals (ORIC) Gains A De Risked Path As Undervalued Case Holds
ORIC Pharmaceuticals (ORIC) drew fresh attention after partnering with Cancer Research UK to advance ORIC-259, a potential first in class CIP2A targeted cancer therapy, through fully funded early clinical development.
At a share price of $12.49, ORIC Pharmaceuticals has seen short term momentum soften, with a 7 day share price return down 6.58% and a 30 day move down 2.88%. This comes even as the 90 day gain of 14.59% and year to date share price return of 52.88% point to stronger underlying interest that likely reflects shifting expectations after the Cancer Research UK deal.
Scan beyond ORIC Pharmaceuticals and the Cancer Research UK partnership by reviewing 19 high quality undiscovered gems that could be next in line for de-risked development deals.
Analysts see ORIC Pharmaceuticals worth closer to their US$21.43 target, yet the market is holding the line near US$12.49 after the Cancer Research UK deal. Is that discount caution or opportunity?
Most Popular Narrative: 40% Undervalued
On the prevailing storyline, ORIC Pharmaceuticals screens as undervalued, with a fair value of $20.67 against the last close at $12.49. This puts a lot of weight on how late stage trial data and cash usage play out over the next few years.
Cash of US$388m at the end of Q2 2026 with guidance that this funds operations into the second half of 2028, including the ongoing Himalayas-1 Phase III and a planned Phase III for enozertinib starting in early 2027, along with Bayer supplying darolutamide for Himalayas-1 at no cost while ORIC retains full rinzimetostat rights, provides capacity to advance late stage programs while potentially limiting near term equity dilution and supporting future net margins and earnings leverage if products reach market.
See why 1 investors see ORIC Pharmaceuticals as 40% undervalued.
Result: Fair Value of $20.67 (UNDERVALUED)
Still, the bullish ORIC Pharmaceuticals story can unravel fast if large Phase III trials disappoint or fresh PRC2 safety issues curb physician confidence and use.
Find out about the key risks to this ORIC Pharmaceuticals narrative.
Another View On ORIC Pharmaceuticals
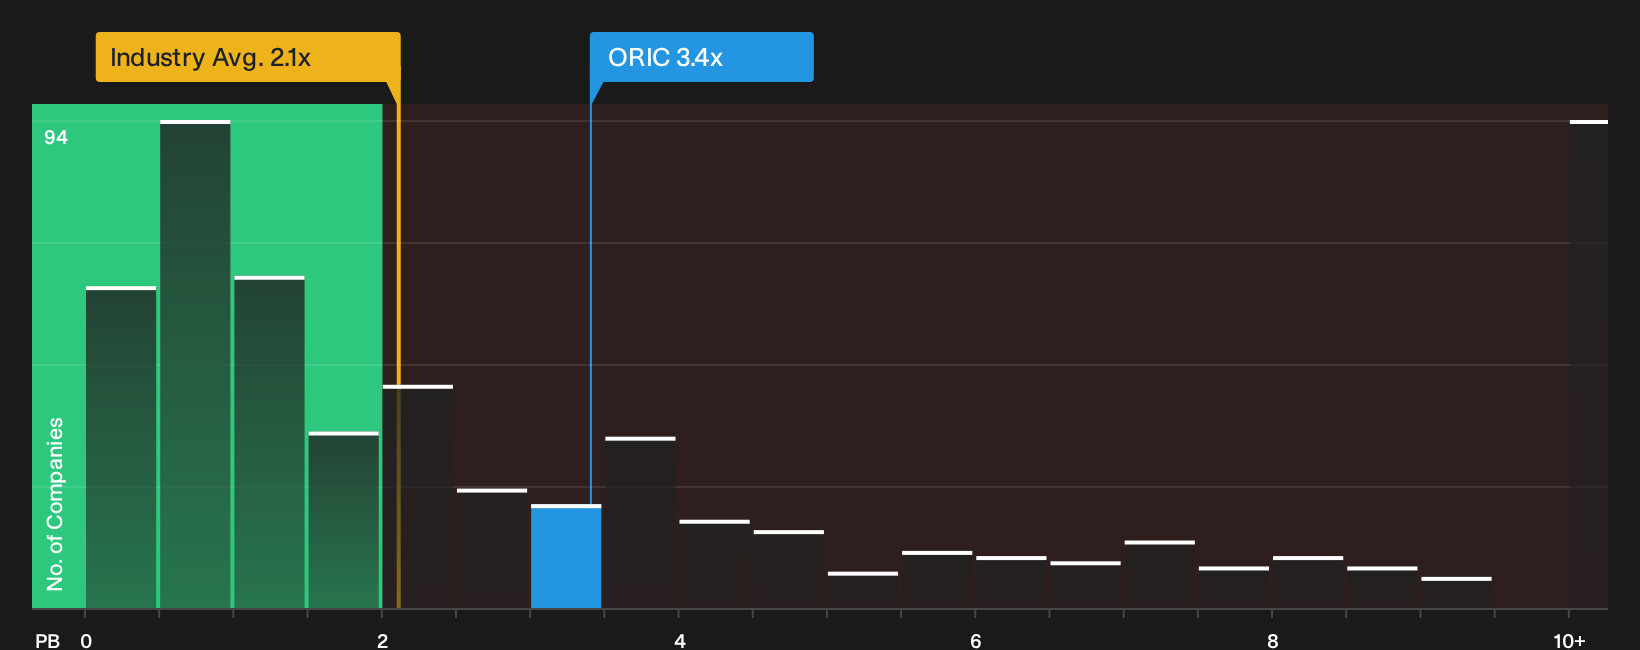
That 40% upside case leans heavily on future earnings, yet today ORIC Pharmaceuticals is still loss making and is being judged on asset value instead. On a P/B of 3.4x versus a US Biotechs average of 2.1x and a peer average of 7.6x, investors are paying a clear premium to the wider sector but a discount to closer comparables. Is that pricing a sensible middle ground, or is it setting up a tougher ride if sentiment turns?
For a closer look at how this price stacks up against the underlying numbers, start with the valuation breakdown in the See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
If this ORIC Pharmaceuticals story feels finely balanced, move quickly to pressure test it against the hard numbers, starting with the 4 important warning signs.
Looking for more investment ideas beyond ORIC Pharmaceuticals?
If ORIC Pharmaceuticals has sharpened your thinking, do not stop here. The real edge often comes from lining it up against other high quality opportunities.
- Target resilient balance sheets by comparing ORIC against companies on the list of solid balance sheet and fundamentals (25 results) that pair financial strength with disciplined fundamentals.
- Hunt for mispriced opportunities by scanning the 27 high quality undervalued stocks that match strong business quality with potentially attractive entry points.
- Lock in potential income streams by reviewing the 7 dividend fortresses that offer higher yields while still aiming for stability.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com