
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
3 Media Stocks Worth Watching As Consolidation Reshapes Warner Music And TKO
Media investors just watched Paramount close a reported $111b deal for Warner Bros Discovery and create Skydance, a new heavyweight with studios, streamers and news networks under one roof. That kind of consolidation can reshuffle who controls content, pricing power and audience attention. This piece walks through three large cap media and entertainment stocks exposed to that same story, and how that backdrop might shape their risk and reward trade off.
The stocks covered below are just a starter set, and the full screen on Simply Wall St surfaced 11 more large-cap media and entertainment companies with equally compelling consolidation angles that are not discussed here. To identify and analyze those additional potential plays in one place, head straight to the Large-Cap Media & Entertainment Consolidation Plays screener.
Warner Music Group (WMG)
Warner Music Group plugs into the consolidation story from a different angle, as a global rights holder whose catalog and licensing reach can matter just as much as studio libraries when distributors and platforms look for scaled content partners.
Warner Music Group is a global music entertainment group spanning Recorded Music and Music Publishing. Most revenue comes from Recorded Music at about US$5.9b, with roughly US$1.4b from Publishing, reflecting a catalog of around two million compositions. The stock carries a market value near US$14.0b.
"Although AI partnerships with platforms like Suno, Stability, Klay and Udio are designed around consumption based models that could lift revenue per user, there is clear execution risk in turning these early deals into sustained, high margin earnings contributions as usage patterns and artist opt in levels are still unproven, which could limit the benefit to net margins."
What happens if a single pressure point in those new models reshapes how much of each streaming dollar Warner Music Group keeps.
If that pressure point matters for you, read the full narrative for Warner Music Group to see how Warner Music Group’s AI upside and catalog strength could be separating from simple streaming economics.

USA TODAY (TDAY)
USA TODAY sits in this consolidation screen as the clearest pure media play, plugged directly into how advertisers and distribution partners respond when bigger TV and streaming groups start throwing more weight around.
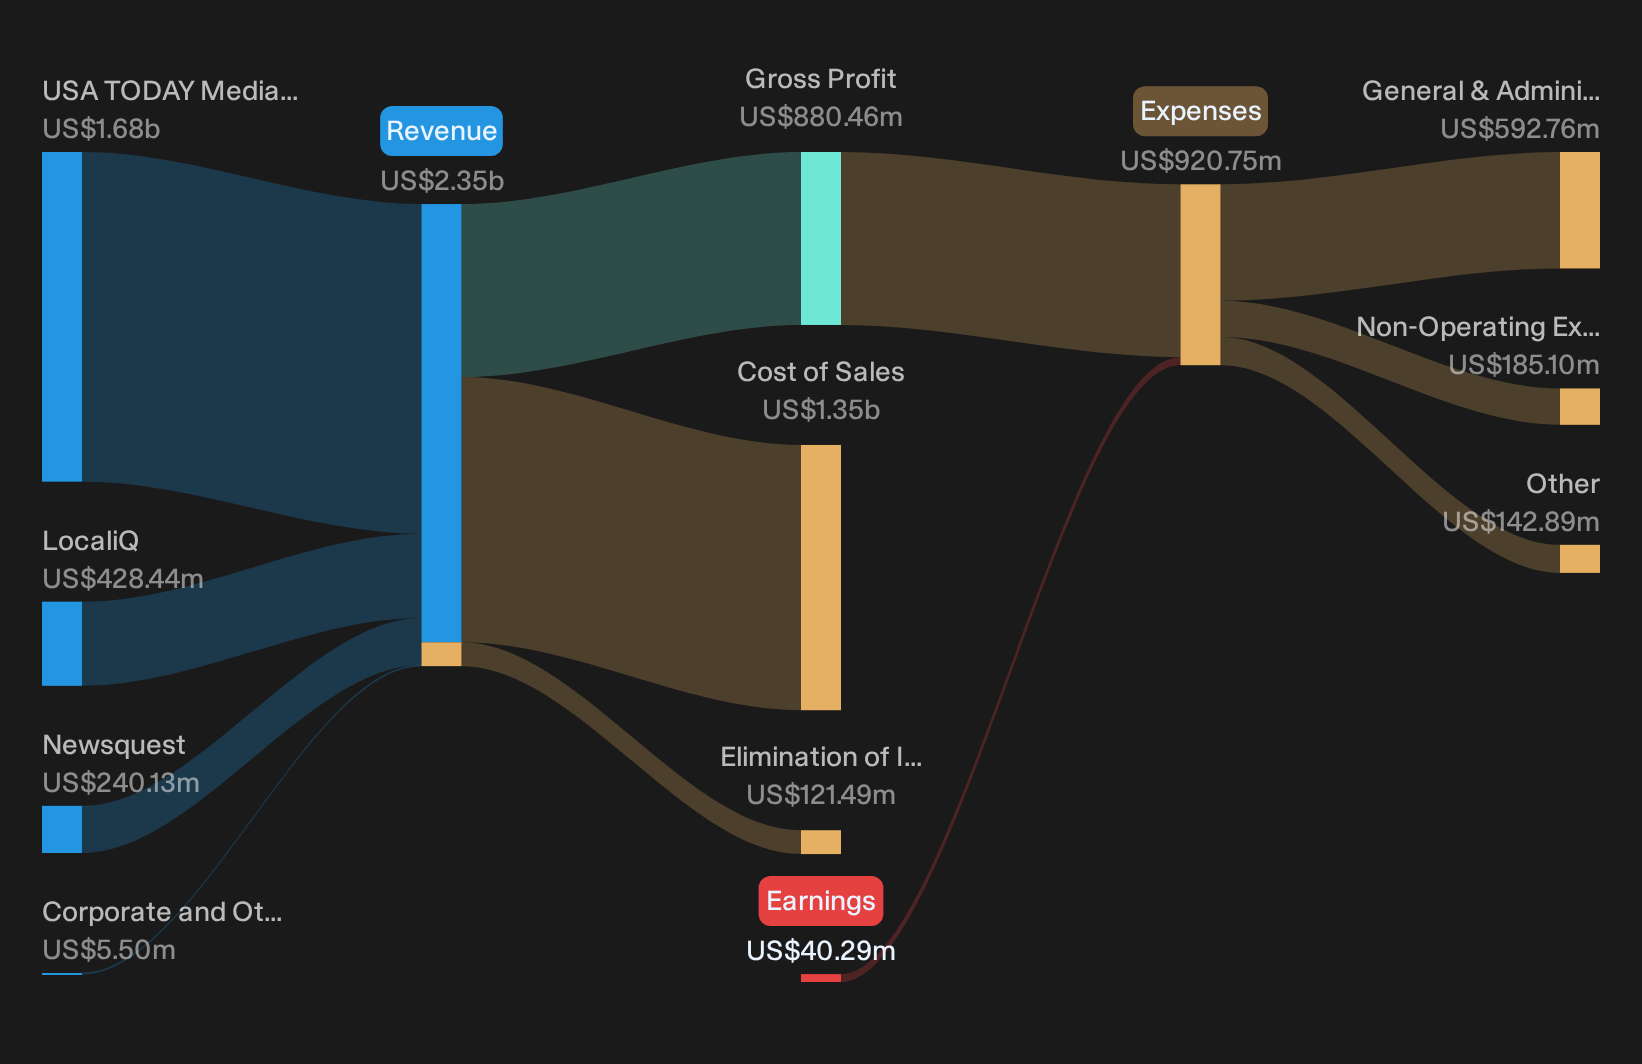
USA TODAY Co. runs a mix of news publishing and digital marketing platforms tied to U.S. media and advertising trends, with most revenue from USA TODAY Media at about US$1.7b, plus roughly US$428 million from LocaliQ and US$240 million from Newsquest, and a market value near US$1.0b.
"Accelerating shift of the revenue mix toward nearly half digital today, with expectations to surpass 50 percent, increases scalability and reduces print-driven cost drag."
What really matters is how one less-visible piece of the digital engine ultimately filters into earnings quality as consolidation pressure builds around it.
That quiet driver of earnings quality is where the full narrative for USA TODAY maps how USA TODAY’s digital shift, consolidation pressure and ad trends could be decoupling from legacy print risk.
TKO Group Holdings (TKO)
TKO Group Holdings ties into the Large-Cap Media & Entertainment Consolidation Plays theme through premium sports rights that streaming platforms and broadcasters increasingly compete for. This makes its combat sports and live events portfolio a useful contrast to broader film and TV focused peers.
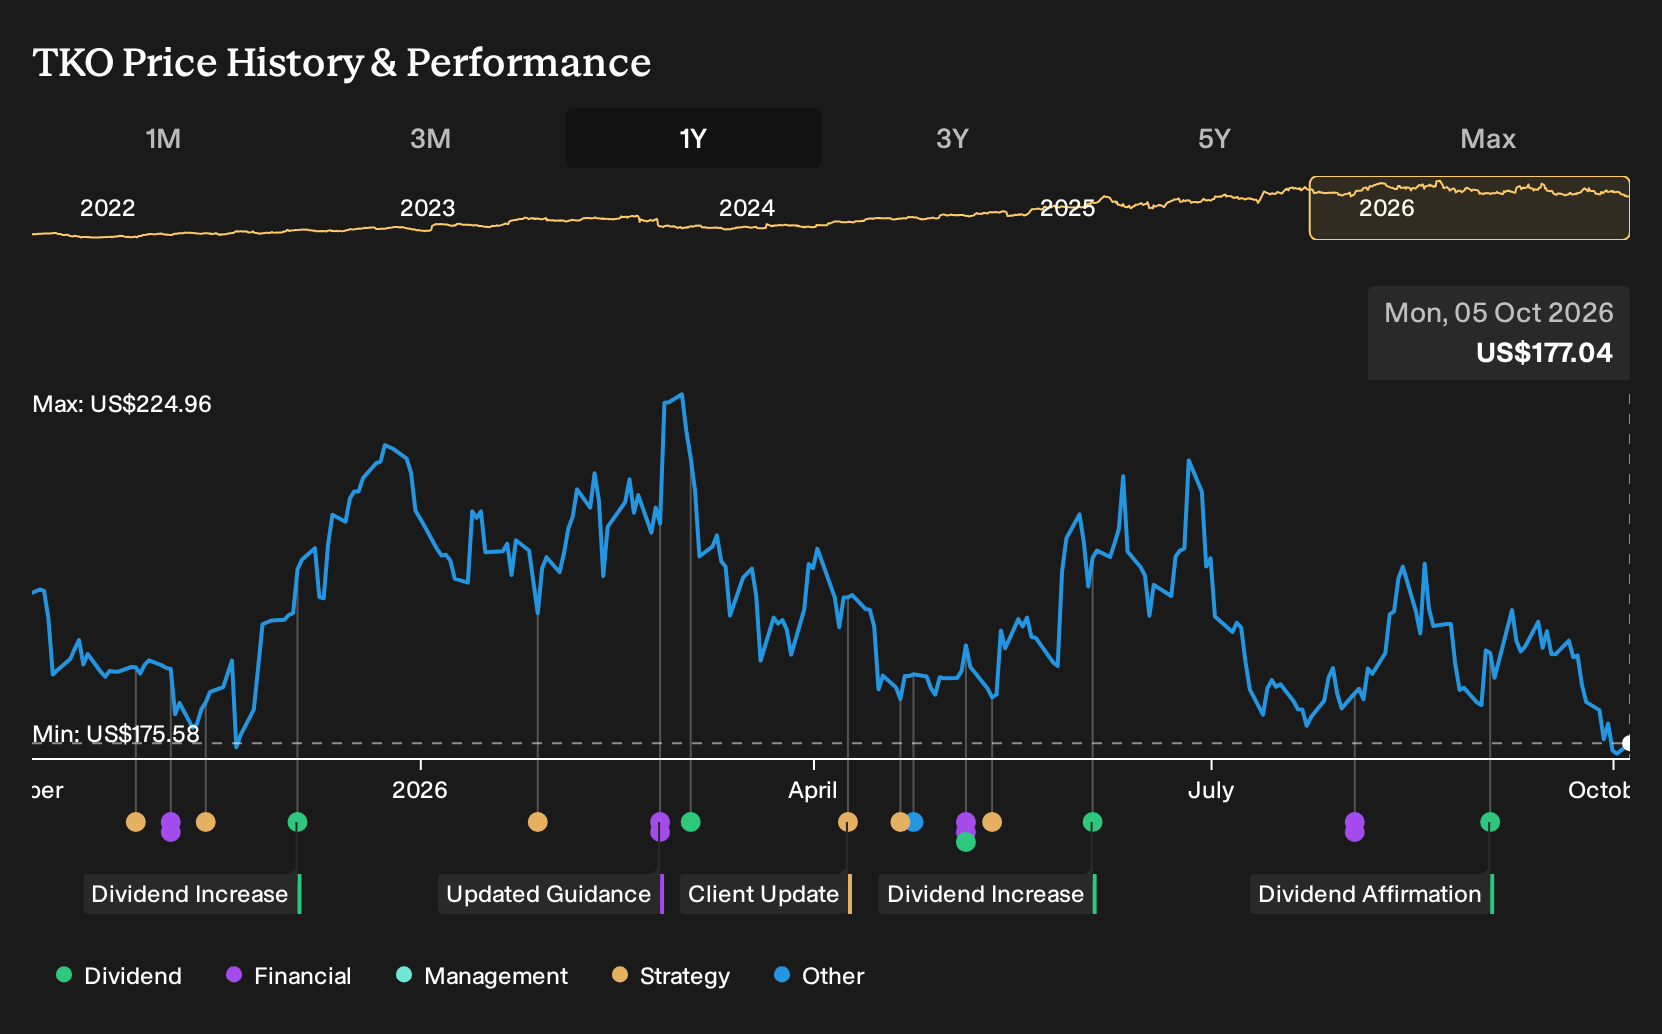
TKO Group Holdings runs UFC, WWE and IMG, monetising combat sports, sports entertainment and event services as a US$33.2b media and live experiences business. Revenue is split across WWE at about US$1.9b, UFC at roughly US$1.7b, IMG near US$1.6b plus smaller corporate items.
For this screen, the interest in TKO Group Holdings is less about another general entertainment conglomerate and more about a content owner whose live fights, storylines and hospitality packages sit at the intersection of sports media consolidation and the hunger for must watch programming.
"Embedded step ups in long-term media rights for UFC with Paramount and WWE with ESPN and Netflix, alongside annual escalators and broader distribution, are set to structurally lift high-margin contractual revenue and expand EBITDA margins and earnings visibility from 2026 onward."
What really moves the needle from here is how a single assumption about future pricing power across those rights deals ultimately holds up once the next round of consolidation plays out.
That pricing leap of faith is exactly where the full narrative for TKO Group Holdings pulls apart rights assumptions, consolidation risk, and how TKO Group Holdings’ media muscle could still accelerate earnings power.
Seeking Alternatives Before The Crowd?
Fresh ideas move first. Breakout stories gain momentum while screens load slowly and prices keep flying. Spot under the radar for now opportunities before information gets stale. Act now.
- Spot cash rich compounders early by scanning the list of solid balance sheet and fundamentals (25 results) that filters for resilient businesses investors often overlook until momentum is already building.
- Track the next infrastructure wave by following the 39 power grid technology and infrastructure stocks highlighting companies involved in grid upgrades while valuations can still be monitored before they move.
- Review the curated 89 robotics and automation stocks focused on automation leaders as robotics demand evolves and expectations change.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com