
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Huron (HURN) Stock Looks Below Fair Value On Earnings
Huron Consulting Group has delivered a powerful run for long term holders, yet the current US$160.10 share price raises a straightforward question for anyone looking at the stock today. Are the earnings supporting where Huron now trades, or has the share price moved ahead of the underlying profit power of the business?
- Over the past 5 years, Huron Consulting Group has returned 215.4%, which puts real weight on whether that gain is grounded in its earnings profile.
- The consulting model relies heavily on converting fee revenue into consistent profit, so the quality and stability of those earnings can shape how investors think about what they are willing to pay for the shares.
- Your read on Huron Consulting Group is one view; the desks covering it have another. See what analysts think Huron Consulting Group's shares could be worth.
The issue now is whether Huron Consulting Group's current price is justified by its earnings when stacked against a Fair Ratio benchmark.
If you are weighing Huron Consulting Group against other opportunities that also put earnings front and centre, a focused stock screen built around 27 high quality undervalued stocks can be a useful second starting point for your research.
Does Huron Consulting Group Look Undervalued on Earnings?
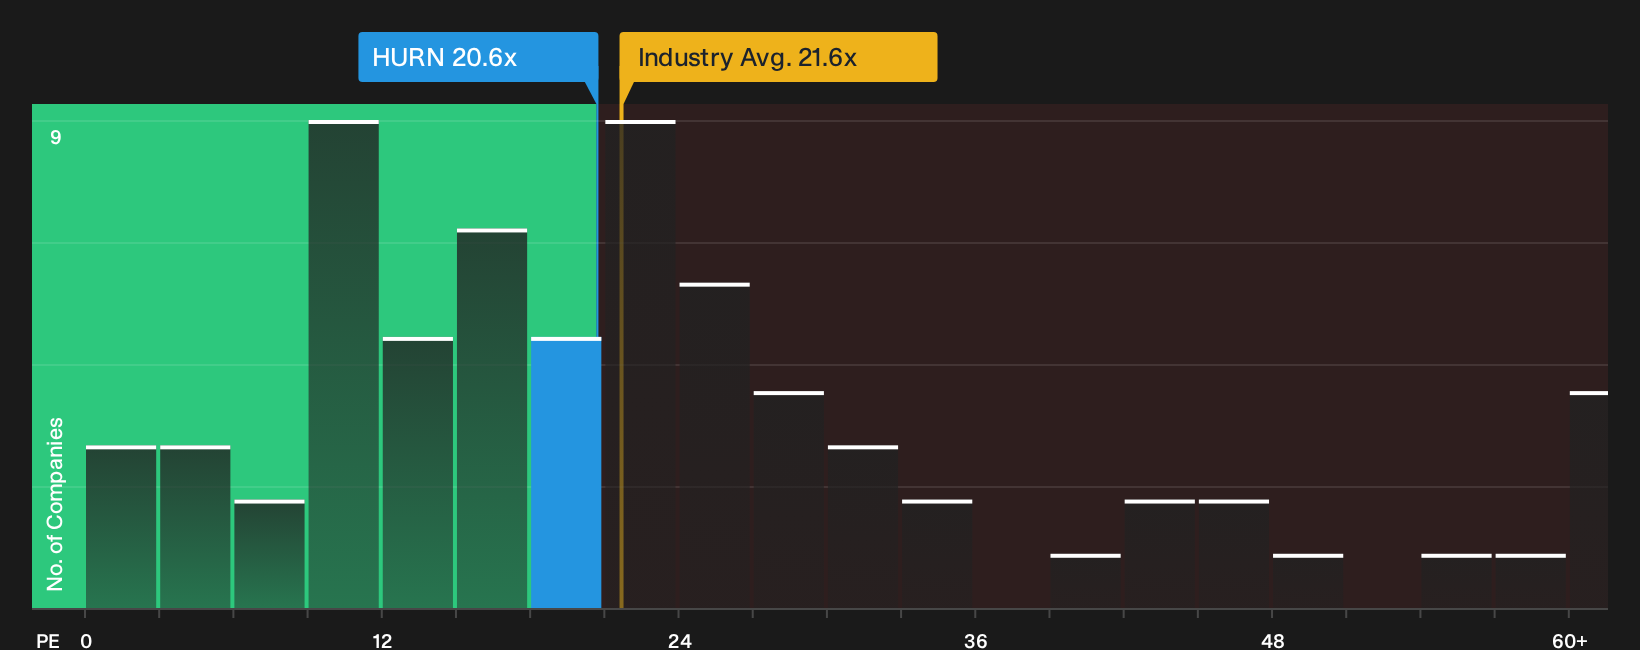
The P/E ratio works well for Huron Consulting Group because investors largely focus on its ability to turn fee income into consistent earnings. On this measure, the stock trades on roughly 20.6x, which is slightly below the Professional Services industry average of about 21.6x and under the peer group mark near 24.1x. That places Huron on a lower earnings multiple than many comparable consulting businesses even though it is in the same broad segment.
A Fair Ratio estimate, which blends the company’s growth profile, profitability, size and risk into a tailored benchmark, points to a higher P/E level than where Huron currently trades. The current 20.6x sits below that reference point, so the market is assigning a discount relative to what this framework suggests might be appropriate for the earnings stream. For anyone weighing whether that gap reflects opportunity or caution, it is worth examining the durability of Huron’s consulting demand, contract mix and fee rates before drawing a conclusion on the share price. Explore the numbers behind Huron Consulting Group's P/E valuation.
The Huron Consulting Group Narrative: What Would Justify Today's Price?
Simply Wall St Narratives take the valuation puzzle around Huron Consulting Group and turn it into clear scenarios that spell out what kind of growth, margins and earnings path would need to hold for the stock to be worth materially more or less than it is today. Each view lays out the assumptions behind its fair value so you can track those against Huron Consulting Group's reported numbers over time on the Community page.
Community views on Huron Consulting Group are split between those who see more upside left in the consulting story and those who think expectations already bake in a lot.
Bull case: 26% undervalued
"The build out of managed services, including revenue cycle in healthcare and research administration in education, is increasing recurring work tied to long duration contracts…"
Discover why this Narrative puts Huron Consulting Group at 26% undervalued.
Bear case: roughly fairly valued
"Although programmatic acquisitions in commercial digital, compliance and strategy are broadening the platform, the near term mix shift toward lower margin digital work and integration risk from recent deals…"
Explore why this Narrative puts Huron Consulting Group at roughly fairly valued.
One more piece for the Huron Consulting Group puzzle
Price multiples only tell part of the story, because the research community has already sketched out where they think Huron Consulting Group could be a few years from now, and that forward view can sharpen how you interpret today's terms. Explore where analysts expect Huron Consulting Group to be in a few years.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com