
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Aflac (AFL) Could Be 5% Undervalued Following Its Recent Pullback
Aflac (AFL) draws attention after recent trading left the shares at a last close of $112.38, putting recent returns in focus as investors reassess the insurer’s long term track record.
Recent trading has come after a softer patch, with Aflac’s share price return down 4.12% over the past 30 days and 7.50% over 90 days, yet still modestly positive year to date and supported by a 5-year total shareholder return of 130.98%. This suggests that long term holders have seen much stronger gains than the short term tape implies.
Look past Aflac’s recent pullback and compare it with other insurers that have strong balance sheets and cash flows using our curated list of 31 resilient stocks with low risk scores.
The share price has slipped while analyst targets and intrinsic value estimates sit higher, leaving a clear gap. Does Aflac now trade meaningfully below where fair value models cluster?
Most Popular Narrative: 5% Undervalued
The most followed Aflac narrative pins fair value at $118.53, modestly above the last close at $112.38. This puts the current pullback in a different light for anyone focused on long term cash flows and capital returns.
The repositioning of about 5% of Aflac’s global investment portfolio, using foreign exchange gains on dollar assets to support moves out of older bonds, is expected to add over US$50 million of annual net investment income on a run rate basis. This directly supports earnings even if premium growth stays modest.
See why 40 investors see Aflac as 5% undervalued.
Result: Fair Value of $118.53 (UNDERVALUED)
Still, Aflac’s case can weaken quickly if Japan’s pressured premiums persist, or if fallout from the recent cybersecurity breach drags on margins and trust.
Find out about the key risks to this Aflac narrative.
Another View: What Aflac’s P/E Is Telling Investors
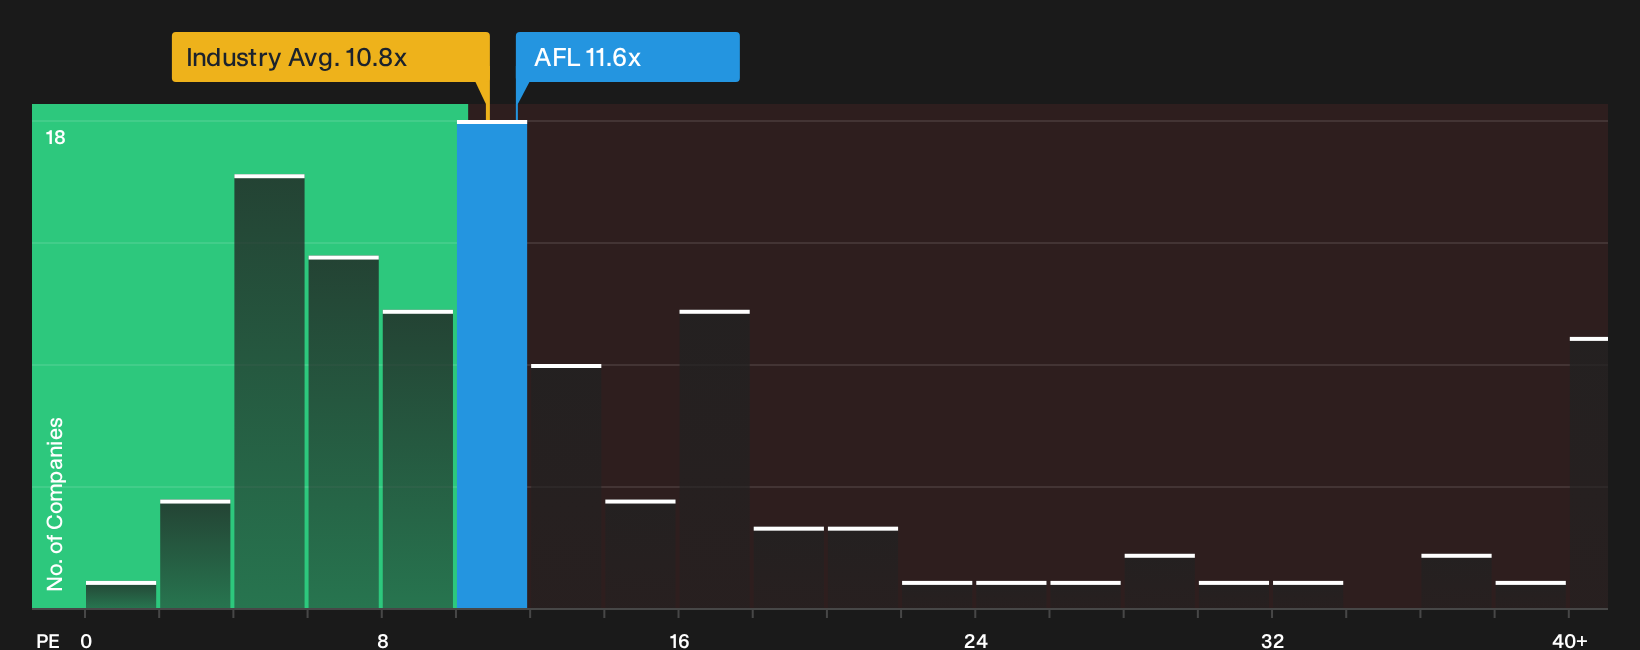
A different lens on Aflac looks at simple pricing. The stock trades on an 11.6x P/E, which is above the US Insurance industry at 10.8x and also above a fair ratio of 8.9x. That gap points to valuation risk rather than a margin of safety. Which signal do you trust more?
To see how that pricing gap stacks up against earnings power in more detail, review the valuation breakdown in the See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages on Aflac’s value and risks can feel confusing, so consider acting promptly, studying the full picture, and weighing both sides using 3 key rewards and 2 important warning signs
Looking for more Aflac sized opportunities?
Do not stop your research with Aflac. Broaden your watchlist with other ideas that match your risk, return, and income goals using focused stock screens.
- Target potential bargains early by scanning companies that appear mispriced against their fundamentals through the 27 high quality undervalued stocks.
- Strengthen your income stream by zeroing in on higher yielding businesses that may offer more dependable payouts using the 7 dividend fortresses.
- Protect your downside by filtering for companies with sturdy finances and resilient balance sheets via the list of solid balance sheet and fundamentals (25 results).
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com