
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
How to Play Okta Stock at New 3-Year Highs
Okta (OKTA) is entering a bigger phase of the identity-security market as cloud adoption and artificial intelligence (AI) reshape how enterprises protect digital access. The company is expanding beyond employees and customers to secure AI agents and machine identities, giving it a potentially much larger opportunity as businesses accelerate AI deployment.
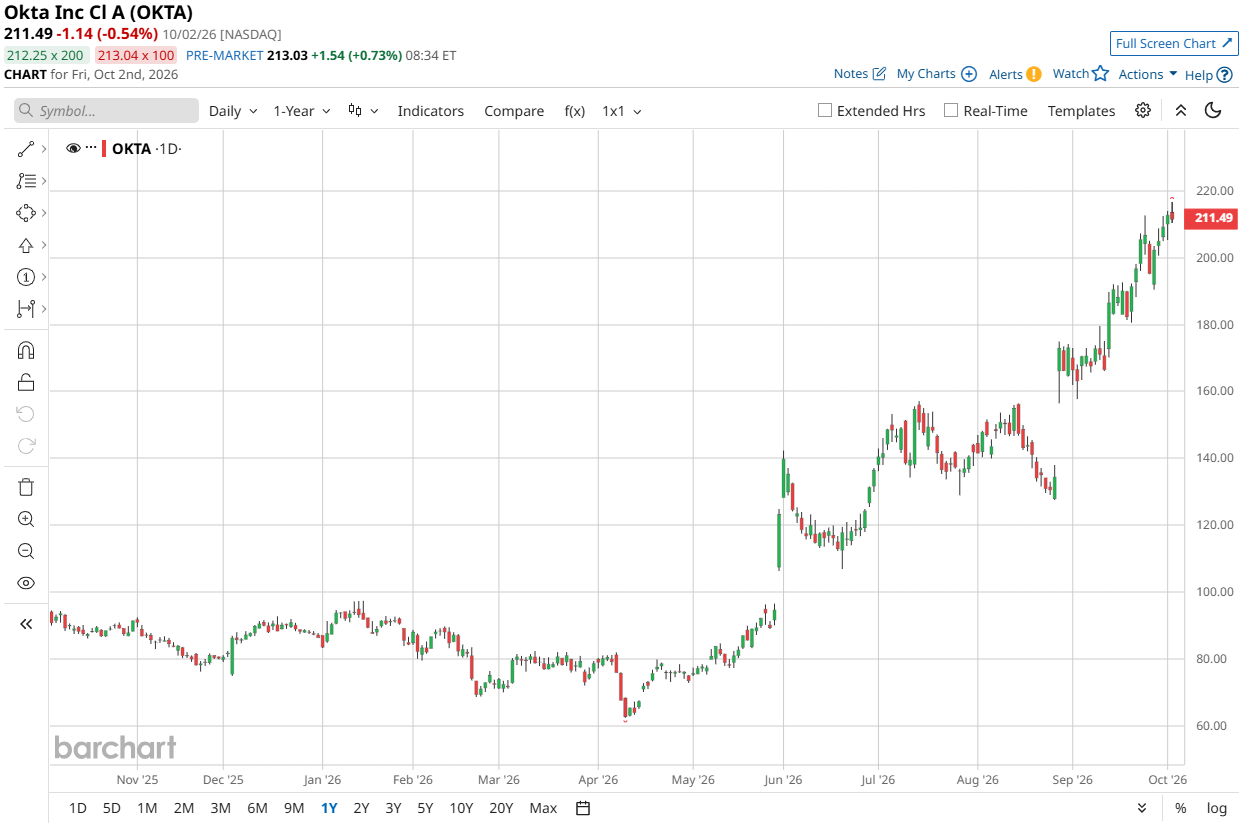
This opportunity is becoming more important as the security risks around rapidly advancing AI systems come into sharper focus. Against that backdrop, OKTA stock jumped 28.6% on Thursday, Aug. 27, after the company reported better-than-expected Q2 FY2027 results and raised its full-year outlook.
The strong results and brighter outlook have since helped push the shares to a fresh three-year high of $216.59, reached on Monday, Sep. 28. At this level, investors are looking beyond Okta’s core identity business and assigning greater value to the company’s potential for sustained subscription growth, rising AI-related demand, and improving profitability.
About Okta Stock
Headquartered in San Francisco, California, Okta is a global identity and access management company that helps organizations securely manage users, devices, applications, APIs, and AI agents.
Holding a market cap of nearly $37 billion, its platform provides authentication, single sign-on, multifactor authentication, identity governance, privileged access, and threat protection, enabling secure, flexible access across cloud, on-premises, hybrid, and AI-driven environments.
Investors have also rewarded that positioning. Its shares have gained 122.8% in the last 52 weeks, and are up 163.7% in the past six months. Moreover, in just the past three months, the stock has gained 29.6%.
From a valuation standpoint, OKTA stock is currently trading at 53.83 times forward adjusted earnings and 11.47 times sales. The multiples sit above the industry averages and their own five-year historical averages, reflecting a premium.
Okta Surpasses Q2 Earnings
On Aug. 26, Okta reported Q2 FY2027 results, highlighting resilience in its core identity business alongside stronger adoption of newer products. Total revenue increased 10.6% year over year (YOY) to $805 million, exceeding analyst estimates of $792.8 million, while subscription revenue rose 11.5% to $793 million, underscoring continued recurring-revenue strength.
The stronger forward indicator was remaining performance obligations (RPO), which climbed 17% YOY to $4.86 billion. Current RPO also accelerated 14% to $2.59 billion, pointing to healthier demand and greater revenue visibility. That momentum was broad-based across Workforce and Customer Identity, with particularly strong traction among large enterprises.
Customers generating more than $1 million in ACV increased over 20% YOY, while record bookings, improved conversion, upselling, and stronger partner engagement added to growth. New products accounted for 30% of bookings, led by Identity Governance. AI-agent demand also emerged as a potential growth catalyst.
On the bottom line, non-GAAP net income rose 14.8% to $194 million, while non-GAAP EPS increased 15.4% to $1.05, beating analyst estimates of $0.96. Free cash flow jumped 40.1% YOY to $227 million, reinforcing the company’s operating strength.
Looking ahead, management expects Q3 FY2027 revenue of $813 million to $817 million, representing 10% YOY growth, with non-GAAP diluted EPS of $0.92 to $0.94. For FY2027, Okta projects revenue of $3.216 billion to $3.226 billion, implying 10% to 11% YOY growth, alongside diluted EPS of $3.90 to $3.94.
On the other hand, analysts expect Q3 FY2027 EPS to rise 38.7% YOY to $0.43. For full-year FY2027, they project 21.5% growth from the previous year to $1.92, followed by another 26.6% increase to $2.43 in FY2028.
What Do Analysts Expect for Okta Stock?
Morgan Stanley analyst Meta Marshall has reiterated an “Overweight” rating and raised the price target from $200 to $245, reflecting stronger conviction in Okta’s long-term agentic identity opportunity. Similarly, Scotiabank analyst Patrick Colville reiterated an “Outperform” rating on OKTA stock and raised the price target from $190 to $245.
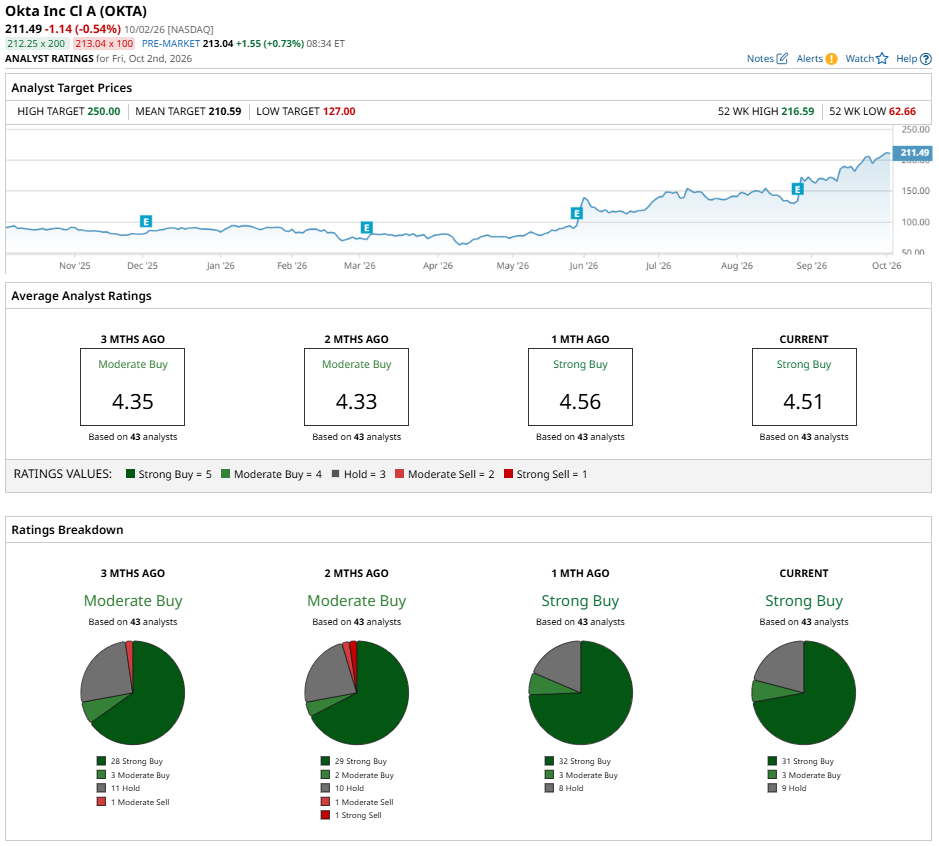
Wall Street has assigned the stock an overall rating of “Strong Buy.” Among 43 analysts covering the name, 31 rate the stock a “Strong Buy,” three have assigned a “Moderate Buy,” while nine recommend “Hold.”
To that end, the stock is already trading above its average price target of $210.59, whereas the Street-high target of $250 suggests a gain of 18.2% from current levels.
On the date of publication, Aanchal Sugandh did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.