
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Can Charles Schwab (SCHW) Still Trade At A Discount After Record Earnings?
Charles Schwab has delivered a 97.3% gain over the past three years, yet the sharper question for anyone looking at the stock today is whether that share price now lines up with the returns the business earns on its capital. With fresh headlines around earnings, funding and new products, the current valuation rests heavily on how effectively Schwab can keep turning its balance sheet and client base into profitable growth.
- A roughly 97.3% share price increase over three years puts a lot of faith into Schwab's ability to keep generating attractive returns on every dollar it commits to the business.
- Record recent earnings alongside a new US$3.6b senior note issuance and the Forge Global acquisition can shift expectations for future profitability, funding costs and how efficiently Schwab reinvests capital into higher return opportunities.
- If you'd rather focus on earnings, this one's for you. See why Charles Schwab's 17.4x P/E tells a different valuation story.
The issue now is whether the current price for Charles Schwab is fully supported by the returns it earns on its capital.
If you want a broader starting point for research beyond Charles Schwab, a focused screen of solid balance sheet and fundamentals stocks screener (25 results).
Does Charles Schwab Look Undervalued on Excess Returns?
The Excess Returns model looks at how much profit Charles Schwab can generate above the return that equity investors require, then ties that back to today’s $97.96 share price. On this view, the starting point is a book value of $25.42 per share and a stable book value estimate of $32.35 per share, paired with a stable EPS estimate of $7.65. With an average forecast return on equity of 23.65% and a cost of equity of $2.84 per share, the model assigns $4.81 per share to excess returns rather than just balance sheet value.
Because those projected excess returns are capitalised into the valuation, the Excess Returns model points to an estimated intrinsic value meaningfully above where Charles Schwab trades today. The recent record Q2 2026 earnings report, with higher net revenues and EPS plus fresh senior notes funding, helps explain why the model assumes Schwab can keep reinvesting at attractive rates even as the stock price lags that implied worth. Find out what Charles Schwab could be worth using our Excess Returns estimate.
The Charles Schwab Narrative: What Would Justify Today's Price?
Narratives pick up where the Charles Schwab valuation puzzle leaves off. They spell out which specific assumptions on future growth, profitability and earnings would need to hold for the share price to sit meaningfully above or below where it trades now, and each one treats fair value as a thesis about Schwab's business that you can watch over time rather than a single static estimate. Narratives live on Simply Wall St's Community page.
Community views on Charles Schwab split between those who see more upside left in the story and those who think the current price already bakes in a lot.
Bull case: 20% undervalued
"The real upside for Schwab isn’t tied to one quarter or one rate cut. It lies in the slow, steady expansion of participation in capital markets..."
Discover why this Narrative puts Charles Schwab at 20% undervalued.
Bear case: roughly fairly valued
"Heavy investment in AI, technology and new platforms such as spot crypto could overshoot sustainable demand. This may lead to structurally higher run-rate technology and personnel spending..."
Explore why this Narrative puts Charles Schwab at roughly fairly valued.
One more Charles Schwab check that belongs beside the valuation
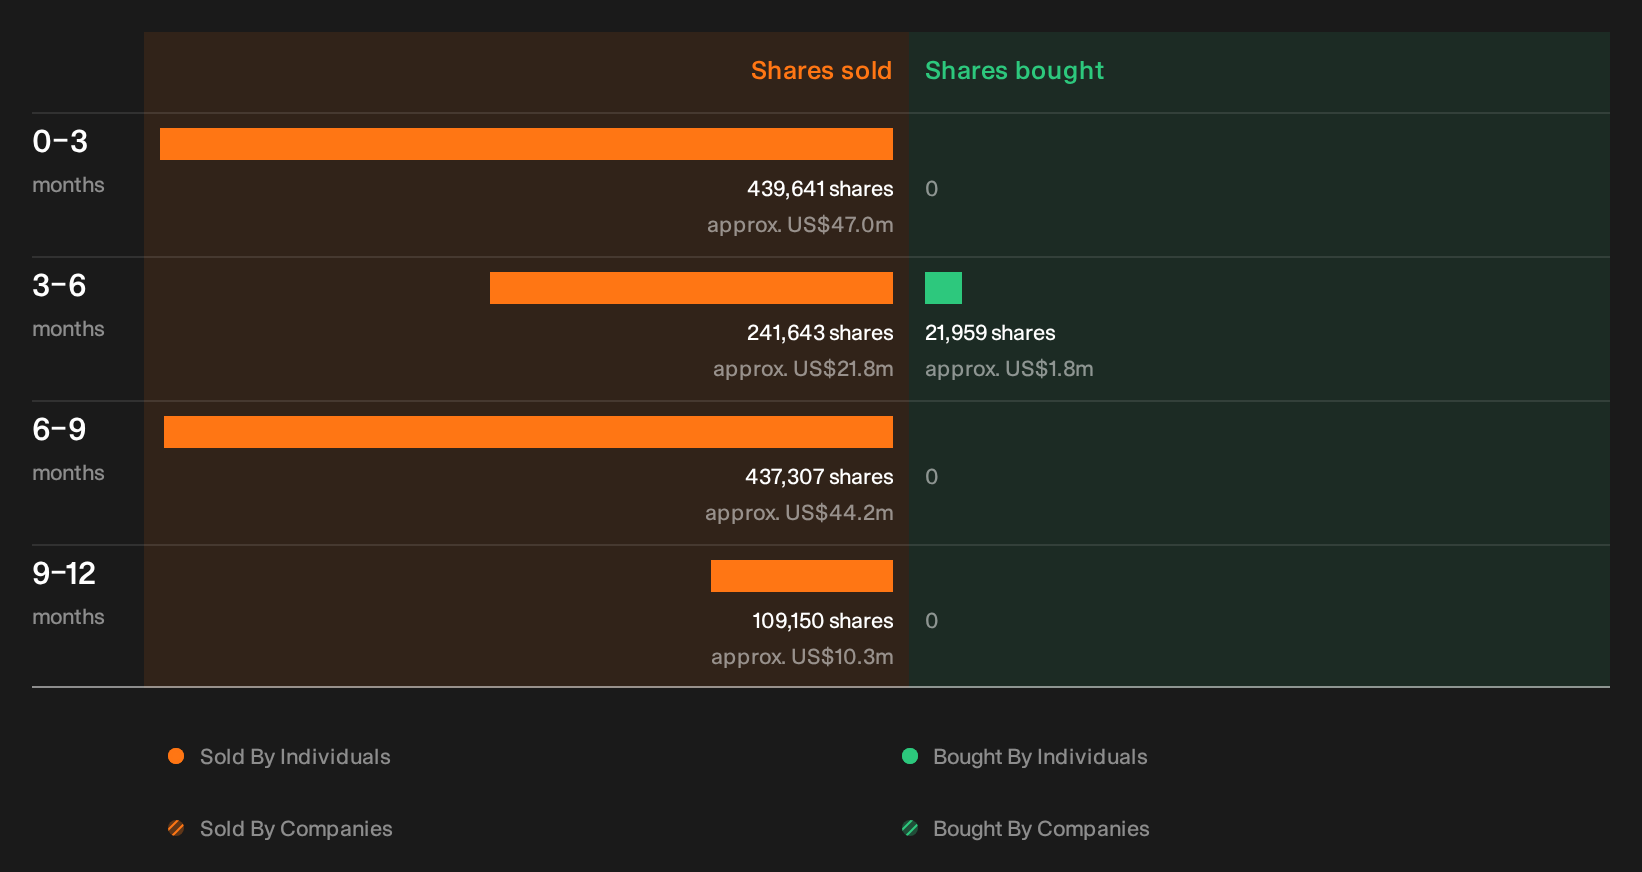
Before you close the file on Charles Schwab, there is one more signal to look at, because recent dealings by key insiders can add a very different layer to the story. See the recent insider selling flagged for Charles Schwab.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com