
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Nebius Group (NBIS) Stock Looks Overvalued Given Its Sales Base
Nebius Group has been one of the more eye catching AI infrastructure stocks in the past few years, and its surge has pushed a simple question to the front for investors who care about fundamentals. With the share price moving far ahead of where it was five years ago, the real issue is whether Nebius Group's current market value is justified by its sales base today.
- Over the past 5 years the stock has delivered a total return of 200.9%, which puts a lot of pressure on the underlying sales trajectory to support that kind of value creation.
- Recent headlines around rapid revenue growth, aggressive AI capacity build out and sizeable financing needs mean expectations for future sales and capital intensity can all feed directly into how investors think about the value they assign to each dollar of Nebius Group's revenue.
- There is a second opinion on Nebius Group worth weighing. See what analysts think Nebius Group's shares could be worth.
The stock's next move may depend on whether current sales and the price investors are paying for them can comfortably sit alongside each other.
If you want to pressure test Nebius Group's sales based valuation question against a broader AI infrastructure theme, compare it with a curated list of 91 AI infrastructure stocks.
Does Nebius Group Look Pricey on Sales?
P/S fits Nebius Group because investors are mostly paying for its current and potential revenue base rather than mature earnings.
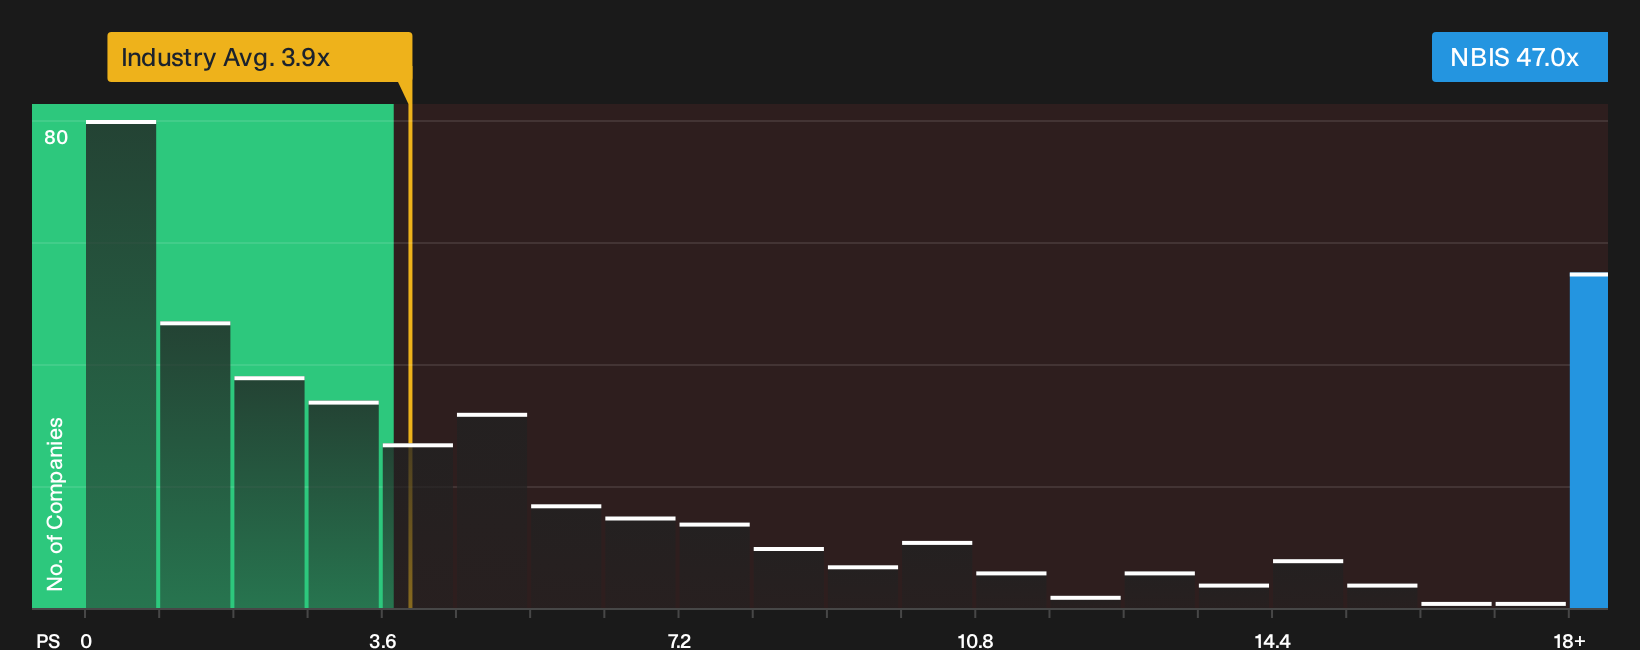
The stock trades on a P/S of 47.0x, which is far above the Software sector average of 3.9x and already well ahead of the peer group on 11.3x. Based on a tailored fair multiple that factors in Nebius Group's growth profile, margins, size and risk, the current P/S still screens as overvalued rather than simply reflecting its AI premium.
Despite the strong AI headlines around capacity expansion and recent upgrades, the gap between Nebius Group's P/S and more typical software and AI infrastructure peers implies investors are paying a very high price for each dollar of revenue today, so you need strong conviction about the durability of that top line to be comfortable here. Explore the numbers behind Nebius Group's P/S valuation.
The Nebius Group Narrative: What Would Justify Today's Price?
Nebius Group Narratives pick up where the P/S puzzle leaves off and spell out which combinations of future growth, profitability and earnings power would need to line up for the stock to be worth materially more or materially less than today's valuation. They sit on Simply Wall St's Community page. Each one connects its implied number to a clear view on how Nebius Group's revenue path, margin profile and risk picture might evolve, which you can revisit as fresh information arrives.
The community is split on Nebius Group, with one camp arguing the stock still has room to run and the other focused on funding and capital strain.
Bull case: 18% undervalued
"Hypergrowth in demand for AI compute and cloud infrastructure, as evidenced by exceptionally strong revenue growth and high utilization, suggests Nebius may benefit from long-term secular trends..."
Discover why this Narrative puts Nebius Group at 18% undervalued.
Bear case: 114% overvalued
"Surging capital expenditures, as evidenced by the company's commitment to $2 billion in 2025 alone and a massive multi-year plan to secure 1 gigawatt of power by 2026, will likely drive down free cash flow and pressure net margins for years..."
Explore why this Narrative puts Nebius Group at 114% overvalued.
One more piece to weigh for Nebius Group before you make a move
Before you lean too hard on today’s multiples, it is worth checking what professional forecasters think Nebius Group could look like a few years from now and how those expectations line up with current pricing. Explore where analysts expect Nebius Group to be in a few years.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com