
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Badger Meter (BMI) Following OneNetwork Launch Is The Valuation Story Changing
Badger Meter (BMI) just rolled out its OneNetwork software platform at WEFTEC in New Orleans, putting real-time monitoring and unified data analysis for water, wastewater and stormwater utilities in sharper investor focus.
For investors, the launch comes at a tougher time for Badger Meter, with the share price down about 29% year to date and the 1-year total shareholder return declining just over 30%. This suggests that momentum has faded even as the longer term 5-year total shareholder return remains positive.
Scan beyond Badger Meter and see how other water and infrastructure plays are setting up right now with the hand picked 39 power grid technology and infrastructure stocks in this space.
The share price reset and the fresh OneNetwork launch now pull Badger Meter into a clear tension. Has most of the easy upside already played out, or does the current valuation still leave meaningful room ahead?
Most Popular Narrative: 20.3% Undervalued
Against the last close of $124.89, the most followed narrative pegs Badger Meter’s fair value at $156.67, which reflects a higher valuation built on execution of awarded projects and a growing software mix rather than short term share price momentum.
The main factor that needs to go right is execution on the large cohort of awarded but not yet fully ramped AMI and sewer monitoring projects, including PRASA and the post UDlive sewer portfolio. The expectation is that the second half weighting in 2026 translates into sustained volume and software attachment over the next several years.
Badger Meter’s current valuation suggests that the market is only partially reflecting management’s high single digit organic growth framework and double digit Software as a Service ambitions, as well as the assessments from several research houses and independent analysts indicating that the stock trades below their estimates of intrinsic value.
See why 12 investors see Badger Meter as 20% undervalued.
Result: Fair Value of $156.67 (UNDERVALUED)
Still, Badger Meter’s story can fray if the large AMI and sewer awards ramp more slowly than analysts expect, or if legal actions start to pressure margins.
Find out about the key risks to this Badger Meter narrative.
Another View on Badger Meter’s Valuation
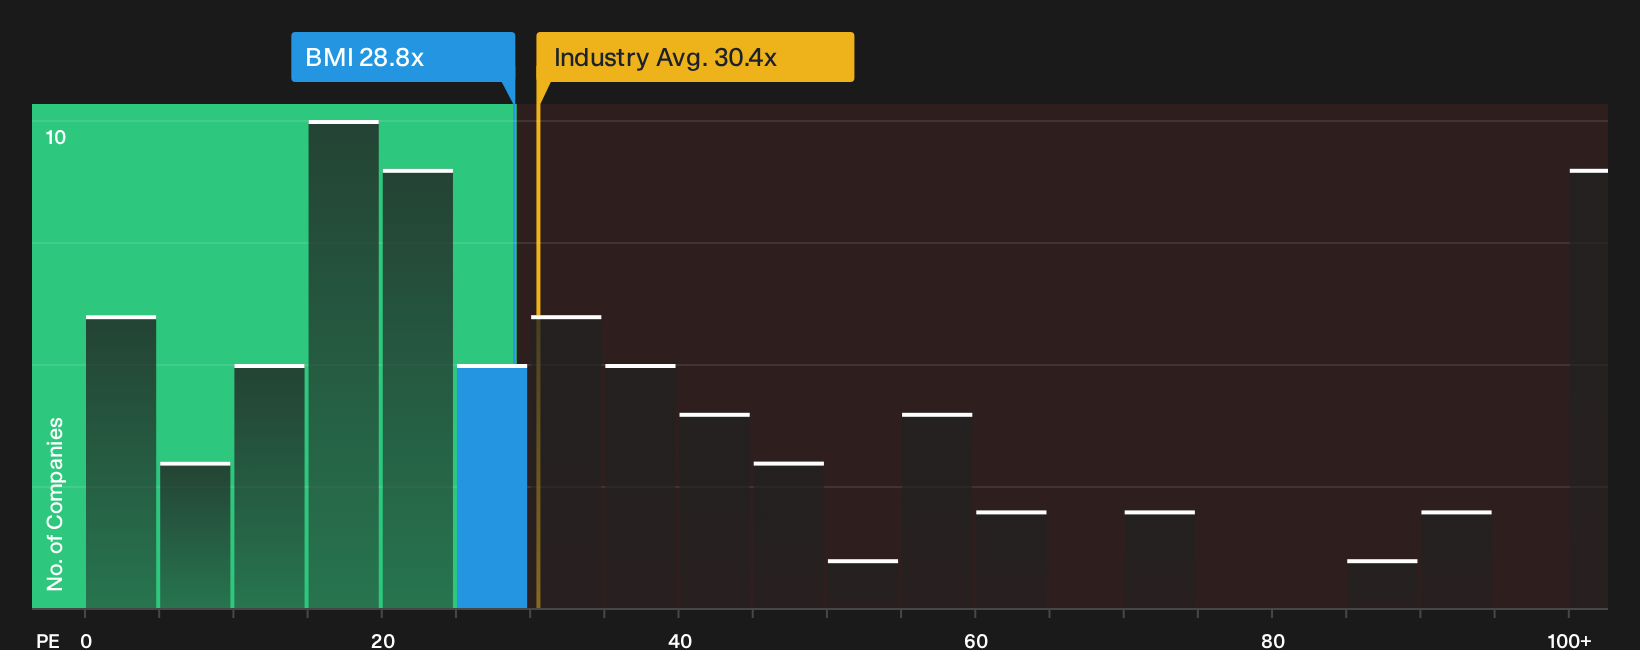
While the narrative around Badger Meter leans on fair value around $156.67 and an undervaluation of about 20%, the simple P/E picture is more mixed. The stock trades on roughly 28.8x earnings, which is cheaper than peer averages around 50.7x yet richer than a fair ratio closer to 24x. That gap suggests investors are paying up relative to the fair ratio even though the shares are priced below peers. This raises a basic question for you as a shareholder: is the quality premium worth that extra multiple risk today?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If the mix of optimism and caution around Badger Meter leaves you on the fence, go straight to the source data, compare the trade offs, and pressure test your own thesis against the 3 key rewards.
Looking for more investment ideas beyond Badger Meter?
Do not stop with Badger Meter. Use the Simply Wall Street Screener to spot fresh opportunities, compare risk profiles, and build a watchlist that fits your own investing style.
- Target potential mispricing by scanning a curated pool of companies that combine quality fundamentals with attractive valuations through the 27 high quality undervalued stocks.
- Strengthen portfolio resilience by focusing on financially sturdy businesses using the list of solid balance sheet and fundamentals (25 results).
- Hunt for lesser known opportunities with strong fundamentals before they are widely followed via the 19 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com