
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
3 Canadian Dividend Stocks With At Least 4% Yield
When U.S. Treasury yields hit a 24 year high, reliable income suddenly matters a lot more for investors who own Canadian shares. Higher global bond yields pull attention toward upfront cash returns. That creates a window for people who want steady dividend cheques from companies paying more than 3% and with room to keep those payouts going. This article highlights three such Canadian dividend stocks.
The three stocks covered below are just a starting sample. The full Dividend Powerhouses screen surfaced 18 more companies with similarly compelling income stories that are not included here. If you want to identify and analyze potential high conviction dividend ideas for yourself, head straight to the Dividend Powerhouses (3%+ Yield) screener.
Canadian Tire Corporation (TSX:CTC.A)
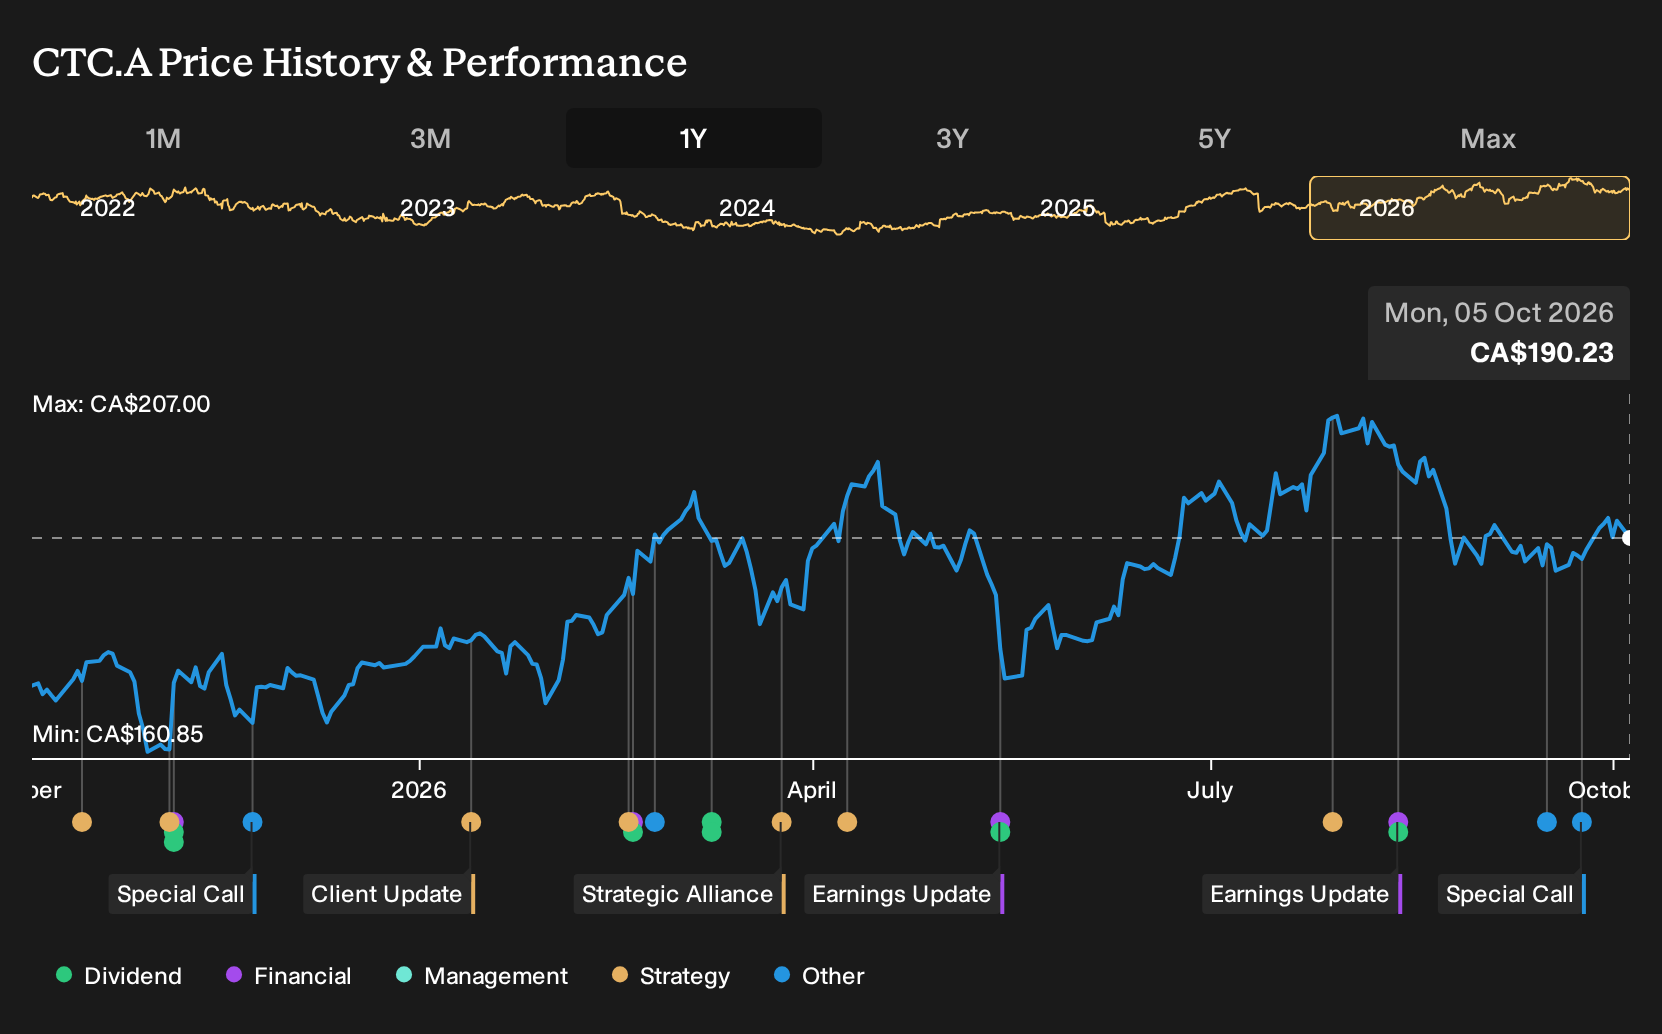
Canadian Tire Corporation brings together retail, credit cards, and real estate, and that last piece is what really matters for this dividend screen. CT REIT owns Canadian Tire anchored properties that generate steady rent, which helps support a 3% plus yield that aims to stay dependable.
Canadian Tire Corporation runs a broad retail network across banners like Canadian Tire, Mark's, SportChek, and Helly Hansen, while earning about CA$14.9b from Retail, CA$1.6b from Financial Services, and CA$618 million from CT REIT. Its market value sits near CA$10.1b.
"Investments in digital infrastructure, including store automation, omnichannel enhancements (same-day delivery, one-click checkout), and the rollout of advanced data analytics/AI tools, are improving operational efficiency. Over time, these are likely to be associated with higher sales and margin expansion, as e-commerce sales are already outpacing overall growth."
The real test for Canadian Tire investors is how one pressure on profitability plays out just as this dividend story looks more comfortable.
That pressure point is exactly what the full narrative unpacks in the full narrative for Canadian Tire Corporation, including how Canadian Tire Corporation’s cash engine could accelerate or stall from here.
Exco Technologies (TSX:XTC)
Exco Technologies designs and sells tooling, molds, and auto interior parts. Its Automotive Solutions arm produces high volume seating, cargo, and restraint components that help underpin dividend coverage. Automotive Solutions generates about CA$329 million of revenue, Casting and Extrusion adds roughly CA$316 million, and the group’s market value is around CA$315 million.
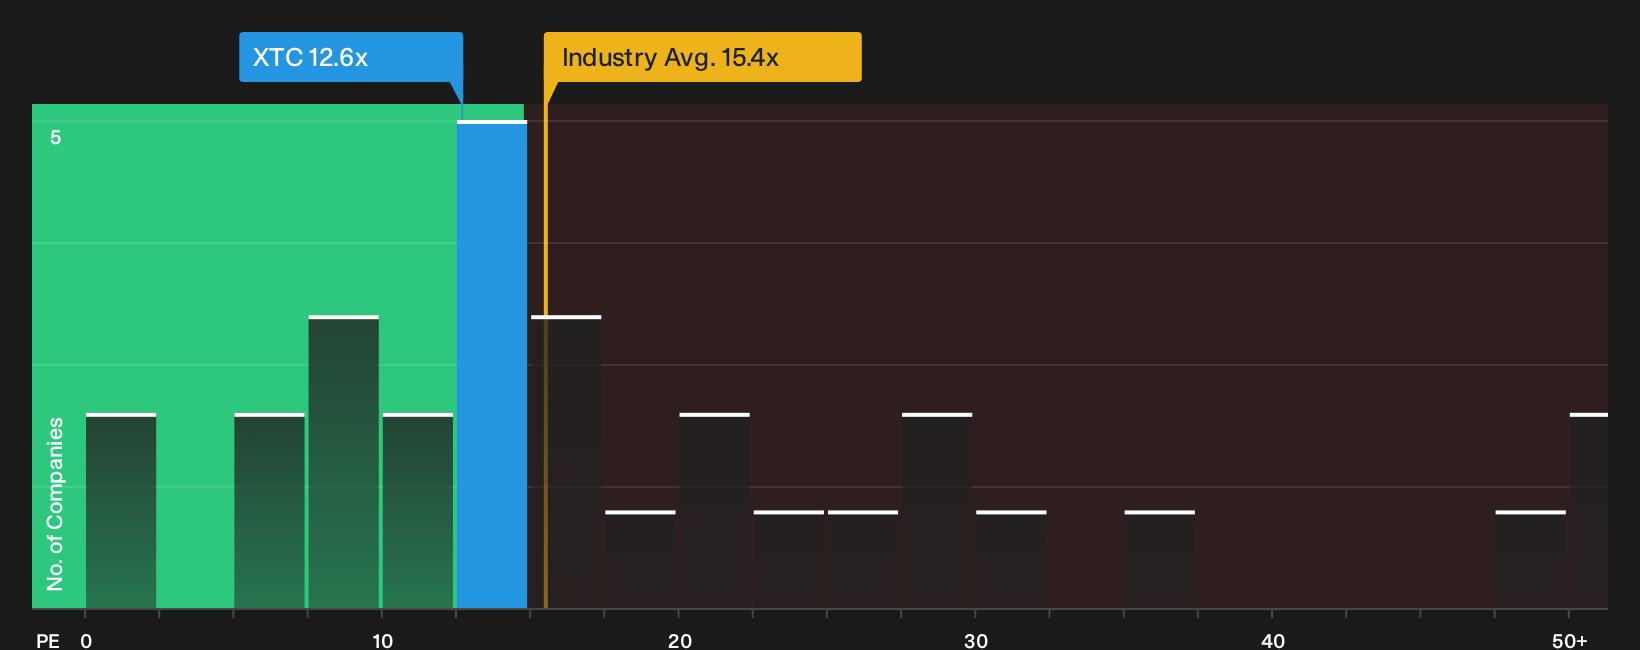
A 5.05% yield, recurring cash from Automotive Solutions, and a modest P/E of 12.6x against an industry average of 21.5x put Exco Technologies squarely in the Dividend Powerhouses bucket. Dividend stability leans heavily on what happens when that funding structure meets the next turn in borrowing costs.
That funding mix only tells part of the story, so check the 3 key rewards and 1 important major warning sign to see how Exco Technologies’ payout profile and rate sensitivity really line up.
Canadian Natural Resources (TSX:CNQ)
Canadian Natural Resources is built around large scale oil and gas production that throws off the kind of recurring cash flow income investors look for in a 3% plus dividend screen. That production backbone is what makes its payout story interesting right now.
Canadian Natural Resources develops and sells crude oil, natural gas and NGLs across Western Canada, the North Sea and Offshore Africa, with revenue anchored in North America at about CA$21.3b and oil sands mining and upgrading at roughly CA$20.8b, plus midstream and refining near CA$1.0b, and the stock carries a market value around CA$142.4b.
"Recent accretive acquisitions have expanded production and reserves with minimal increase to the 2025 capital budget, positioning Canadian Natural for immediate cash flow growth and increased future revenues as these assets are developed."
The real swing factor for Canadian Natural Resources is how one quiet shift in long term regulatory and carbon costs ultimately filters through to dividend headroom.
That quiet shift could reshape the whole payout story, so read the full narrative for Canadian Natural Resources to see how Canadian Natural Resources might maintain or enhance its dividend capacity despite rising long term costs.

Seeking Fresh Alternatives Before Others?
Fresh dividend ideas can move quickly, and attractive setups often gain traction once momentum builds. Review these under the radar picks before the broader market focuses on them.
- Target resilient balance sheets and steady cash engines by scanning the curated list of solid balance sheet and fundamentals (7 results) while valuations and entry prices still look reasonable for patient income hunters.
- Consider structural power demand and grid upgrade themes by reviewing the hand picked 39 power grid technology and infrastructure stocks before these infrastructure plays potentially become more widely followed.
- Explore long term copper demand themes by checking the curated 16 top copper producer stocks while these producers are still attracting relatively limited attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com