
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
HCA Healthcare's Q3 2026 Earnings: What to Expect
HCA Healthcare, Inc. (HCA), headquartered in Nashville, Tennessee, owns and operates hospitals and related healthcare entities. Valued at $92.4 billion by market cap, the company provides diagnosis, treatments, consultancy, nursing, surgeries, and other services, as well as medical education, physician resource center, and training programs. The healthcare service provider is expected to announce its fiscal third-quarter earnings for 2026 before the market opens on Tuesday, Oct. 27.
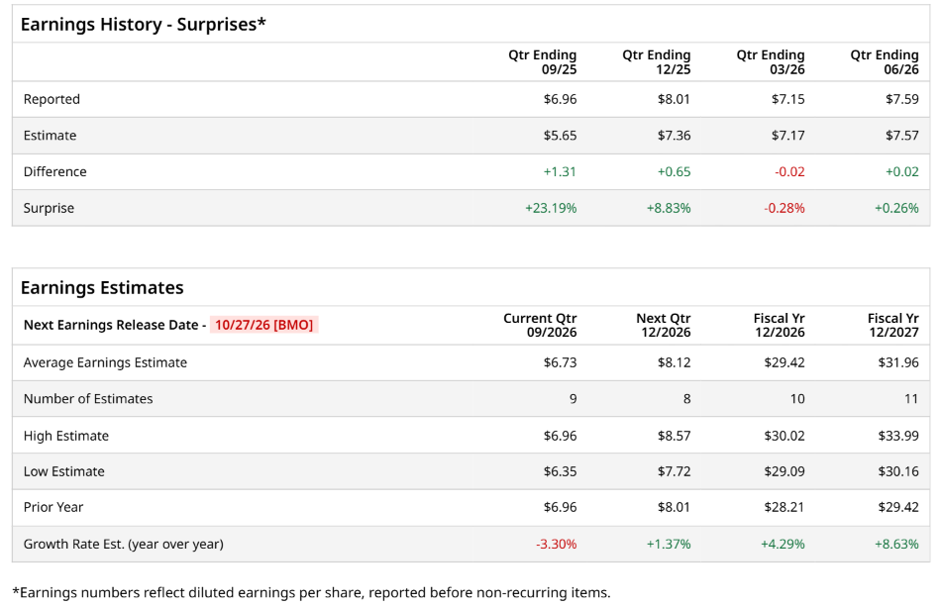
Ahead of the event, analysts expect HCA Healthcare to report a profit of $6.73 per share on a diluted basis, down 3.3% from $6.96 per share in the year-ago quarter. The company beat the consensus estimates in three of the last four quarters while missing the forecast on another occasion.
For the full year, analysts expect HCA Healthcare to report EPS of $29.42, up 4.3% from $28.21 in fiscal 2025. Its EPS is expected to rise 8.6% year over year to $31.96 in fiscal 2027.
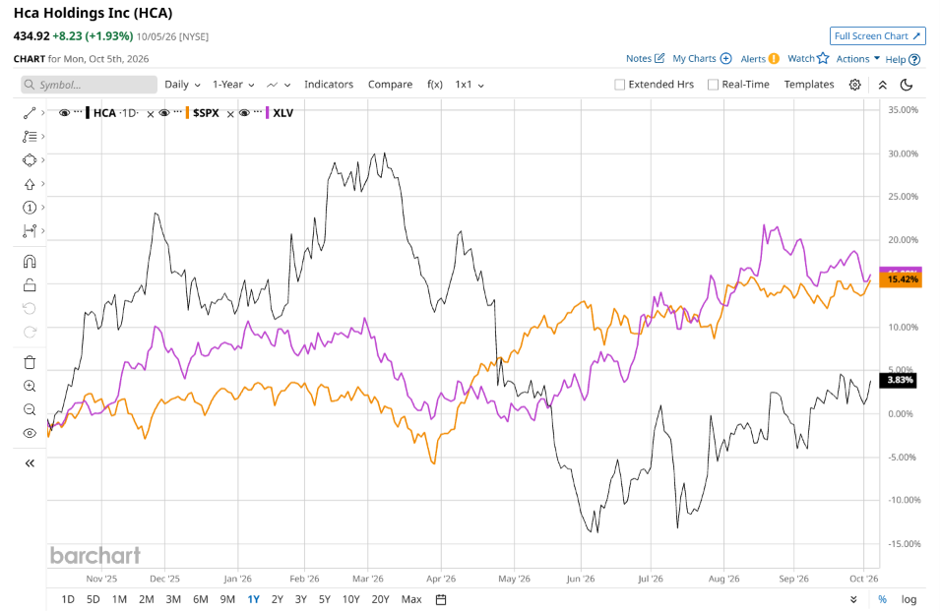
HCA stock has underperformed the S&P 500 Index’s ($SPX) 15.8% gains over the past 52 weeks, with shares up 1.3% during this period. Similarly, it underperformed the State Street Health Care Select Sector SPDR ETF’s (XLV) 15.6% returns over the same time frame.
HCA’s underperformance was primarily driven by a worsening payer mix, as millions of individuals lost coverage through health insurance exchanges following the expiration of Affordable Care Act subsidies. This shift toward uninsured or underinsured patients led to sharp declines in high-margin elective inpatient and outpatient surgeries, creating a broader-than-expected drag on reimbursement rates. Although steady growth in emergent surgical cases helped cushion these volume losses, management was ultimately forced to slash its full-year EPS guidance to a range of $28.70 to $30.50.
Analysts’ consensus opinion on HCA stock is reasonably bullish, with a “Moderate Buy” rating overall. Out of 26 analysts covering the stock, 14 advise a “Strong Buy” rating, one suggests a “Moderate Buy,” 10 give a “Hold,” and one recommends a “Strong Sell.” HCA’s average analyst price target is $458.22, indicating a potential upside of 5.4% from the current levels.
On the date of publication, Neha Panjwani did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.