
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Warren Buffett's Overlooked AI Race Pick
Key Points
Buffett's commentary implies he favors Alphabet over other hyperscalers in the AI space.
Credit default swaps pricing suggests Alphabet is financially stronger than Oracle.
Warren Buffett is a polite man, and the famed investor stated in a recent CNBC interview that he's not in the habit of "knocking the others" when it comes to the hyperscalers he might not favor investing in. However, while it's not clear which hyperscalers Buffett might not like, it's clear he likes Alphabet (NASDAQ: GOOG)(NASDAQ: GOOGL). Here's what he said.
Buffett initiated Berkshire Hathaway's position in Alphabet
The legendary investor made it clear in the interview that he initiated Berkshire Hathaway's position in Alphabet and fully supported Greg Abel in building the position to 106 million shares, equivalent to about $35.5 billion at the time of writing.
Missed AI’s "Act 1"? Act 2 Could Be 15x Bigger. Most investors think they missed the AI boat because they didn't buy Nvidia in 2005. But according to our analysts, we’re only at the end of "Act 1"—the R&D phase. "Act 2" is the global rollout. Continue »
The position is significant, and so is what Buffett said when asked about Alphabet and the other hyperscalers. He responded by saying that the others didn't "have any choice. They're now playing a game, in many cases, that they don't want to play," and then went on to describe how IBM had to change its business to meet its customers' demands.
Image source: The Motley Fool.
What it means to Alphabet and AI investors
One interpretation of these pieces is that Buffett likes Alphabet but thinks some of the other hyperscalers are being forced to win in the AI market because that's where their customers are heading. While it's important not to put words into Buffett's mouth, it's hard not to think that companies like Oracle (NYSE: ORCL) are what Buffett might be referencing.
Alphabet and Oracle credit default swaps
The difference between Alphabet and Oracle in the AI race is partly reflected in the rise in credit default swap (CDS) prices on both companies' 5-year debt. CDS are the price of insuring against a default in a company's debt, so a higher CDS reflects a greater level of skepticism over a company's debt.
The bond markets typically assume a 40% recovery rate when a bond defaults. Hence, Oracle's CDS of about 248 basis points (where 100 basis points equals 1%) implies an annual risk of 2.48/60 = 4.13%, and Alphabet's 72 bps implies 1.2%, giving a cumulative 5-year risk of 19% for Oracle compared to 5.9% for Alphabet.
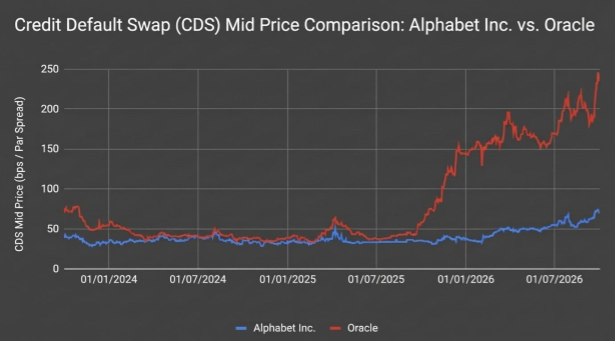
Data source: S&P Global Market Intelligence. Chart by the author.
Why Berkshire's pick, Alphabet, is the better AI choice
The difference in fundamentals between the two is also evident in the trajectories of each company's free cash flow (FCF) and capital spending, with Oracle burning cash as it ramps up AI spending to support a massive contract with OpenAI. In contrast, Alphabet is in a much better position, and although Wall Street expects a cash outflow in 2027, it's expected to start generating cash again in 2029.

Data by YCharts.
While it's important not to panic over Oracle, not least because the CDS data simply reflects pricing of risk, not necessarily the risk itself, it's clear that Alphabet is in a much better position to weather any slowdown of AI application spending in the market, and that's likely to suit Buffett and Berkshire better.
Lee Samaha has no position in any of the stocks mentioned. The Motley Fool has positions in and recommends Alphabet, Berkshire Hathaway, and Oracle. The Motley Fool has a disclosure policy.