
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
What Stanley Black & Decker's 26% Gain Can Still Teach You
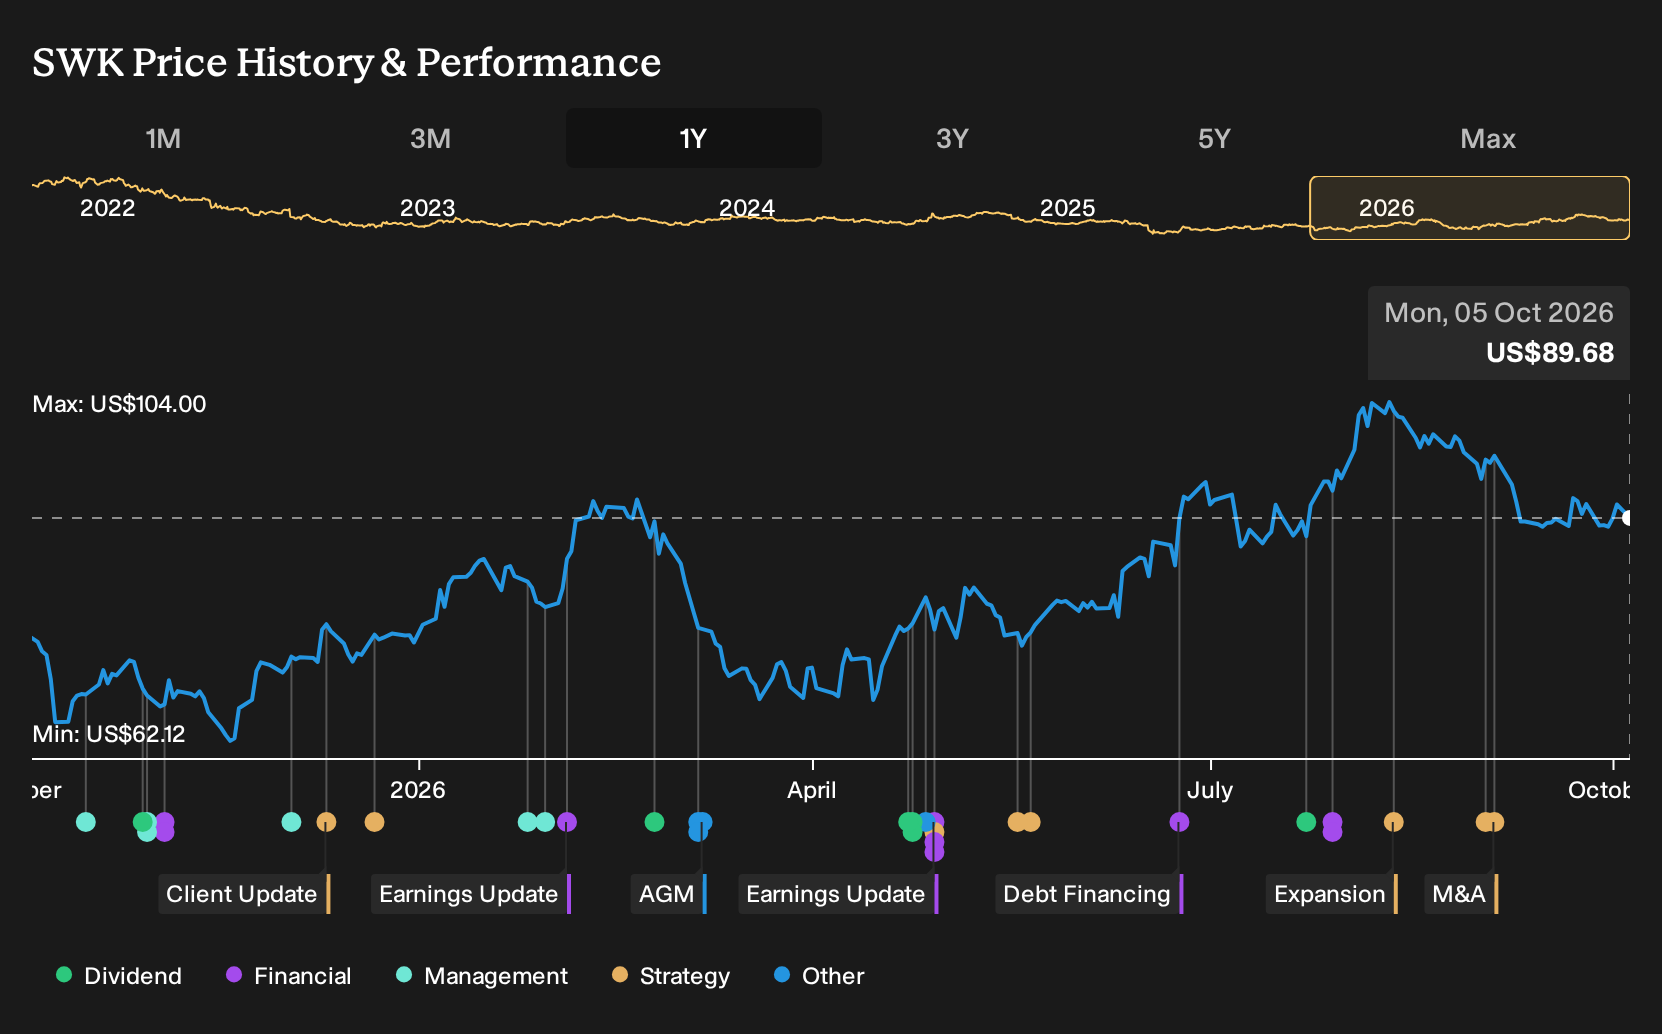
If Stanley Black & Decker was on your watchlist instead of in your portfolio, the outcome over the past year may feel like a missed call. Holding Stanley Black & Decker over the past year would have returned 25.8%, including dividends. That gain now raises a sharper question. Back on 5 October 2025, what clues in the debate over its manufacturing overhaul and push into digital tools could have helped you judge whether the supply chain reset would actually translate into stronger earnings power?
A Narrative on Simply Wall St is one investor's written case for a company, with its growth, margin and multiple assumptions spelled out. Those assumptions imply an estimated Fair Value.
Stanley Black & Decker has already moved. See which of 27 high quality undervalued stocks still trade below our estimates.
The Argument You Would Have Been Weighing On Stanley Black & Decker
The shares cost US$75.42 at the start of the period, and investors were split on what Stanley Black & Decker was really worth. One view said the tools group deserved a Fair Value of US$86.49, about 15% above the start price.
That bullish Narrative leaned on global urbanization, higher home ownership in emerging markets, and heavier investment in cordless power tools and digital workflow products such as MSUITE as potential drivers for long term demand.
The opposing, bearish case put Fair Value closer to US$64, roughly 15% below the start price, and focused on aging populations in the US and Europe plus ongoing tariff and supply chain cost pressures as potential threats to long term margins.
What The Results Changed For Stanley Black & Decker
The clearest data point for Stanley Black & Decker is the Q2 2026 net margin of 8.9%, up from 2.6% a year earlier. Profit rose to US$351.3m while revenue stayed close to flat at about US$3.9b. That shift in earnings quality supported parts of the optimistic case about margin repair, though flat sales and tariff pressures kept the cautious view alive. Overall, the evidence cut both ways.
The useful takeaway is where to look first. When a thesis turns on a manufacturing reset and digital tools, it can be helpful to track net margin and segment earnings rather than headline revenue or short term cost headlines.
What Today's Stanley Black & Decker Price Assumes
Stanley Black & Decker now trades at US$89.68, and the selected Narrative places its Fair Value above that level rather than below it. The current argument leans heavily on efficiency gains, tighter supply chains, and a bigger role for connected, pro-focused tools.
On that view, buyers at today’s price must judge whether the market still underestimates how far margin structure and product mix could shift if those changes stick.
"Analyst consensus expects $2 billion in cost savings by 2025 to drive margin improvement, but the extent of supply chain transformation and rapid localization could deliver gross margins above 35 percent well ahead of schedule and structurally reset net margins at a level not seen in over a decade due to breakthrough efficiencies and sustainably lower cost bases."
That disagreement has a full argument behind it. → Uncover the higher Fair Value this Narrative argues for
Where Stanley Black & Decker Leads Next
After looking at Stanley Black & Decker, you might wonder what powers the digital projects its tools help build.
Your drill or saw helps assemble a data center rack. Something else keeps that rack running safely, every hour of the day.
Specialist engineers design power systems and cooling gear so those facilities can handle dense computing loads without overheating.
They also provide monitoring and lifecycle services that help operators maintain uptime and fine tune efficiency.
If AI workloads keep climbing, that behind the scenes infrastructure role could matter even more.
One Narrative has already put a figure on it. → Uncover the company trading 38% below one Narrative's Fair Value
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com