
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Is Regions Financial (RF) A Bargain As Finance Leadership Changes Unfold?
Regions Financial (RF) just reshaped its finance bench by elevating long-time treasury executive Allen Mayer to Treasurer and hiring Craig Harrison to lead Corporate Finance, following Deron Smithy’s announcement of his planned 2026 retirement.
Regions Financial’s shares have eased in recent months, with a 30-day share price return down 11.01% and a 90-day share price return down 11.51%. At the same time, the 1-year total shareholder return of 8.91% and 3-year total shareholder return of 88.10% point to longer term momentum that investors are weighing against leadership changes and the current US$27.07 trading level.
Compare how Regions Financial’s leadership refresh stacks up against peers by scanning a curated group of banks with resilient balance sheets and fundamentals using our list of solid balance sheet and fundamentals (25 results).
For investors watching Regions Financial after the recent pullback and finance team reshuffle, the immediate fork in the road is simple: Does the current US$27.07 entry already reflect the risks, or does patience make more sense once the valuation is on the table?
Price-to-Earnings of 10.7x: Is it justified?
On simple earnings maths, Regions Financial trades on a P/E of 10.7x, which screens as inexpensive next to both peers and the wider US Banks industry.
P/E tells you how many dollars investors are currently willing to pay for each dollar of net profit. For a lender like Regions Financial, that figure effectively wraps together its earnings power, balance sheet risk and the market’s read on future profitability into one number that is easy to line up against competitors.
RF is flagged as trading at good value compared to peers and the industry, with its 10.7x P/E sitting below the US Banks industry average of 11.6x and the peer group average of 12.6x. The estimated fair P/E of 12.2x is also higher than where the stock is now, which indicates a level the market might move toward if sentiment and fundamentals remain aligned with current expectations.
Explore the SWS fair ratio for Regions Financial.
Result: Price-to-earnings of 10.7x (UNDERVALUED)
Still, Regions Financial faces clear swing factors, including the ongoing leadership transition in its finance ranks and recent share price weakness over the past quarter.
Find out about the key risks to this Regions Financial narrative.
Another view on Regions Financial’s value
On a cash flow lens, the picture looks different. Our DCF model points to a future cash flow value of $58.88 per share versus the current $27.07 price, which screens as materially undervalued. The question is whether those long range cash assumptions feel realistic to you.
Look into how the SWS DCF model arrives at its fair value.
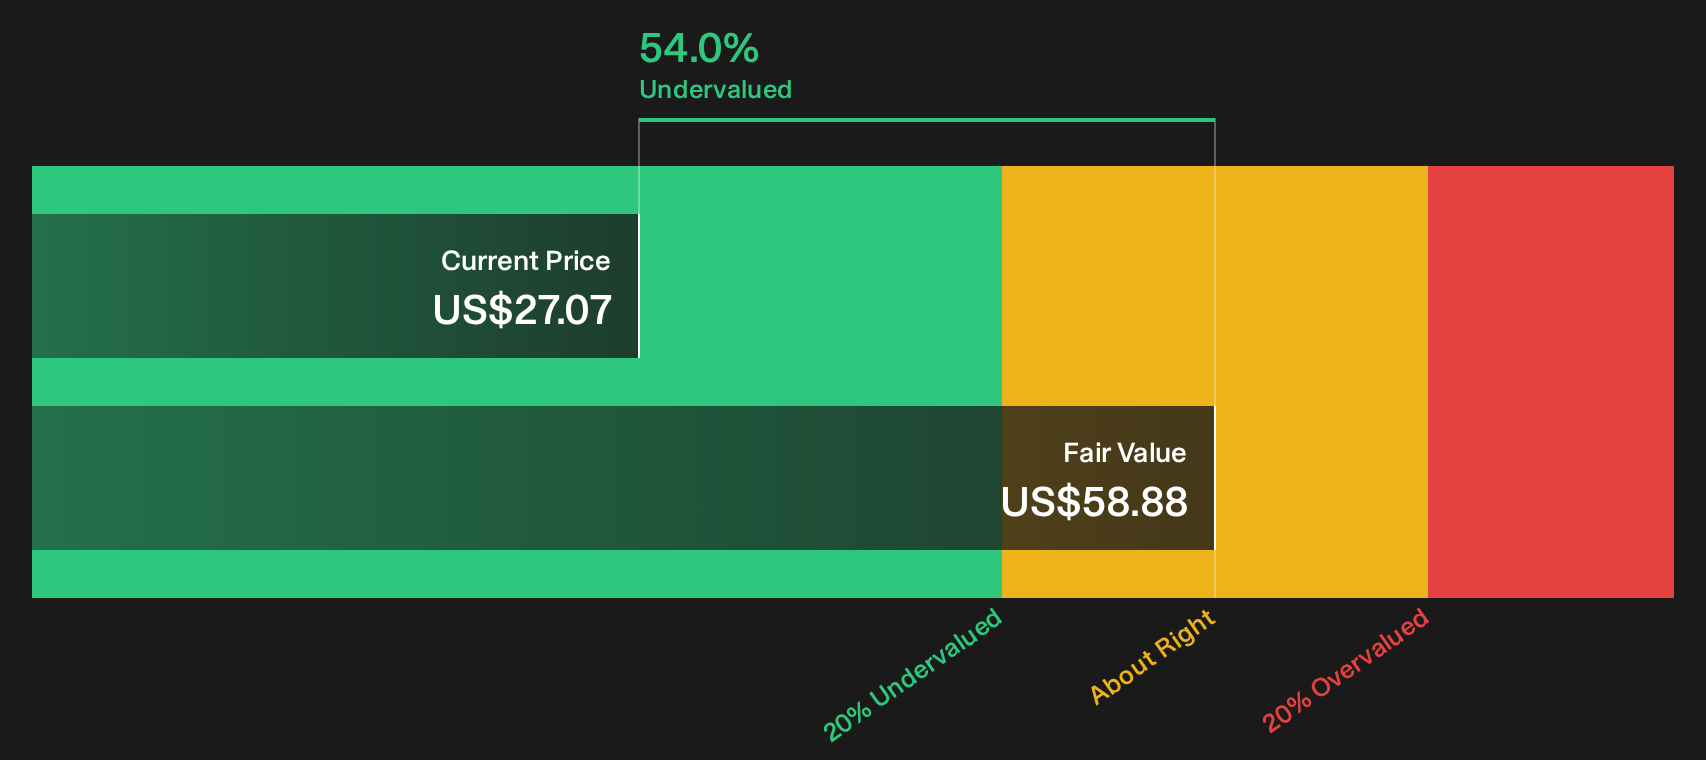
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Regions Financial for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 27 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Sentiment around Regions Financial in this piece may feel mixed, so move quickly and test the numbers yourself before they shift again. To unpack the optimism already reflected in our work, review the 4 key rewards
Looking for more Regions Financial style investment ideas?
If you are comparing Regions Financial with other opportunities, do not stop here. A wider watchlist built from clear data can sharpen every decision you make.
- Target potential mispricings by scanning companies that screen as 27 high quality undervalued stocks and see which ones match the quality bar you already expect from your holdings.
- Strengthen your income stream by zeroing in on firms that qualify as 7 dividend fortresses so your portfolio is working for you between market moves.
- Dial back risk without stepping away from opportunity by reviewing a focused group of 31 resilient stocks with low risk scores that could balance out more volatile positions.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com