
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Should New Idaho Distribution Center Require Action From Tractor Supply (TSCO) Investors?
- Tractor Supply opened its 11th distribution center in Nampa, Idaho, a US$200 million, 865,000 square foot facility serving 123 stores across nine states with capacity to support more than 200 locations.
- The Nampa site pairs KNAPP automated storage and retrieval systems with an on site AI Innovation Team, signaling a push to rewire Tractor Supply’s cost base and service levels through automation, data and energy efficient design.
- We will look at how Tractor Supply's investment narrative evolves as the AI enabled Nampa distribution hub begins to shape network efficiency.
Scan how Tractor Supply is wiring AI into logistics, then broaden your watchlist with 91 AI infrastructure stocks.
Tractor Supply Investment Narrative Recap
To own Tractor Supply, you need to believe the rural lifestyle model can work through softer consumer spending while management tightens costs and improves supply chain efficiency. The Nampa distribution center fits that belief, but the more pressing near term swing factor is whether traffic stabilizes after recent comparable sales softness in big ticket and discretionary categories.
The biggest risk right now is that weaker comps and a lower 2026 outlook collide with finite tariff refunds and higher transportation costs, putting more pressure on margins. If that happens, the Nampa AI enabled hub may matter tactically only at the margin in the short term, rather than changing the near term earnings story.
The most connected recent development is Tractor Supply’s plan to slow 2027 new store openings and close about 75 underperforming Petsense locations. That choice shifts capital away from footprint growth toward remodels, relocations and supply chain projects such as Nampa that can potentially improve returns on invested capital if executed well.
For you as a shareholder, the link is simple. Nampa is the operational expression of this capital reallocation and cost focused playbook. If remodels, Final Mile delivery and the growing pet ecosystem can help lift traffic while the new warehouse and tariff refunds support gross margin, the main near term debate narrows to how quickly comparable sales trends and earnings quality stabilize.
Tractor Supply's current analyst narrative points to revenues of US$18.0b and earnings of US$1.2b by 2029, based on an assumed 4.6% yearly increase in revenue and an earnings rise of about US$200m from the current US$1.0b level.
Uncover why Tractor Supply's fair value indicates a 13% potential upside to its current price that could narrow quickly.
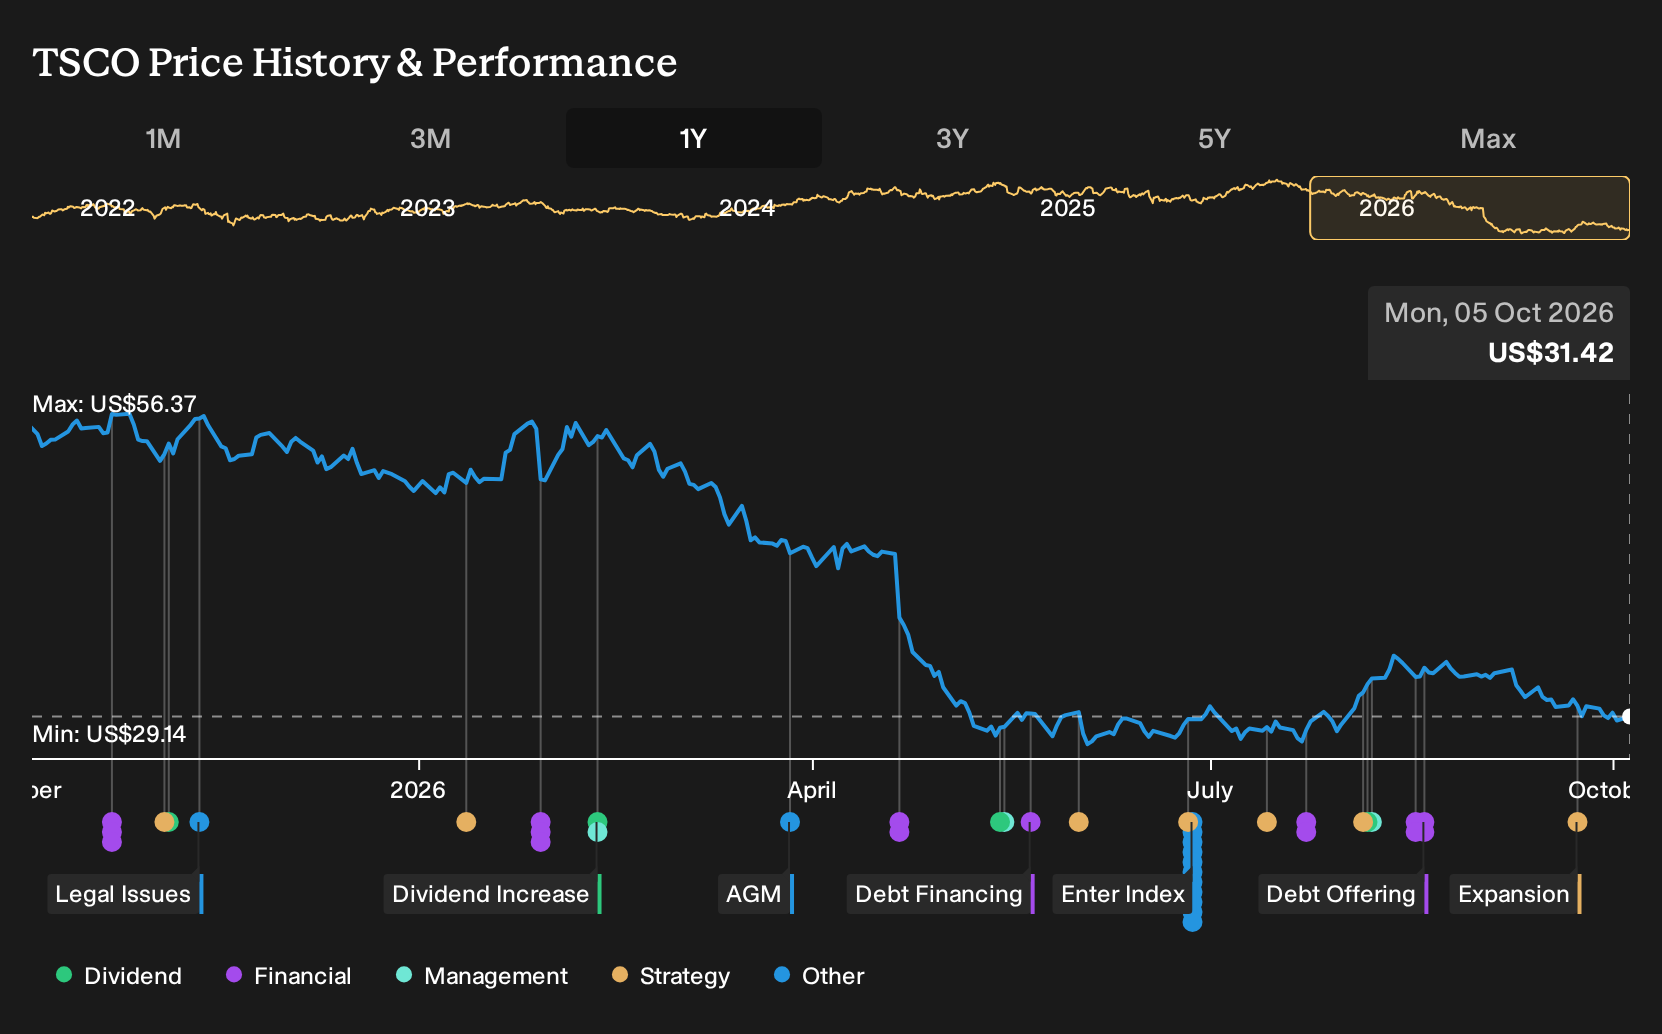
Exploring Other Perspectives
Some of the most optimistic analysts already built a story around Tractor Supply squeezing more value from pet, delivery and remodels. They were penciling in about US$18.5b of revenue and US$1.4b of earnings by 2029, well above consensus. The new AI heavy Nampa hub could cause those bullish or bearish views to shift again, so treat this as a moment to compare multiple narratives.
Explore 4 other Tractor Supply fair value estimates, including one that suggests as much as 27% upside from the current price.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so trust your own analysis.
- A great starting point for your Tractor Supply research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Tractor Supply. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Tractor Supply's overall financial health at a glance.
Looking for more Tractor Supply style investment ideas?
If you like Tractor Supply but want a broader watchlist, use this moment to scan other listed businesses with clear financial traits that match your own tolerance for risk and income needs.
- If you prefer to keep things steadier through different cycles and focus on balance sheet strength, then start with a 31 resilient stocks with low risk scores.
- If dependable income matters more to you than rapid capital gains, consider building a watchlist around 7 dividend fortresses that aim for higher yields.
- If you are hungry for opportunities the market may not be fully focused on yet, then broaden your research with a 19 high quality undiscovered gems that still screen well on fundamentals.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com