
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Caterpillar (CAT) Bets $1b On North Carolina As Undervalued View Holds
Caterpillar (CAT) just put a roughly US$1b project on the table in North Carolina, planning a new Sanford facility to expand compact track loader and telehandler production for its Cat Compact business.
The Caterpillar share price has climbed 41.73% year to date and the stock shows a 72.75% total shareholder return over the past year, while a 9.78% decline over 90 days hints at cooling short term momentum even as long term returns, including a 379.19% five year total shareholder return, remain strong.
Scan beyond Caterpillar and this North Carolina buildout by comparing it with 39 power grid technology and infrastructure stocks that could also benefit as construction, infrastructure and equipment demand keeps reshaping global power needs.
Caterpillar looks like a powerhouse, with a fresh US$1b commitment into compact equipment production and multi year returns to match. The real question is whether that strength is already fully reflected in today’s US$848 share price.
Most Popular Narrative: 13% Undervalued
Caterpillar’s most followed narrative points to a fair value of about $975.61 per share against the last close at $848.14. This frames the current price as a discount and depends on how long dated power and construction demand plays out.
The plan to increase large engine capacity to three times 2024 levels by 2030 and expand turbine capacity to 2.5 times 2024 levels, together with the restart of the 10 megawatt medium speed gas engine targeting about 1.5 gigawatts of shipments from Q4 2026, positions Caterpillar to serve future natural gas and gas compression demand and potentially lift revenue and free cash flow as these assets are deployed.
Find out how 216 investors see Caterpillar as 13% undervalued.
Result: Fair Value of $975.61 (UNDERVALUED)
Still, the Caterpillar story can change quickly if the forecast US$2.2b tariff burden squeezes margins or if long dated AI power orders fail to convert as expected.
Find out about the key risks to this Caterpillar narrative.
Another View on Caterpillar’s Valuation
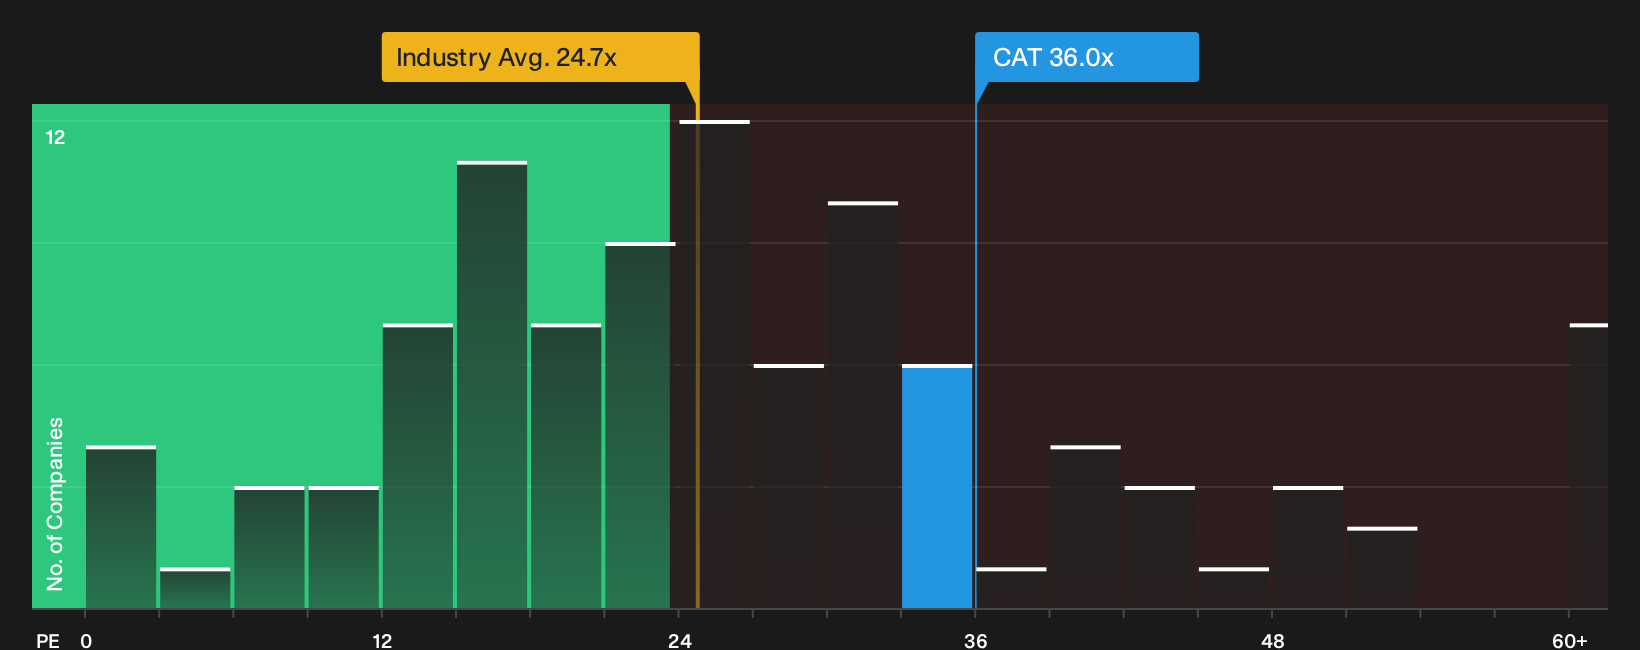
Multiples tell a different story for Caterpillar. The stock trades on a P/E of 36x, which is richer than both the US Machinery industry at 24.7x and the peer average at 26.6x, even though the fair ratio model suggests a higher 41.7x could be justified.
That gap cuts both ways. It hints at potential upside if the market leans toward the higher fair ratio. However, it also leaves less room for disappointment if earnings or sentiment cool. Which side of that trade off feels more realistic to you at today’s price?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If this Caterpillar setup appears finely balanced between opportunity and risk, review the data promptly and develop your own view using 3 key rewards and 1 important warning sign.
Looking for more Caterpillar sized investment ideas?
If Caterpillar has sharpened your focus on quality opportunities, do not stop here. Use the Simply Wall Street Screener to pressure test fresh ideas across income, value and resilience.
- Target reliable income streams by scanning companies with a track record of strong payouts using the 7 dividend fortresses.
- Hunt for potential mispriced opportunities by sorting through a curated pool of quality companies screened as 27 high quality undervalued stocks.
- Prioritise staying power in tougher conditions by focusing on businesses highlighted in the 31 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com